How Mileage Tiers Work for Classic Cars
It's a common worry for classic car owners: you've finally got your dream machine, polished and ready for the open road, but then you hit the roadblock of insurance. Many traditional insurers just don't "get" the classic car lifestyle, trying to pigeonhole your prized possession into a standard policy that penalizes you for every mile. Understanding how mileage tiers work for classic car insurance is crucial to getting the right coverage without unnecessary restrictions or inflated costs, ensuring you can enjoy your vintage ride responsibly and affordably.
Understanding Classic Car Insurance Mileage Tiers
When you insure a modern daily driver, the expectation is that you'll use it for commuting, errands, and general transportation. Insurance premiums are often calculated assuming regular, high mileage, and standard depreciation. However, classic cars are a whole different beast. They're typically not daily drivers; they're cherished investments, weekend cruisers, or show vehicles. This is where classic car insurance, and specifically its mileage tiers, really shines, offering policies tailored to the unique way these vehicles are used.
What Are Mileage Tiers?
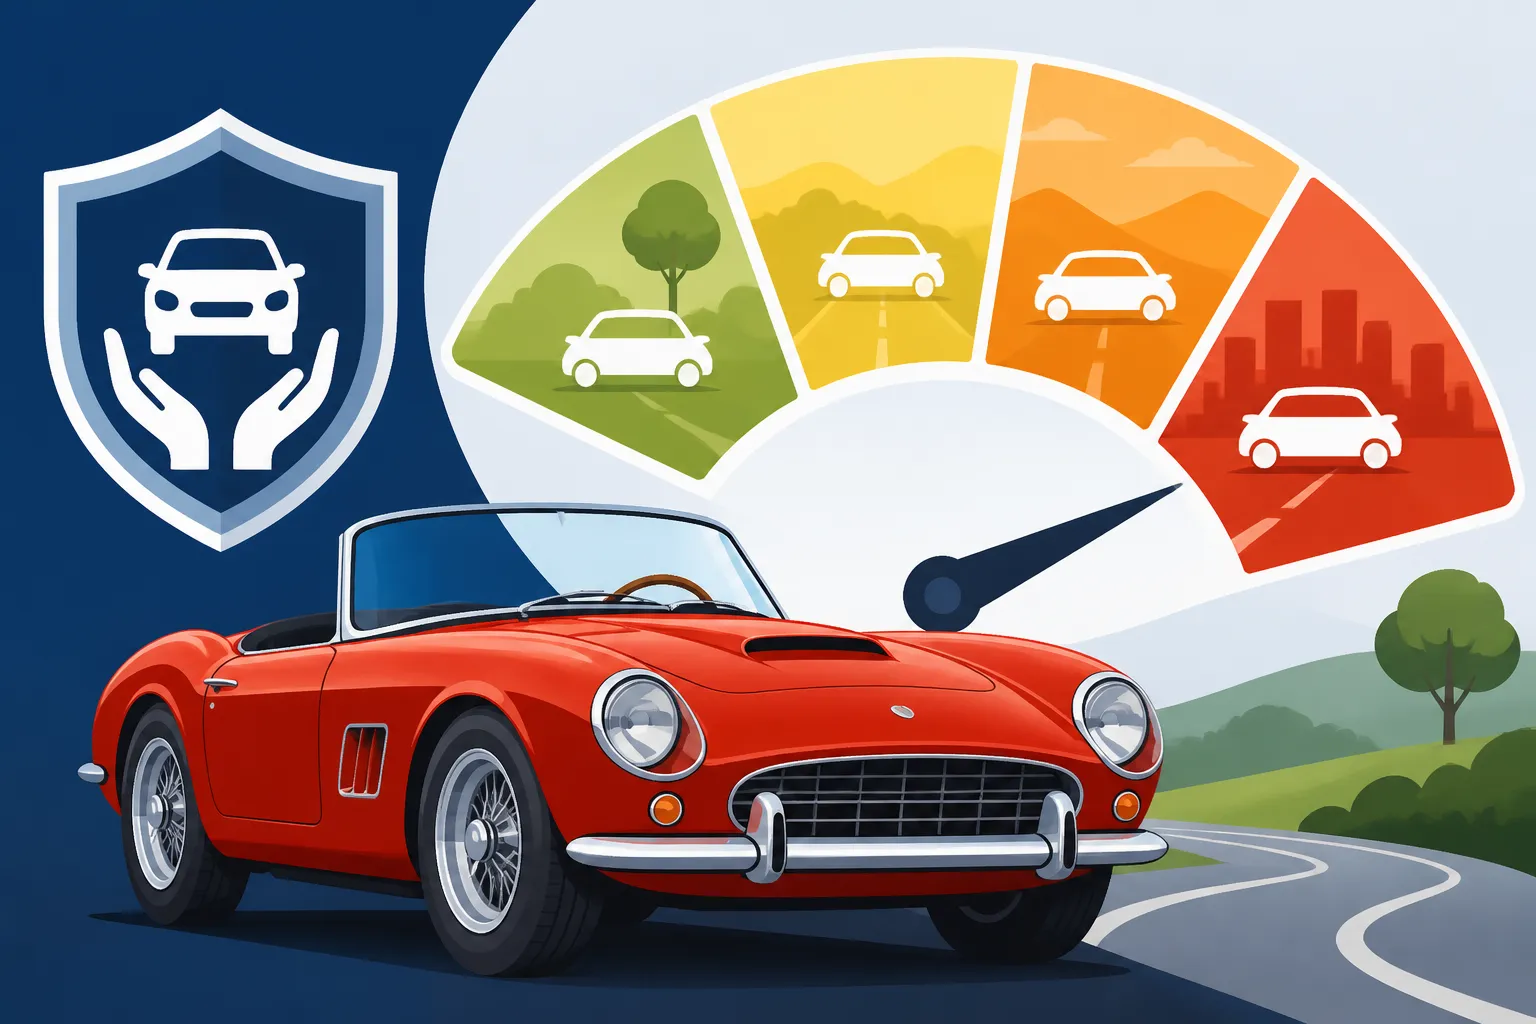
Mileage tiers are essentially different categories of annual driving limits that classic car insurance providers offer. Instead of a one-size-fits-all approach, these tiers acknowledge that some collectors drive their cars more than others, but still not in the same way a daily commuter would. These tiers allow you to choose a coverage level that accurately reflects how much you plan to drive your classic vehicle each year. The lower the mileage tier you choose, generally, the lower your premium will be, as it signals less exposure to risk for the insurer. It’s a smart way to match your insurance cost to your actual usage, which is often very limited for these special vehicles.
For example, a company like Hagerty understands that a pristine 1967 Corvette that only comes out for weekend shows and an occasional sunny Sunday drive will have a vastly different risk profile than a new sedan driven daily in rush hour traffic. They've built their policies around this understanding, offering a range of mileage options to suit every type of collector, from the garage queen to the occasional tourer.
Why Do Mileage Tiers Exist for Classic Cars?
The existence of mileage tiers is rooted in the fundamental difference in how classic and modern vehicles are used and valued. Traditional auto insurance often bases its payout on Actual Cash Value (ACV), which means if your car is totaled, you get its depreciated value, and mileage significantly contributes to that depreciation. For a classic, however, high mileage doesn't necessarily devalue it in the same way; in fact, its value often appreciates. Classic car insurance operates on an "Agreed Value" basis, meaning you and the insurer agree on the car's value before a loss occurs. Mileage tiers help maintain this agreed value by ensuring the car is driven within parameters that align with its status as a collector's item, reducing the likelihood of wear-and-tear related claims or accidents from excessive use.
Beyond the financial aspect, mileage tiers also tie into the "pleasure use" requirement that many specialty insurers and even some state registration programs impose. If your state offers special Historic Vehicle Registration Explained, it often comes with stipulations that the vehicle is used for parades, exhibitions, club activities, or occasional pleasure drives, explicitly excluding regular commuting. Insurance mileage tiers align perfectly with these expectations, offering a flexible yet controlled way to enjoy your classic without violating policy terms or state regulations. This symbiotic relationship ensures that your insurance coverage supports the very definition of a classic or antique vehicle as recognized by both the insurance world and governmental bodies.
Navigating Different Mileage Tiers and Their Impact
Choosing the right mileage tier is more than just picking a number; it's about honestly assessing your driving habits and understanding the implications for your coverage and premiums. It’s a crucial step in ensuring your classic car insurance truly fits your needs without leading to unexpected issues down the line.
Common Mileage Tier Options
Specialty classic car insurers offer a variety of mileage tiers designed to cater to different levels of usage. While the exact numbers might vary slightly between providers, here are some common categories you’ll encounter:
- Ultra-Low Mileage (e.g., 1,000 miles or less per year): This tier is perfect for the purest "garage queen" – a show car that sees very limited road time, primarily for local car shows, short parades, or a quick spin to keep the fluids moving. If your 1957 Chevrolet Bel Air rarely leaves the garage except for concours events, this might be your sweet spot.
- Low Mileage (e.g., 2,500 miles per year): This is a popular option for many collectors. It allows for regular weekend cruises, club events, and a few regional tours without feeling overly restricted. You might take your 1969 Camaro to a few car shows within a 100-mile radius, enjoy leisurely drives, and attend local meet-ups.
- Moderate Mileage (e.g., 5,000 miles per year): This tier provides more freedom for those who love to drive their classics a bit more often. It’s suitable for longer road trips, more frequent pleasure drives, and participation in various rallies or multi-day tours. This could be ideal if you frequently drive your vintage Porsche 911 on scenic routes or take it to a major national classic car show that's a few states away.
- Flexible or Unlimited Mileage: Some insurers, like Hagerty, understand that some collectors might not want a strict mileage cap or might have a specific classic that they enjoy driving more frequently, though still not as a daily driver. These options provide greater flexibility, though they typically come with a higher premium. While not truly "unlimited" in the daily driver sense, they offer significant allowances that remove the anxiety of constantly checking your odometer. This is distinct from Unlimited Mileage Classic Car Insurance Explained, which refers to policies with no stated annual cap but still imply limited recreational use.
It's important to remember that these mileage caps are annual. So, if you choose a 2,500-mile tier, you have that entire allowance to use throughout your policy period, not per month.
How Mileage Tiers Impact Your Premiums
The direct correlation between your chosen mileage tier and your insurance premium is one of the most significant factors in classic car insurance costs. This is a core reason Why Classic Car Insurance Is Cheaper Than Regular insurance. Here's why:
- Reduced Risk of Accidents: Simply put, the fewer miles a car is driven, the less exposure it has to accidents. Less time on the road means less chance of collision, theft, or other incidents, which translates to lower risk for the insurance company.
- Lower Wear and Tear Claims: While classic car insurance primarily covers major losses like accidents or theft, lower mileage also reduces the likelihood of minor claims related to wear and tear that might be covered under certain circumstances, or at least reduces the overall stress on the vehicle's components.
- Alignment with Collector Status: Insurers view limited mileage as a key indicator that the vehicle is indeed a cherished collectible, not just an old car. This commitment to preservation often comes with a financial reward in the form of lower premiums.
Choosing a lower mileage tier often results in substantial savings. For instance, opting for a 1,000-mile limit over a 5,000-mile limit for the same vehicle can lead to a noticeable difference in your annual premium. It's all about finding the sweet spot where your driving habits align with an affordable premium.
| Mileage Tier (Approximate) | Typical Use Case | Premium Impact (Relative) | Common Driver Profile |
|---|---|---|---|
| Under 1,000 miles | Concours, static shows, occasional short drives | Lowest | Collector with multiple vehicles, show competitor |
| 1,000 – 2,500 miles | Weekend cruising, local/regional shows, club events | Low | Enthusiast who enjoys driving but prioritizes preservation |
| 2,500 – 5,000 miles | Longer road trips, more frequent pleasure driving, rallies | Moderate | Active driver, enjoys touring and longer events |
| 5,000+ or Flexible | Extensive touring, occasional longer trips, less strict use | Higher | Enthusiast who values freedom, still not a daily driver |
Choosing the Right Mileage Tier for Your Classic
Selecting the appropriate mileage tier is a crucial decision that can save you money and headaches. It requires an honest assessment of how you truly intend to use your classic and a good understanding of what factors might influence your driving.
Factors to Consider When Estimating Your Mileage
Before you commit to a mileage tier, take a moment to really think about your classic car habits. Don't just pick the lowest number to save a few bucks, because underestimating can lead to major problems.
- Your Driving Style: Are you the type who only brings out your classic for pristine weather and special events? Or do you enjoy longer, more frequent drives? If you own a vintage Mustang and love taking it on scenic routes every other weekend, a 1,000-mile limit will feel incredibly restrictive. Conversely, if your car is a true museum piece, rarely trailered to a single show a year, even 1,000 miles might be too much.
- Types of Events You Attend: Consider the car shows, club meets, and rallies you plan to participate in. A single multi-day rally might easily put hundreds of miles on your odometer. Major national shows, especially if they require driving a significant distance, can quickly eat into your allowance. If you plan to attend the Woodward Dream Cruise in Michigan from out of state, for example, those travel miles add up.
- Geographic Location and Weather: If you live in a region with long winters, your driving season might be naturally shorter, making a lower mileage tier more feasible. Conversely, in sunny states like Florida or California, where classic car events happen year-round, you might find yourself driving more than anticipated. Consider how your local climate impacts your car's availability for Seasonal Driving Coverage Explained.
- Purpose of Ownership: Is this a collector's investment, a weekend toy, or a car you want to pass down to your children and occasionally drive with them? The purpose dictates the use. A cherished heirloom might see fewer miles than a fun project car you just want to cruise.
The Risks of Underestimating Your Mileage
It might be tempting to select the lowest mileage tier to get the cheapest premium, but this can backfire spectacularly. If you exceed your declared mileage limit, you could face severe consequences:
- Policy Violation: Most classic car insurance policies clearly state that exceeding your mileage limit is a violation of the terms. This can lead to your insurer refusing to pay a claim if an incident occurs while you're over the limit. Imagine crashing your prized 1970 Challenger, only to find your policy is void because you drove 2,600 miles on a 2,500-mile limit. That's a collector's nightmare.
- Retroactive Premium Adjustments: Some insurers might allow you to adjust your mileage mid-term, but they could charge you a higher premium retroactively for the entire policy period, negating any initial savings.
- Policy Cancellation: In more extreme or repeated cases, the insurance company could choose to cancel your policy altogether, making it harder to find coverage in the future.
It's always better to be honest, or even slightly overestimate, your mileage needs. The slight increase in premium is a small price to pay for peace of mind and valid coverage.
Adjusting Your Mileage Tier
Life happens, and your driving plans might change. You might unexpectedly decide to enter your classic in a cross-country rally, or perhaps you bought a second classic and now divide your driving time differently. Most specialty classic car insurers are flexible. If you realize you're approaching your limit or need more miles, contact your insurer immediately. Companies like Hagerty are usually very accommodating and can adjust your mileage tier mid-policy, though a premium adjustment will likely follow. Don't wait until you've exceeded the limit to make the call.
Mileage Tracking, State Requirements, and Enforcement
The idea of mileage tiers often brings up questions about how insurance companies keep tabs on your driving and how these tiers interact with state regulations for classic vehicles. It's a valid concern, and transparency here is key to a smooth insurance experience.
How Insurers Track and Monitor Mileage
You might wonder, "How do they even know how many miles I've driven?" The process is generally straightforward and relies on a combination of trust and verification:
- Odometer Readings: When you first obtain your classic car insurance policy, your insurer will typically ask for an initial odometer reading. This serves as your baseline. At renewal, they'll ask for another reading. This simple comparison confirms your annual usage.
- Self-Reporting: A large part of classic car insurance operates on an honor system. Insurers trust that you, as a responsible collector, will accurately report your mileage and adhere to the agreed-upon limits. They understand that classic car owners are usually meticulous about their vehicles and want to protect their investments.
- Occasional Verification: While not every policyholder will be subjected to an annual in-person inspection, insurers may, at their discretion, request updated photos of your odometer or even arrange for an appraisal that includes mileage verification. This is more common if there's a claim or if there's reason to suspect a discrepancy. Keep detailed records of your classic car's maintenance and usage, as this can help corroborate your mileage reports.
The key takeaway here is that honesty is the best policy. Misrepresenting your mileage can lead to significant issues if you ever need to file a claim.
State Regulations and Mileage Restrictions
While mileage tiers are a feature of insurance policies, they often align with broader state-level requirements for classic, antique, or historic vehicle registration. Many states offer special license plates for these vehicles, which come with specific usage restrictions that implicitly involve limited mileage.
For instance, in states like Pennsylvania, an antique vehicle (generally 25 years or older) registered with an antique plate is often restricted to "use for shows, exhibits, club activities, parades, and other functions of public interest and occasional pleasure driving." This phrase, "occasional pleasure driving," is open to interpretation but clearly rules out daily commuting. Similarly, Classic Car Insurance Requirements in Florida often cater to cars under specific mileage use for collector's purposes.
Consider the following aspects of state regulations:
- "Not for Daily Driver" Clauses: Many states explicitly state that vehicles with antique or historic plates cannot be used for routine transportation or commuting to work. This directly supports the low-mileage philosophy of classic car insurance. For detailed information, you can read about the Daily Driver Requirement Explained.
- Pleasure Use Requirements: The concept of "pleasure use" is central. This means driving for enjoyment, attending events, or maintaining the vehicle, rather than using it as primary transportation. Your insurance mileage tier should reflect this kind of use. For more on this, check out our guide on the Pleasure-Use Requirement Explained.
- Emissions and Safety Exemptions: Often, vehicles registered with historic plates are exempt from certain emissions testing or safety inspections. This exemption is usually predicated on their limited use, reinforcing the idea that they aren't driven frequently enough to warrant the same regulatory oversight as daily drivers. For example, Classic Car Emissions Test Exemptions by State can significantly impact classic car ownership.
It’s crucial to understand that your insurance mileage tier should not only fit your personal driving habits but also adhere to any specific state requirements for your classic vehicle's registration. If your state's regulations imply "limited use," choosing a higher mileage tier that suggests more frequent driving might raise questions from your insurer or state authorities, even if not an explicit contradiction. Always ensure your insurance policy and vehicle registration are in harmony.
Final Considerations for Your Classic Car Mileage Tier
Choosing the right mileage tier is a nuanced decision, reflecting both your passion for driving and your commitment to preserving your classic. It's about finding that sweet spot where enjoyment meets responsible ownership and smart insurance.
How Mileage Affects Other Policy Aspects
Your chosen mileage tier doesn't just impact your premium; it can indirectly influence other aspects of your classic car policy:
- Roadside Assistance: While most classic car policies, including those from providers like Hagerty, offer specialized roadside assistance (often flatbed towing, which is essential for classics), the frequency of its use might be lower with lower mileage tiers. However, don't skimp on this coverage, as breakdowns can still happen, regardless of how far you drive.
- Trip Interruption Coverage: If you opt for higher mileage tiers because you plan on longer tours or rallies, you might want to consider Trip Interruption Coverage for Classic Cars Explained. This add-on provides reimbursement for expenses like lodging, meals, and alternative transportation if your classic breaks down far from home.
- Coverage for Events and Tours: If your mileage tier allows for extensive driving to shows and tours, ensure your policy also explicitly covers these activities. Most specialty insurers understand this type of use, but it's always good to confirm your Classic Car Show and Event Coverage Rules.
Long-Term Planning and Your Mileage Tier
As a classic car owner, you're not just thinking about this year's drives; you're thinking about the next five, ten, even twenty years.
- Value Appreciation: Classic cars, unlike daily drivers, can appreciate in value. As your car's value grows, your Agreed Value coverage should be updated. While mileage doesn't directly impact this appreciation, maintaining lower mileage can contribute to the car's overall pristine condition, which supports higher valuations. Regularly reassessing your car's value and updating your policy is a good practice. Learn more about How Agreed Value Is Determined.
- Future Driving Goals: Do you foresee yourself taking your classic on more extensive road trips in the future, perhaps once you retire? Or do you plan to eventually pass it on to a family member who might have different driving habits? Thinking ahead can help you understand if you'll need to adjust your mileage tier in the coming years.
Ultimately, classic car insurance mileage tiers are designed to offer flexibility and cost savings while recognizing the unique nature of collector vehicles. By understanding how they work, choosing wisely, and communicating openly with your insurer, you can ensure your classic is perfectly covered for all the joy it brings.
Disclaimer
Please note that this article provides general information about classic car insurance mileage tiers. Insurance policies and state regulations can vary significantly. It is essential to consult with a qualified insurance professional and review your specific policy documents to understand your coverage, limits, and obligations. State laws regarding classic car registration and use are also subject to change, so always check with your local Department of Motor Vehicles or equivalent agency for the most current requirements.