Classic Car Insurance Requirements in Texas
Navigating the world of classic car insurance can feel like trying to find a needle in a haystack, especially when each state throws its own unique set of rules into the mix. For passionate collectors in the Lone Star State, understanding the specific classic car insurance requirements in Texas is absolutely crucial. You want to protect your prized possession properly without getting caught off guard by state laws or insurer stipulations. This comprehensive guide will walk you through everything a Texas classic car owner needs to know, ensuring your vintage ride is both legally covered and truly protected.
Understanding Texas Classic Car Designations
Before we even get to insurance, it's vital to understand how Texas classifies classic vehicles. The terms "classic," "antique," and "historic" are often used interchangeably in casual conversation, but legally, they have distinct meanings that impact registration and, by extension, insurance. Knowing these differences will help you speak the right language when you're talking to insurers and the Department of Motor Vehicles (DMV).
Defining "Classic" and "Antique" in Texas
In Texas, the primary distinction for specialty vehicle registration often revolves around age. Generally, a vehicle must be at least 25 years old to qualify for "Antique" or "Classic" registration, which then opens the door to specialized insurance policies. The Texas Department of Motor Vehicles (TxDMV) offers specific types of license plates for these vehicles. An "Antique" vehicle, according to the TxDMV, is a passenger car or truck that is at least 25 years old and is a collector's item. These vehicles must be manufactured to the manufacturer's original specifications and not modified in a way that would alter their original design.
It's important to remember that while the state uses "antique," many specialty insurers broadly refer to these as "classic" or "collector" cars. The key is the intent behind the vehicle's use – it’s typically not a daily driver. This distinction is paramount because it sets the foundation for the kind of insurance policy you'll need. If your vehicle meets the age and condition criteria, you'll likely be eligible for a policy that better understands its unique value and limited usage. For a broader overview of how states define these vehicles, you might find our guide on When a Car Qualifies as Classic] helpful.
The Role of Historic License Plates in Texas
Texas offers specific "Antique" and "Classic" license plates, which come with certain benefits and restrictions. For instance, a vehicle registered with "Antique" plates is generally exempt from annual safety inspections and emissions testing. This is a significant perk for many older vehicles that might struggle to pass modern emissions standards or require specific maintenance that doesn't align with standard inspection points. To learn more about specific registration types, check out our article on Historic Vehicle Registration Explained].
However, these plates also come with usage limitations. An antique vehicle in Texas can only be used for exhibitions, club activities, parades, and occasional transportation to and from repair shops or for maintenance. It cannot be used for regular transportation or daily commuting. This usage restriction is a core component of why classic car insurance is generally more affordable than regular auto insurance. Insurers see these vehicles as lower risk because they spend less time on the road and are driven more carefully by owners who cherish them.
Minimum Insurance Requirements for Classic Cars in Texas
Just like any other vehicle on Texas roads, your classic car needs to meet the state's minimum liability insurance requirements. There's no getting around this, even if your classic only sees the light of day a few times a year for a show or a cruise. However, while the minimums are a starting point, they are rarely sufficient for truly protecting a valuable classic.
Texas Minimum Liability Limits
Texas law mandates that all drivers carry minimum liability insurance. The current minimum requirements in Texas, often referred to as 30/60/25 coverage, are:
- $30,000 for bodily injury liability per person
- $60,000 for total bodily injury liability per accident
- $25,000 for property damage liability per accident
This means if you're at fault in an accident, your insurance will pay up to these amounts for the damages you cause to others. While this is the bare minimum to legally drive your classic on Texas public roads, it's generally a woefully inadequate amount of coverage for a vehicle that often holds significant sentimental and financial value. For a deeper dive into statewide regulations, our guide on Classic Car Insurance Requirements Explained] offers a general overview.
Why Specialty Coverage Exceeds Minimums
For classic car owners, relying solely on state minimums is a risky game. The true value of your classic often far exceeds $25,000 in property damage, and medical bills from a serious accident can quickly skyrocket past $60,000. This is where specialty classic car insurance steps in. These policies are designed specifically for collector vehicles and offer much more robust protection, especially when it comes to the actual value of your car.
With a standard auto policy, if your classic is totaled, the payout is typically based on "actual cash value" (ACV), which is market value minus depreciation. For a classic, depreciation can be a cruel mistress, potentially leaving you with far less than what your car is truly worth. Specialty insurers, like Hagerty, understand that classics don't depreciate in the same way, often appreciating instead. They offer "agreed value" coverage, where you and the insurer agree on your car's value upfront. If your car is totaled, you get that agreed-upon amount, no questions asked. This distinction is critical for peace of mind. Without it, you could be left significantly out of pocket if the worst happens.
Unique Requirements for Classic Car Insurance in Texas
Beyond the basic state liability minimums, classic car insurance policies in Texas (and across the country) come with their own set of unique stipulations. These aren't just arbitrary rules; they're in place because they reflect the lower risk profile of collector vehicles. Adhering to these requirements is often what makes specialty classic car insurance so much more affordable and comprehensive than standard auto insurance.
Usage and Mileage Restrictions for Texas Classics
One of the most common tenets of classic car insurance is the understanding that these vehicles aren't daily drivers. Insurers expect your classic to be a leisure vehicle, used for pleasure drives, car shows, club events, or occasional errands, not your primary mode of transportation. This "pleasure-use" requirement is key. If you're planning to commute to work every day in your 1967 Mustang in Houston, a specialty classic policy might not be the right fit, or you might need a specific endorsement for more frequent use.
Most specialty policies will have mileage limits, often ranging from 2,500 to 5,000 miles per year. This restriction helps confirm that the vehicle is indeed used for pleasure and not daily driving, significantly reducing the insurer's exposure to risk. Some premium policies might offer higher mileage tiers or even unlimited mileage for an increased premium, but the core principle remains: these cars are driven less. Understanding these nuances is vital; misrepresenting your usage could lead to a denied claim down the line. Our article on Classic Car Insurance Mileage Limits by State] offers more detailed insights into how these limits vary.
Storage Requirements for Texas Classic Vehicles
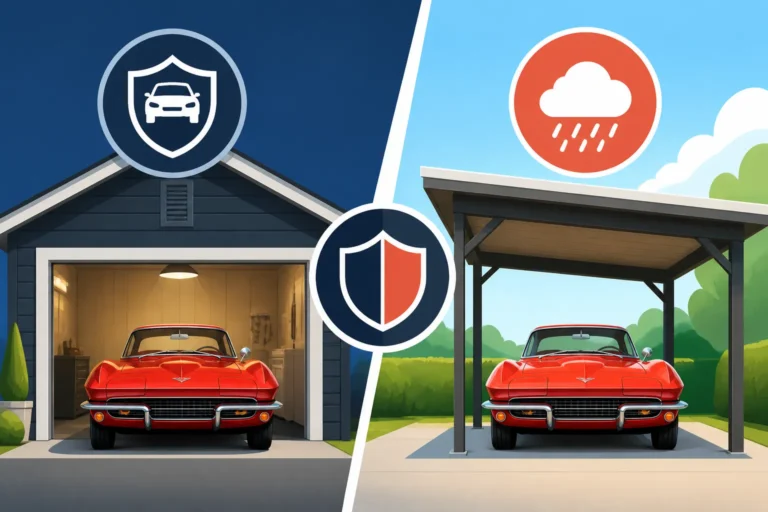
Where you keep your classic car is another critical factor for specialty insurers. They expect your vehicle to be stored securely, typically in an enclosed, locked garage. This isn't just a suggestion; it's often a strict requirement because secure storage minimizes the risk of theft, vandalism, and damage from the elements. A carport, driveway, or street parking typically won't cut it for most classic car insurance providers.
For a collector in Dallas or Austin, ensuring your garage is secure might mean installing an alarm system or reinforcing the garage door. The better protected your classic is when it's not being driven, the lower the risk for the insurer. This, in turn, contributes to the often lower premiums associated with classic car insurance. Don't underestimate the importance of this detail; it's one of the first things an insurer will ask about. You can find more information on this topic in our guide to Garage Storage Requirement for Classic Cars].
Driver Eligibility and Household Requirements in Texas
Classic car insurance policies also have specific requirements regarding who can drive the vehicle and the driving records of all household members. Generally, specialty insurers prefer drivers with clean records – meaning no major accidents, speeding tickets, or DUIs. While minor infractions might be overlooked, a history of reckless driving will likely make it difficult, if not impossible, to obtain a specialty policy.
Additionally, most policies require that all licensed drivers in your household be disclosed, even if they won't be regularly driving the classic. If you have a teenager with a brand-new license in your household, for instance, this could impact your eligibility or premium, as insurers view younger, less experienced drivers as higher risk. Some insurers even have minimum age requirements for the primary insured driver of a classic vehicle. It's always best to be upfront about all household drivers to ensure there are no surprises should you ever need to file a claim. You can explore this further in our article about Minimum Age for Classic Car Insurance Drivers].
Registration and Titling Nuances for Texas Classic Cars
Proper registration and titling are foundational steps for any vehicle owner in Texas, and classic cars have their own set of unique processes. Understanding these can prevent headaches and ensure your classic is road-legal before you even think about hitting the pavement.
Obtaining Historic Plates in Texas
To obtain "Antique" or "Classic" license plates for your vehicle in Texas, you'll need to visit your local county tax assessor-collector's office. You'll typically need to provide proof of ownership (title), a valid Texas inspection (unless exempt), and proof of insurance. The vehicle must meet the age requirement (25 years or older for "Antique" plates) and other criteria, such as being primarily a collector's item and not used for general transportation.
The application process involves a few forms and fees, but once you have your historic plates, you'll benefit from the aforementioned exemptions from annual safety and emissions inspections. Remember, the choice to get historic plates usually comes hand-in-hand with the choice for classic car insurance, as both imply limited, special use for the vehicle. Our detailed post on Antique License Plate Requirements] covers this in depth.
Inspections and Exemptions for Texas Classics
As mentioned, classic cars registered with "Antique" or "Classic" plates in Texas are generally exempt from the annual safety inspection and emissions testing requirements. This is a huge relief for many owners of vintage vehicles, as modifying an older car to meet modern emissions standards can be costly and challenging, if not impossible, while maintaining originality.
However, if your classic car is not registered with "Antique" or "Classic" plates, but instead with standard passenger vehicle plates, it will be subject to the same annual safety inspection and emissions testing requirements as any other vehicle in its county. This is why many classic car owners opt for the specialized registration, not just for the plates themselves, but for the associated exemptions. Make sure you understand the difference before you choose your registration type. You can find out more about exemptions in our article on Classic Car Insurance Inspection Requirements].
Beyond the Basics: Recommended Coverages for Texas Collectors
While meeting Texas's minimum liability requirements is essential, true classic car protection goes much further. Specialty insurance isn't just about meeting legal obligations; it's about safeguarding your investment and passion. There are several additional coverages that virtually every classic car owner in Texas should consider.
The Importance of Agreed Value in Texas
This is arguably the most critical distinction between standard auto insurance and specialty classic car insurance. As mentioned before, standard policies offer Actual Cash Value (ACV), which factors in depreciation. For a classic car, this can be disastrous. Imagine your pristine 1969 Camaro in San Antonio is totaled, and a standard insurer only offers you a fraction of its true market value because they calculated depreciation from its original MSRP.
With an "agreed value" policy, you and your insurer, like Hagerty or Grundy, determine and agree upon the vehicle's fair market value before the policy is issued. This value is often based on an appraisal, current market trends, and the car's condition. If your classic is a total loss, the insurer pays you that exact agreed-upon amount, no deductions for depreciation. This offers immense peace of mind, knowing your investment is fully protected. Our article on Agreed Value Coverage Explained] delves deeper into why this is a game-changer for collectors.
Restoration and Spare Parts Coverage
Many classic cars are ongoing projects, either undergoing a full restoration or being meticulously maintained with original or period-correct spare parts. Standard insurance policies often fall short here. They typically don't account for the incremental increase in value during a restoration project or cover a valuable stash of rare parts.
Specialty classic car insurance, however, often offers endorsements for "restoration coverage" or "vehicle under construction" policies. These policies adjust the agreed value of your car as you invest more into its restoration, ensuring your increasing investment is protected. Similarly, "spare parts coverage" can protect your collection of rare components, engines, or body panels that might be worth a significant amount on their own. For a classic car enthusiast in Houston who's always tinkering, these coverages are invaluable. For more on this, check out our guide on Restoration Coverage for Classic Cars] and Spare Parts Coverage Explained].
Additional Coverages to Consider
Beyond agreed value and restoration coverage, Texas classic car owners should also think about:
- Roadside Assistance: Not just any roadside assistance. You'll want a plan that guarantees flatbed towing, as winching or traditional towing can damage classic vehicles. Many specialty insurers offer this as part of their package.
- Inflation Guard: The value of classic cars can appreciate over time. Inflation Guard automatically increases your car's agreed value by a small percentage each year (e.g., 2-6%) at no additional cost, recognizing its potential appreciation without needing a new appraisal annually.
- Trip Interruption: If your classic breaks down far from home during a tour or road trip, this coverage can help with lodging, meals, and alternative transportation.
These additional layers of protection ensure that your classic isn't just insured, but truly cared for, reflecting the passion and investment you've put into it. When comparing policies, don't just look at the premium; scrutinize the details of what each policy truly offers.
Classic Car Insurance Requirements Summary for Texas
To make things a little easier to digest, here's a quick overview of the key points for classic car insurance in Texas:
| Requirement Category | Texas State Minimums for All Vehicles | Typical Specialty Classic Car Insurance Requirements (e.g., Hagerty) |
|---|---|---|
| Liability Coverage | $30k/$60k/$25k (bodily injury/total bodily injury/property damage) | Often higher than state minimums, recommended for better protection |
| Vehicle Age | N/A (for standard plates) | Generally 25+ years old for "Antique" plates or specialty policies |
| Usage Restrictions | N/A (for standard plates) | Limited pleasure use (e.g., shows, parades, leisure drives) |
| Mileage Limits | N/A (for standard plates) | Typically 2,500 – 5,000 miles/year (tiers available) |
| Storage | N/A (for standard plates) | Secure, enclosed, locked garage required |
| Driver Record | Varies by standard insurer | Clean driving record for all household drivers |
| Primary Driver | N/A | Primary driver must typically have a separate daily driver |
| Valuation Method | Actual Cash Value (ACV) | Agreed Value (guaranteed payout upon total loss) |
| Inspections (with Antique plates) | Exempt from annual safety/emissions | Generally no initial inspection required by insurer, but appraisal may be needed for Agreed Value |
Remember, while the state sets the minimum, specialty insurers have their own criteria that go beyond. This table highlights those important differences.
Disclaimer
The information provided in this article is intended for general informational purposes only and does not constitute legal, financial, or insurance advice. While we strive to provide accurate and up-to-date information, classic car insurance requirements and state laws can change. Always consult with a qualified insurance professional and refer to the official Texas Department of Motor Vehicles (TxDMV) resources for the most current and specific requirements applicable to your situation. Policy terms and conditions vary by insurer.