Classic Car Insurance Cost by State
It's a common misconception that classic car insurance costs are static, a one-size-fits-all number you can easily budget for. The reality is, just like with regular car insurance, the state where your cherished classic resides can dramatically influence your premiums. You might find yourself scratching your head, wondering why your buddy in Ohio pays significantly less for his '69 Camaro than you do for your identical model in Florida. This guide is here to unravel those state-specific mysteries and help you understand the core factors at play.
Understanding Why Classic Car Insurance Costs Vary by State
When you’re looking to protect your prized possession, it’s not just about the car itself or how often you drive it. The geographical location where your classic lives and breathes plays a surprisingly significant role in how much you’ll pay for insurance. It's a complex tapestry woven from laws, environmental factors, and local market conditions.
State-Specific Laws and Regulations
Every state in the U.S. has its own set of rules and regulations governing vehicle insurance, and classic cars are no exception. These aren't just minor differences; they can fundamentally alter the risk profile from an insurer's perspective. For instance, some states have higher mandatory minimum liability coverage requirements. This means the baseline cost for liability coverage, which every driver needs, is inherently higher. Imagine the difference between states like Florida, known for its higher minimum liability requirements, versus a state with more relaxed mandates. These state minimum requirements for classic cars can affect your overall premium significantly.
Beyond liability, states also have differing rules on registration for classic, antique, and historic vehicles. Some states offer special classic car license plates that come with specific usage restrictions, which in turn can influence insurance rates. For example, some states might require your classic to be over a certain age to qualify for these special plates, and insurers often factor these official designations into their underwriting. Understanding the nuances of Classic Car Registration and Insurance by State is crucial. If your state mandates annual safety inspections or emissions tests for certain vehicle ages – even for classics – that regulatory environment can subtly push up administrative costs for insurers, which might reflect in premiums.
Regional Risk Factors and Environmental Concerns
The physical location of your classic also exposes it to different sets of risks, and insurers are meticulous about assessing these. Think about states prone to natural disasters. If you live in a coastal area of Florida, Louisiana, or North Carolina, your classic is at a higher risk of hurricane damage, storm surge, or flooding. Similarly, collectors in California face increased risks from wildfires and earthquakes. These geographical vulnerabilities mean insurers factor in a higher probability of comprehensive claims due to acts of nature.
Beyond natural phenomena, localized theft rates are a huge consideration. Urban centers in states like California, Texas, or New York often have higher rates of vehicle theft compared to more rural areas. A classic car, being a desirable and often easy-to-resell target, can be particularly attractive to thieves. If your car is stored in a high-theft zip code, even if it's garaged, that regional risk can translate to higher comprehensive coverage costs. Similarly, population density and traffic congestion can increase the likelihood of accidents. More cars on the road in states like New Jersey or Massachusetts can mean a higher chance of a collision, impacting the cost of your collision coverage.
Local Market Dynamics and Competition
The insurance market isn't a monolith; it's a dynamic ecosystem that varies from state to state. The number of classic car owners in a particular state can affect the demand for specialized insurance, which in turn influences pricing. States with a vibrant classic car culture, large car clubs, and frequent shows might see more competition among specialty insurers. This competition can sometimes lead to more favorable rates or a wider range of policy options. For instance, if you're in a state like Pennsylvania or Michigan with a strong tradition of classic car ownership, you might find more options for Best Specialty Classic Car Insurers who are familiar with the local scene.
Conversely, in states with fewer classic car enthusiasts or a less developed specialty insurance market, there might be fewer insurers vying for your business, potentially leading to higher premiums. The presence of major specialty carriers like Hagerty or Grundy in a given state can also impact competition. If one or two insurers dominate the market, they might have less incentive to offer highly competitive pricing. Local economic factors, such as the cost of living and average repair costs for specialized classic car mechanics, also play a role. If it costs more to fix a vintage engine in New York City than it does in rural Tennessee, those higher potential claim payouts will be reflected in the state's average insurance rates.
Key Factors Influencing Classic Car Insurance Premiums Beyond State Lines
While state-specific variables set a crucial baseline for your insurance costs, there are also universal factors related to your vehicle, your driving habits, and how you store your classic that significantly impact your premium, no matter where you live. These are the elements you often have more control over.
Vehicle Value and Type
The inherent value of your classic car is, naturally, one of the biggest drivers of its insurance cost. This isn't just about what you paid for it; it’s about its "agreed value" with your insurer. Unlike regular car insurance, which often uses actual cash value (ACV) and depreciates your vehicle, classic car policies typically offer Agreed Value Coverage Explained. This means you and the insurer agree on a specific value for your car at the outset, and in the event of a total loss, that's the amount you'll be paid. The higher this agreed value, the higher your premium will generally be, as the insurer's potential payout is greater.
The type of classic also matters immensely. Insuring a rare 1963 Split-Window Corvette will undoubtedly cost more than a more common 1970 Volkswagen Beetle, simply due to the disparity in their market values and the difficulty/cost of sourcing replacement parts. Muscle cars, exotic classics, and highly modified vehicles often come with higher premiums due to their performance capabilities, increased theft appeal, or the specialized (and expensive) nature of their components. Even subtle modifications can alter a car's risk profile. The more unique, powerful, or valuable your classic, the more the insurer is taking on, and that’s reflected in the price.
Driving Habits and Usage Restrictions
Classic car insurance isn't designed for daily commuting, and your driving habits directly influence your rates. Most specialty policies come with strict usage limitations, such as "pleasure use" or "limited use" clauses. These policies assume you're driving your classic for enjoyment – car shows, club events, Sunday cruises – not to and from work. If you plan to use your classic as a Classic Car Insurance for a Daily Driver, you'll likely face significantly higher premiums or might not even qualify for a specialty policy, as the risk of wear and tear, accidents, and exposure to everyday hazards increases dramatically.
Mileage limits are another critical factor. Many classic car insurance policies offer different mileage tiers (e.g., 1,000, 2,500, or 5,000 miles per year). The more miles you plan to put on your classic, the higher your premium will be, as increased driving equates to increased risk of an incident. Some insurers offer unlimited mileage classic car insurance, but this typically comes at a premium price. Your personal driving record, including any accidents or violations, also impacts your premium, just as it would with a regular car. A clean driving history is usually rewarded with lower rates across the board.
Storage Conditions and Security Measures
Where and how you store your classic car is a significant factor in determining your insurance premium. Insurers want to know that your valuable asset is protected from theft, vandalism, and environmental damage. The gold standard is typically a private, secured, enclosed garage. If your car is kept in a locked garage, whether at your home or a dedicated storage facility, insurers view this as a lower risk, and your rates will often reflect that. Policies almost always have a Garage Storage Requirement for Classic Cars.
Conversely, storing your classic in a carport, under a canvas cover, or worse, out in the open, significantly increases its exposure to risks like theft, hail damage, falling debris, or vandalism. This higher risk translates directly into higher comprehensive coverage costs. Many specialty insurers won't even cover a classic that isn't stored in an enclosed, locked facility. Beyond the basic storage type, additional security measures can also help lower your rates. Installing an alarm system, a vehicle tracking device (like LoJack), or maintaining a secure, gated property can all demonstrate to an insurer that you're taking proactive steps to protect your investment, potentially qualifying you for Classic Car Insurance Discounts Explained.
Decoding State-Specific Cost Differences: A Deep Dive
Let's get down to brass tacks and look at how costs can really differ from one part of the country to another. While average national costs for classic car insurance might be around $300-$1000 annually, these averages hide massive state-by-state disparities.
High-Cost States for Classic Car Insurance
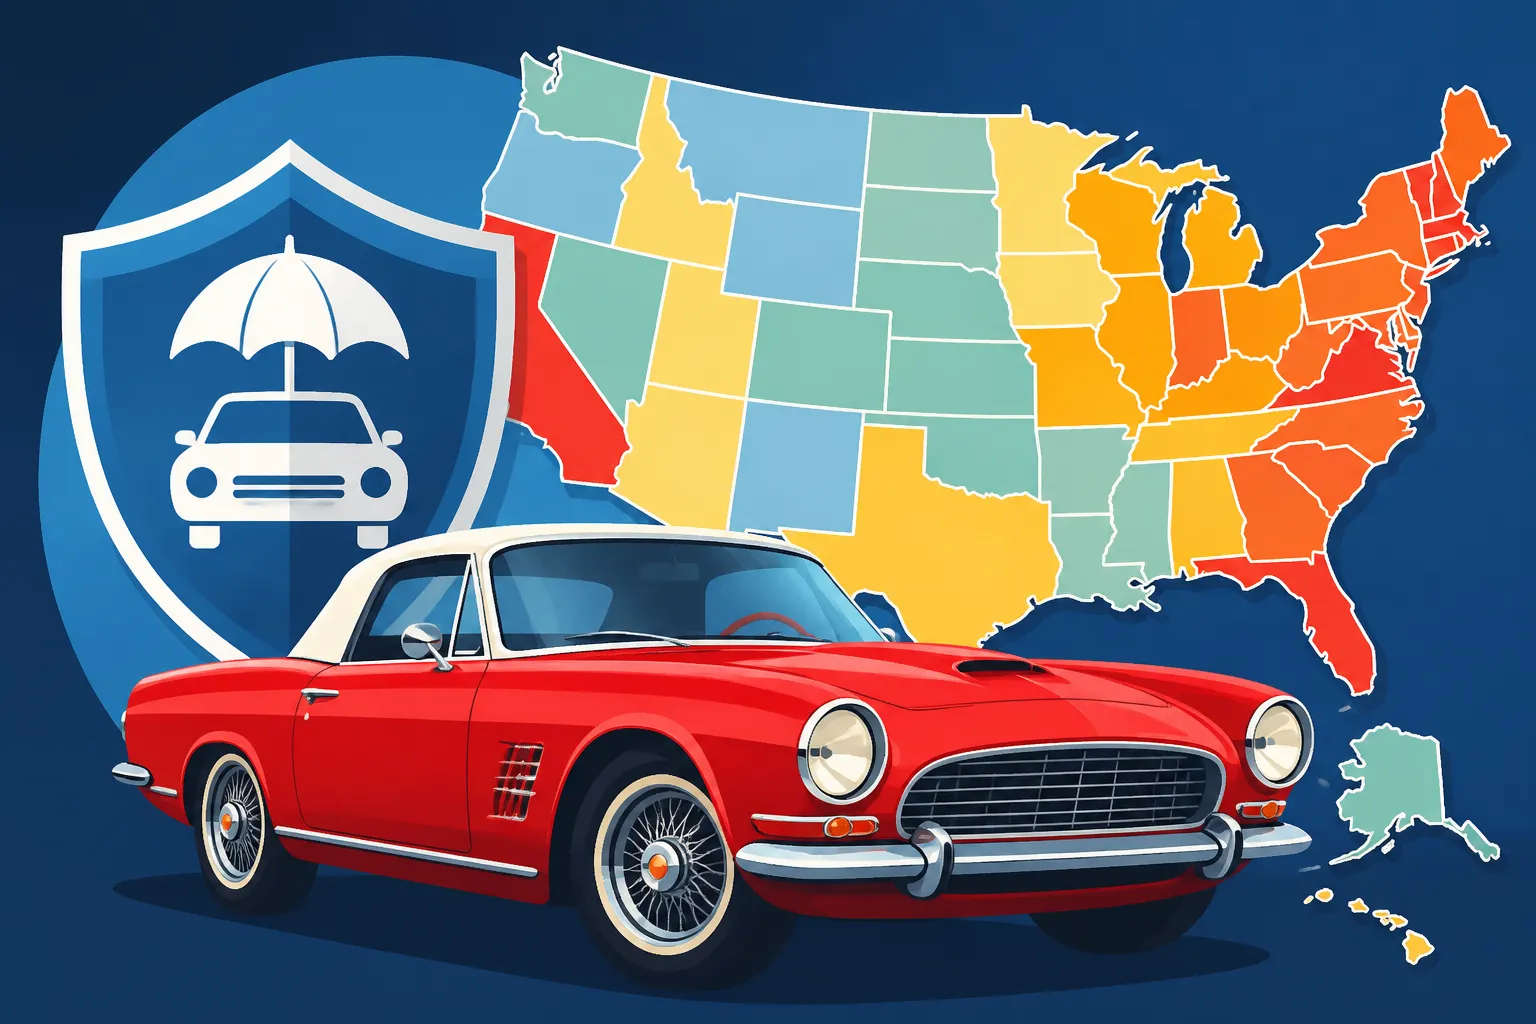
Certain states consistently rank higher for classic car insurance premiums due to a confluence of factors. Take Florida, for example. Its geographic location makes it highly susceptible to hurricanes and tropical storms, leading to elevated comprehensive coverage costs. The dense population in areas like Miami and Orlando also contributes to higher accident rates and theft risks. Additionally, Florida has relatively high minimum liability requirements, pushing up the baseline cost. A classic car owner in Florida might easily pay 20-30% more than someone in a less risky state for comparable coverage.
California is another state where classic car insurance can be on the higher side. While the weather is often sunny, the state faces significant wildfire risks in many regions, and earthquake potential. Its large, densely populated urban centers like Los Angeles and San Francisco have higher theft rates for desirable vehicles, including classics. The sheer cost of living and doing business in California also means repair costs for specialized classic mechanics are often higher, which insurers factor into their rates. Even with exemptions for classic cars, the general regulatory environment and litigation climate can contribute to higher premiums.
Michigan often sees higher auto insurance rates across the board, and classic car insurance can follow suit. This is partly due to its unique no-fault insurance system, which can sometimes lead to higher personal injury protection (PIP) costs, even if classic cars have some exemptions. Urban areas like Detroit also contribute to higher theft and vandalism rates. Similarly, states like New York and Louisiana face high population densities, increased theft risks in major cities, and susceptibility to natural disasters (hurricanes for Louisiana, and nor'easters for New York), all of which contribute to elevated classic car insurance costs.
Lower-Cost States for Classic Car Insurance
On the flip side, many states offer more budget-friendly classic car insurance. Ohio, for instance, often boasts some of the most affordable rates. The state has a diverse geography, but generally lower risks for major natural disasters compared to coastal or earthquake-prone states. Population density is moderate, and while it has urban centers, overall theft rates for classics might be lower than in a place like California. The strong car culture in Ohio, combined with reasonable repair costs, can create a competitive market for insurers.
Similarly, states in the Midwest and Mountain West, like Wisconsin, Idaho, Montana, or North Dakota, frequently offer lower premiums. These states typically have lower population densities, which means fewer cars on the road, less traffic congestion, and a reduced likelihood of minor accidents. They also generally experience fewer extreme weather events that lead to widespread vehicle damage. For example, while Wisconsin has winter, classics are typically stored away for the season, minimizing exposure to snow and ice-related incidents. The cost of living and labor for repairs can also be lower, further reducing potential claim payouts for insurers.
Regulatory Environment and Its Impact
The regulatory oversight of insurance at the state level is a silent but powerful force shaping your premiums. Each state has an insurance department that reviews and approves insurance rates. Some states have stricter regulations on how insurers can price policies, while others allow more flexibility. This can lead to vastly different rate structures for the same coverage from the same insurer, just across a state line.
For example, states with highly consumer-protection-oriented insurance departments might scrutinize rate increases more closely, potentially keeping premiums lower. Conversely, states with a history of high insurance fraud or substantial legal claims (e.g., higher jury awards in liability cases) might see insurers pricing in those increased risks. Auto insurance laws, such as no-fault vs. at-fault systems, also affect classic car liability requirements by state. In a no-fault state, your own insurance typically pays for your medical expenses regardless of who caused an accident, which can sometimes drive up PIP costs, even if classics are driven sparingly. Understanding these underlying frameworks helps explain why How Much Does Classic Car Insurance Cost can fluctuate so much based on your address.
Real-World Examples of State-Specific Cost Scenarios
Let's illustrate these differences with some hypothetical scenarios, bringing to life how state variations impact classic car owners. It's often easier to grasp these concepts when you think about real people dealing with real cars in real places.
The California Collector's Dilemma
Imagine Sarah, living in Pasadena, California, with her beautifully restored 1965 Ford Mustang. She cherishes her Pony car and takes it to local shows and drives along the coast a few times a month, meticulously keeping it under the 2,500-mile annual limit. Sarah has her Mustang valued at an agreed value of $45,000. Her comprehensive and collision coverage is crucial due to the car's value and the potential for wildfire smoke damage, or even theft in the greater Los Angeles area.
Because she lives in a densely populated region, her liability costs are higher than average. Additionally, while classic cars get some exemptions, the overall higher cost of living and specialized repair work in California means that labor rates for fixing her vintage Mustang are quite steep. If she needed a custom body shop after a fender bender, the bill would be significantly higher than in, say, Arizona. Sarah might find her annual premium for full coverage on her Mustang to be in the range of $800-$1,200, even with a clean driving record and garage storage. This premium reflects not just the car's value, but the elevated regional risks and the high cost of doing business in her state.
Navigating New York's Urban Landscape
Now consider Michael, who owns a charming 1970 Triumph TR6 in a secured parking garage in Brooklyn, New York. His TR6 has an agreed value of $35,000. Michael loves to take it out for drives up to the Catskills or to Long Island car meets, staying within his 1,500-mile annual limit. However, insuring a classic in New York City presents its own set of challenges. The sheer density of traffic, combined with higher rates of vehicle crime and vandalism in some city boroughs, means Michael's comprehensive coverage comes at a premium.
While he has excellent secured storage, the underlying risk profile of his zip code is higher. The cost of liability insurance in New York is generally high due to the state's stringent regulations and potential for larger personal injury claims. Michael's premium might be similar to or even slightly higher than Sarah's, perhaps in the $750-$1,100 range, despite his car having a lower agreed value. His policy also has very specific Garage Storage Requirement for Classic Cars, which is non-negotiable for him to qualify for specialty rates. The urban environment and the general cost of living here heavily skew the insurance equations.
The Midwestern Enthusiast's Advantage
Finally, let's look at David, who lives in a quiet suburb of Indianapolis, Indiana. David is the proud owner of a well-maintained 1969 Chevrolet Chevelle SS, with an agreed value of $55,000. He takes it to local cruise-ins and enjoys weekend drives, rarely exceeding 2,000 miles a year. David stores his Chevelle in a locked two-car garage at his home.
In Indiana, population density is lower, and the state experiences fewer severe natural disaster risks compared to coastal states. Theft rates for classics, while present, are generally not as high as in major metropolitan areas on the coasts. Repair costs for classic cars in the Midwest are also typically more reasonable. These factors combine to create a more favorable insurance environment. Despite his car having a higher agreed value than Sarah's or Michael's, David might find his annual premium to be surprisingly lower, perhaps in the $500-$900 range. This significant difference highlights how much state-specific risk profiles and economic conditions can influence the final cost.
Strategies to Manage Classic Car Insurance Costs in Any State
Even with state-specific variations, there are concrete steps you can take to ensure you're getting the best possible rate for your classic car insurance. It's about being proactive and understanding how to tailor your policy effectively.
Optimizing Your Coverage and Agreed Value
The most fundamental way to manage your classic car insurance cost is by carefully determining your vehicle's agreed value. Don't just pick a number out of thin air. Get a professional appraisal to accurately reflect your car's condition, modifications, and market value. If your car is worth $50,000 but you only insure it for $30,000, you're underinsured and risk a significant loss if disaster strikes. Conversely, insuring a $50,000 car for $70,000 means you're overpaying. Regular re-appraisals are also wise, especially if you've completed significant restoration work that increases its value. For example, a fully restored model might fall under Restoration Coverage for Classic Cars for the duration of the work, but once complete, its new agreed value needs to be updated.
Another strategy is to choose the right deductible. A higher deductible means you pay more out-of-pocket if you file a claim, but it almost always results in a lower annual premium. Given that classics are driven less frequently and often stored securely, many owners opt for a slightly higher deductible to save on yearly costs. However, ensure it's an amount you're comfortable paying. Also, consider only the optional coverages you truly need. Do you really need Spare Parts Coverage Explained if you don't have a stash of valuable extra components? Being judicious about add-ons can trim unnecessary costs.
Leveraging Discounts and Bundling Options
Classic car insurers, much like standard carriers, offer a variety of discounts that can significantly reduce your premiums. Always ask your potential insurer about what discounts they provide. One common discount is for car club memberships. If you're a member of a recognized classic car club, like the Vintage Chevrolet Club of America or the Mustang Club of America, many specialty insurers like Hagerty will offer a discount. This is because car club members are generally seen as more responsible, knowledgeable, and careful owners.
Another excellent way to save is through multi-car discounts. If you have a collection of classic cars, insuring them all under a single multi-car collector policy can often be more cost-effective than separate policies for each. You might also find savings by bundling your classic car policy with your homeowners or everyday auto insurance, though this is less common with highly specialized classic car insurers. Maintaining a clean driving record is paramount; tickets and accidents, even in your daily driver, can impact your classic car insurance rates. The more you demonstrate responsible ownership and driving, the more likely you are to qualify for favorable rates.
Choosing the Right Specialty Insurer
This might be the most crucial strategy of all. Standard auto insurance companies often don't truly understand the unique needs and value of classic cars. They might try to insure your classic on a standard policy, which typically uses actual cash value and depreciates your car, leaving you significantly underinsured if it's totaled. Instead, always seek out specialty classic car insurance providers. Companies like Hagerty, Grundy, American Collectors Insurance, and American Modern Insurance Group are dedicated to the classic car market.
These specialty insurers offer policies specifically designed for classics, including agreed value coverage, lower annual mileage limits, and an understanding of how collectors use and store their vehicles. Because they specialize, they often offer more competitive rates for classic cars than standard insurers, as they are pooling lower-risk drivers. They understand that a 1967 Mustang is likely driven cautiously and stored safely, not used for aggressive daily commutes. When you look to How to Get a Classic Car Insurance Quote, make sure you're getting quotes from these specialty providers who genuinely get the classic car world. They know the market, they know the risks unique to these vehicles, and they structure their policies and pricing accordingly, often leading to better coverage at a more appropriate cost.
Important Considerations When Getting Quotes by State
Navigating the world of classic car insurance quotes, especially when factoring in state differences, can feel a bit like a treasure hunt. To ensure you find the best coverage at the right price, it's essential to be prepared and know what to look for.
Providing Accurate Vehicle Information
When you're gathering quotes, be meticulously detailed about your classic. This isn't just about the make, model, and year; it's about the full story of your vehicle. Have documentation ready that details any professional restoration work, significant modifications, and its current condition. If you have a professional appraisal, submit it. This is particularly vital for establishing an accurate agreed value, which, as we've discussed, is the cornerstone of classic car insurance. Photos of your vehicle, especially interior, exterior, and engine bay, can also be very helpful in verifying its condition.
In some states, insurers might require a pre-inspection of your vehicle, especially for higher-value classics or if you're a new policyholder. This is to ensure the condition matches the declared value. Don't shy away from this; it protects both you and the insurer by establishing a clear baseline. The more comprehensive and verifiable information you provide upfront, the smoother the quoting process will be, and the more likely you are to receive an accurate and competitive offer.
Understanding Policy Specifics
Don't just look at the bottom line premium. Dive deep into the policy specifics, paying close attention to factors like mileage limits. If you live in a state like Texas, which has vast stretches of open road perfect for cruising, you might be tempted to put more miles on your classic. Ensure the mileage tier you select genuinely reflects your anticipated usage. Opting for a 1,000-mile limit when you consistently drive 2,000 miles could lead to issues if you ever have a claim. Many states have slightly different interpretations or enforcement of these mileage rules, so clarity is key.
Also, reconfirm the storage requirements. While most specialty insurers require an enclosed, locked garage, some states or urban areas might have higher theft rates, pushing insurers to be even more stringent. If you're moving your classic from a rural garage in Wisconsin to a city garage in Illinois, double-check that your new storage setup still meets the insurer's criteria for that specific locale. Ensure you understand all the exclusions, too. Some policies might exclude coverage for track events or certain types of rallies unless specific endorsements are added. The more you know about the fine print, the fewer surprises you'll face down the road.
The Role of Agents and Online Tools
When seeking quotes, you have a couple of primary avenues: independent insurance agents and online quoting tools. Independent agents who specialize in classic cars can be invaluable. They often work with multiple specialty carriers, including Hagerty vs Grundy: Which Is Better and many others, and can shop around on your behalf. They understand the nuances of state-specific regulations and can help you navigate complex coverage options, ensuring you get a policy that's tailored to your classic and your location. A good agent can often find you discounts you might not even know about.
Online quoting tools, offered by many specialty insurers like Hagerty directly, also provide a convenient way to get an initial estimate. These tools are fantastic for quickly comparing rates between different providers without the back-and-forth of phone calls. However, for truly complex situations or very high-value vehicles, a direct conversation with an agent or an underwriter is often beneficial to ensure every detail is accounted for. Regardless of your chosen method, remember that the goal is to get a clear, comprehensive quote that truly covers your classic car's unique value and usage, keeping in mind the specific risk profile of your state.
| State | Typical Liability Costs (Estimate) | Natural Disaster Risk | Theft Risk (Classics) | Average Garage Storage Cost (Urban) | Common Mileage Tiers | Key Cost Influencers |
|---|---|---|---|---|---|---|
| California | Higher | High (Wildfires, EQ) | Higher | Higher | 1k, 2.5k, 5k | High living cost, population density, natural disasters |
| Florida | Higher | Very High (Hurricanes) | Higher | Moderate to Higher | 1k, 2.5k, 5k | High natural disaster exposure, high liability minimums |
| Ohio | Moderate | Low to Moderate | Moderate | Moderate | 1k, 2.5k, 5k | Stable regulatory environment, moderate risk factors |
| New York | Higher | Moderate (Nor'easters) | Higher | Very High | 1k, 2.5k, 5k | High population density, urban crime, high living cost |
| Indiana | Lower to Moderate | Low | Lower | Lower to Moderate | 1k, 2.5k, 5k | Low population density, low natural disaster risk, favorable regulations |
Disclaimer
Please remember that this article provides general information and guidance regarding classic car insurance costs by state. Insurance rates are highly individualized and depend on many factors unique to your vehicle, driving history, and specific location. Always obtain multiple personalized quotes from reputable specialty classic car insurance providers and consult with an insurance professional to determine the best coverage and pricing for your needs. State laws and insurance regulations are subject to change.