Classic Car Insurance Coverage Types Explained
Trying to navigate the world of classic car insurance can feel like deciphering an ancient scroll, especially when you're just starting out or have always lumped your prized ride in with your daily driver's policy. The truth is, standard auto insurance often falls woefully short when it comes to truly protecting the unique value and specific needs of a collectible vehicle. This comprehensive guide will meticulously break down the various types of classic car insurance coverage available, helping you understand what each one offers and why it's crucial for safeguarding your automotive passion.
Understanding the Core Difference: Classic vs. Regular Insurance
It’s a common misconception that all car insurance is created equal. While both classic and regular policies aim to protect your vehicle and your finances, the fundamental approach to valuation and usage differs dramatically. For your everyday sedan, an insurer looks at depreciation. For your cherished classic, the focus shifts to appreciation and unique care.
What Makes Classic Car Insurance Unique
The very essence of classic car insurance is recognizing that these aren't just vehicles; they're investments, pieces of history, and often, extensions of our own personalities. Unlike a new car, which starts losing value the moment it leaves the lot, a classic car can appreciate over time, especially with proper care and restoration. This shift in perspective means a different kind of coverage is needed. You wouldn't insure a priceless antique vase with the same policy you use for a kitchen utensil, right? The same logic applies here. Classic car insurers understand the passion, the painstaking restorations, and the limited use these vehicles typically see, and they tailor policies accordingly. This specialized understanding is why Classic Car Insurance vs Regular Insurance: What's Required is such a critical distinction for collectors.
The Valuation Conundrum: Why Agreed Value is King
This is arguably the most crucial difference and the bedrock of classic car insurance. When you insure a modern vehicle, the payout after a total loss is typically based on Actual Cash Value (ACV) or Stated Value, which often means depreciation is factored in, leaving you with less than the car is truly worth. For a classic, this approach is disastrous. Imagine your perfectly restored 1969 Camaro being totaled, and the insurer offers you a depreciated amount based on what a standard 1969 Camaro might fetch if it wasn't concourse quality. That's where Agreed Value comes in. It's a pre-determined amount that you and the insurer agree upon as the car's fair market value before anything happens. This figure is locked in for the policy term, providing immense peace of mind. It means if disaster strikes, you get that agreed-upon amount, no haggling, no surprises.
The Cornerstone of Classic Car Protection: Agreed Value Coverage
Let's really dive into the concept of Agreed Value, because it truly is the most important component of a classic car insurance policy. Without it, you're essentially gambling with your investment.
How Agreed Value is Established
So, how do you even arrive at this magical "Agreed Value"? It's a collaborative process between you and your insurer, often involving a bit of documentation. Typically, you'll provide photos of your vehicle, details of any restorations, receipts for major parts or work, and possibly even a professional appraisal. Insurers like Hagerty have extensive databases and valuation tools based on real-world sales data, auction results, and market trends to help determine a fair and accurate value. If your vehicle is particularly rare or has unique provenance, an independent appraisal will carry a lot of weight. It's about presenting a clear, compelling case for what your specific car is truly worth in today's market. Getting an accurate valuation is critical, which is why you might want to learn How to Value Your Classic Car for Insurance.
What Happens in a Total Loss Scenario
This is where Agreed Value truly shines. Let's say your meticulously restored 1965 Mustang, valued at $75,000 under an Agreed Value policy, is involved in an accident and deemed a total loss. With an Agreed Value policy, the insurance company pays you the full $75,000, minus any deductible. There's no negotiation, no arguments about depreciation, and no frustrating scramble to prove your car's true worth after the fact. This certainty is a huge relief for collectors. Compare that to a standard policy where you might only receive an "Actual Cash Value" that severely undervalues your unique asset. The peace of mind alone is worth the investment in a specialized policy.
Why Stated Value and Actual Cash Value Fall Short for Classics
It’s imperative to understand why these other valuation methods are simply inadequate for classic cars. Stated Value, at first glance, might seem similar to Agreed Value. You state a value, and the insurer notes it. However, in the event of a total loss, the insurer typically reserves the right to pay out either the "stated value" or the actual cash value, whichever is less. This means you could state $75,000, but if the insurer later decides the ACV is only $40,000, that's all you're getting. It's a dangerous trap that leaves you vulnerable. Actual Cash Value (ACV) is even worse for classics, as it explicitly deducts for depreciation based on age, mileage, and condition – precisely what you don't want for an appreciating asset. For a collector, these options simply don't offer the financial security needed to replace a unique vehicle. This is why Agreed Value Coverage Explained is so vital for collectors.
Essential Foundational Coverages for Classic Cars
Beyond the critical Agreed Value component, classic car insurance policies offer many of the same foundational coverages you'd find on a standard policy, but they are tailored to the unique usage patterns and risks associated with collectibles.
Classic Car Liability Coverage
Just like with any other vehicle on the road, liability coverage is a non-negotiable requirement in nearly every state. This coverage protects you financially if you're at fault in an accident that causes bodily injury or property damage to others. While your classic car may not see daily driving, you'll still take it to shows, for weekend cruises, or on a special tour. During any of these outings, an accident can happen. Your classic car insurance policy will include liability coverage that meets your state's minimum requirements, and you can, and often should, opt for higher limits to protect your personal assets. If you're curious about specific state regulations, you can research topics like Classic Car Insurance Requirements in California or Classic Car Insurance Requirements in Texas.
Imagine you're cruising your beautiful '67 Corvette down a scenic highway in New Jersey. Suddenly, another driver swerves, and you, unfortunately, collide. If you're found at fault, your classic car liability coverage would step in to cover the other driver's medical bills and damage to their vehicle, up to your policy limits. Without adequate liability, even a minor fender bender could lead to significant out-of-pocket expenses and potential lawsuits, jeopardizing not just your finances, but your entire collection. It’s an essential layer of protection for every outing.
Comprehensive Coverage for Your Prized Possession
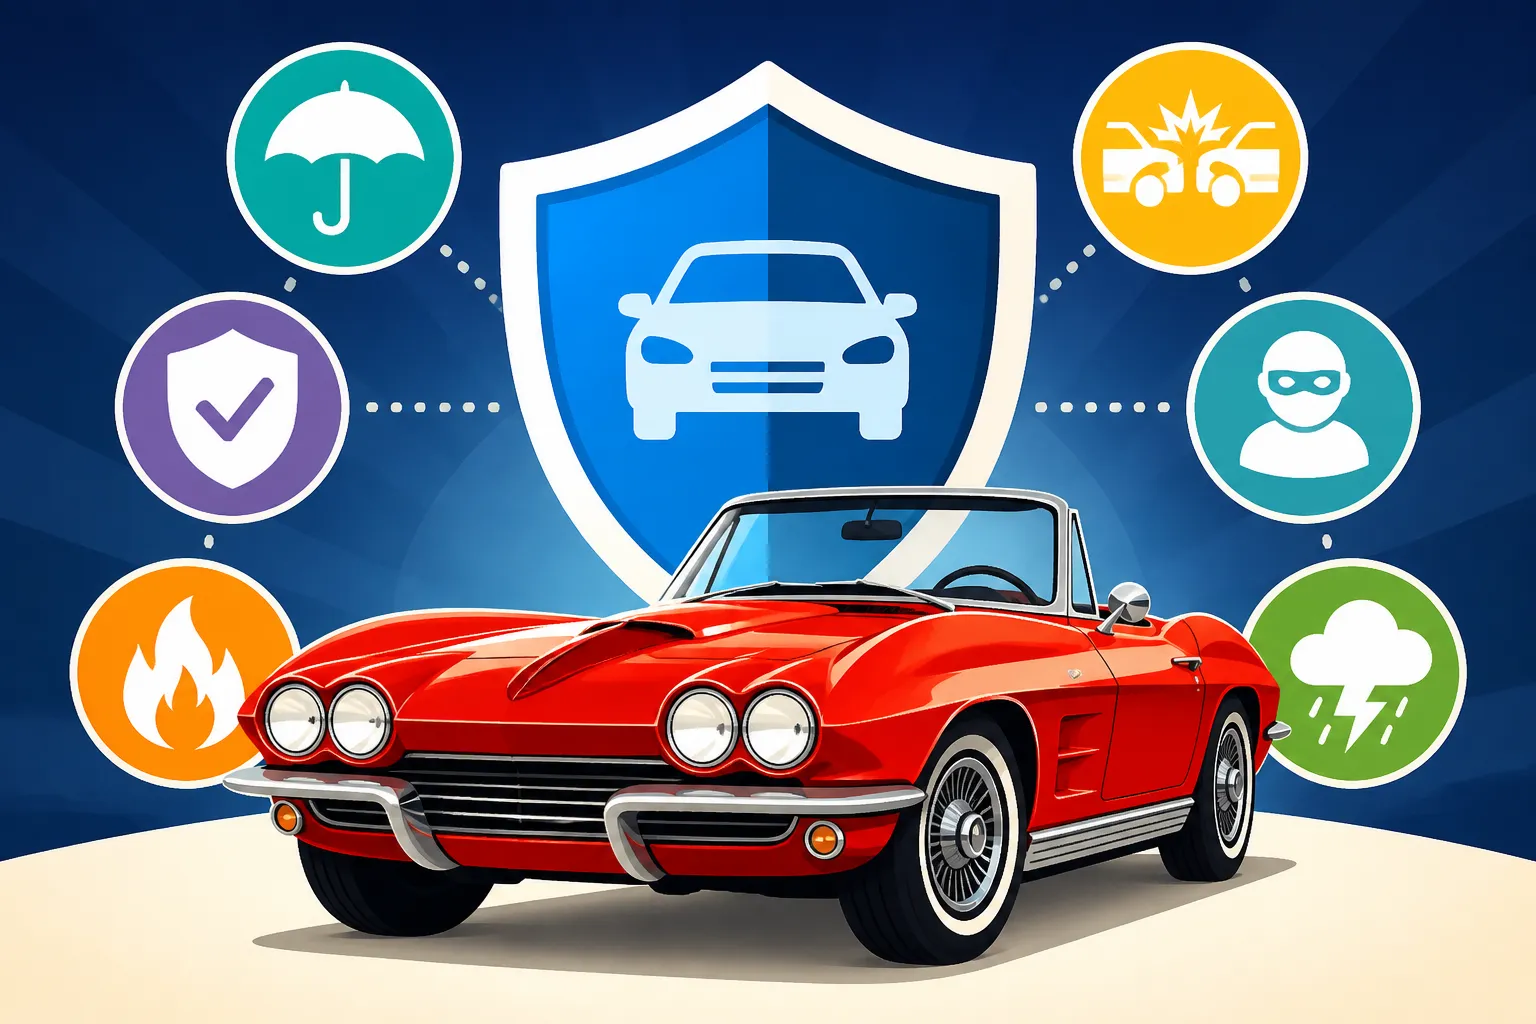
Comprehensive coverage is designed to protect your classic from non-collision-related damage. Think about it: classic cars are often targets for theft, they can suffer damage from hail or falling branches during a storm, or even incur damage from vandalism. These are risks that have nothing to do with driving but are very real for a parked or stored classic. This coverage typically covers:
- Theft: Sadly, classic car theft is a persistent concern.
- Fire: A garage fire or an engine compartment fire can be devastating.
- Vandalism: Malicious damage from others.
- Natural Disasters: Hail, floods, strong winds, and other acts of nature.
- Falling Objects: Trees, rocks, or even debris from construction.
This coverage is especially important because classic cars often spend significant time parked, either in a garage, at a show, or at a restoration shop. Even in a secure location, these non-collision risks exist. A comprehensive policy helps ensure that your investment is protected even when it's not on the road.
Consider a collector in Florida who stores their meticulously restored '55 Thunderbird. A hurricane sweeps through, and despite their best efforts, a tree branch falls, cracking the windshield and denting the roof. Without comprehensive coverage, the cost of repairs would be entirely out of pocket. With it, the policy covers the damage, ensuring the car can be restored to its pre-loss condition, a crucial aspect of protecting its Classic Car Insurance Cost: Complete Breakdown. This type of coverage is non-negotiable for preserving your classic's value against unforeseen events.
Collision Coverage: Protecting Against the Unexpected
While classic cars are driven less frequently than daily drivers, accidents can still happen. Collision coverage protects your own vehicle from damage resulting from a collision with another vehicle or object, regardless of who is at fault. This includes hitting a tree, backing into a pole, or being involved in a multi-car pile-up.
For a classic car, repairs can be incredibly expensive due to the need for specialized parts, skilled labor, and often, custom fabrication. Finding original parts for a vintage Shelby GT350 or a rare European exotic isn't as simple as ordering off Amazon. Collision coverage, especially when paired with Agreed Value, ensures that if your classic sustains damage in a fender bender or more serious incident, the costs of getting it properly repaired and restored to its previous glory are covered. This allows you to focus on the restoration process rather than the financial strain.
Imagine taking your beloved 1970 Chevelle SS to a local car show in Ohio. On the way, a distracted driver clips your front bumper, causing significant damage to the grille and headlight assembly. If you have collision coverage, your classic car policy would cover the cost of repairing your Chevelle, ensuring that the necessary parts are sourced and the work is done by qualified specialists, maintaining the car's integrity and value. This avoids the devastating financial hit of paying for potentially complex repairs yourself.
Specialized Add-Ons and Endorsements Every Collector Should Consider
One of the great advantages of specialty classic car insurance is the availability of specific add-ons designed to meet the unique needs of collectors. These aren't typically found on standard auto policies and can be invaluable.
Restoration Coverage: Protecting Your Investment During the Build
Many classics aren't bought in pristine condition; they're passion projects, slowly brought back to life over months or even years. This is where restoration coverage becomes incredibly important. A standard policy won't adequately cover a car that's disassembled in a garage, waiting for parts, or actively undergoing bodywork. Restoration coverage accounts for the increasing value of your project as you invest time, money, and rare parts into it.
This coverage can be structured to automatically increase the Agreed Value of your vehicle incrementally as you complete various stages of restoration or as you spend money on parts and labor. This way, if something happens – a fire in the garage, tools falling on a fender, or theft of components – you're protected for the value you've already invested, not just its "barn find" worth. For anyone with a project car, Restoration Coverage for Classic Cars is a no-brainer.
Consider Mark, a dedicated enthusiast in Pennsylvania, meticulously restoring a 1932 Ford in his home garage. He's already invested countless hours and a significant sum in engine work, new body panels, and a custom interior. Halfway through, a mishap with a welding torch causes a small fire, damaging parts of the chassis and freshly painted fenders. If Mark only had basic "storage-only" coverage, he might be out of luck for the value he added. But with specialized restoration coverage, his insurer, like American Modern, would recognize the incremental value he'd built into the car and cover the costs to bring it back, protecting his ongoing investment.
Spare Parts Coverage: Safeguarding Your Inventory
Any serious classic car collector knows the struggle and expense of sourcing original, rare, or N.O.S. (New Old Stock) parts. Whether it’s a spare engine block for a muscle car, a set of chrome bumpers for a vintage cruiser, or a specific trim piece that’s impossible to find, these parts can represent a significant financial investment, often stored separately from the car itself.
Traditional auto insurance policies almost never cover spare parts. Specialty classic policies, however, offer dedicated spare parts coverage. This add-on protects your collection of components against theft, fire, or damage, typically up to a certain limit. This is crucial for anyone who has invested heavily in future-proofing their classic or is accumulating parts for multiple vehicles. You might think your spare intake manifold is safe on a shelf, but imagine if your garage catches fire. Spare Parts Coverage Explained ensures those hard-won components are financially protected.
For instance, Sarah in Michigan collects vintage Corvettes and has a separate, climate-controlled storage unit specifically for original engines, transmissions, and rare trim pieces she's acquired over the years. One evening, the storage unit facility experiences a break-in, and several high-value components are stolen. Her standard homeowner's policy offers minimal coverage for such items, if any. However, her classic car policy with spare parts coverage would step in, compensating her for the loss of those irreplaceable components, up to the agreed limit, allowing her to replace or re-source them without a crippling financial blow.
Inflation Guard: Keeping Pace with Rising Values
The classic car market can be volatile, with values fluctuating, and often, appreciating significantly over time. This is fantastic news for collectors, but it poses a challenge for insurance. If you set your Agreed Value today, what happens if your car's market value jumps 10-15% next year? Without an update, you could be underinsured.
Inflation Guard is an endorsement that automatically adjusts your Agreed Value upward by a small, pre-determined percentage (e.g., 2% to 6%) each year at renewal, without requiring a new appraisal. This helps ensure that your coverage keeps pace with modest market appreciation, protecting you from being underinsured if your car's value increases steadily. It’s a thoughtful feature that acknowledges the dynamic nature of collectible vehicle values. This ensures that you aren't stuck with an outdated valuation, making Inflation Guard Coverage Explained a valuable tool for savvy collectors.
Think of John in North Carolina, whose 1965 Shelby GT350 has steadily appreciated in value over the last few years. While he regularly checks market trends, he might forget to formally update his policy every single year. With Inflation Guard, his $250,000 Agreed Value policy automatically adjusts to $257,500 (with a 3% increase) at renewal, reflecting the natural upward trend in the market without him having to submit new documentation each time. This proactive protection means his payout will be closer to the actual market value if a total loss occurs.
Roadside Assistance and Towing for Classics
Breaking down is never fun, but it can be particularly stressful with a classic car. You can't just call any tow truck; your vintage ride needs specialized care, like a flatbed tow, to prevent further damage to its suspension, drivetrain, or bodywork. A standard hook-and-chain tow can easily ruin a classic.
Specialty classic car insurance policies offer roadside assistance and towing specifically designed for collectibles. This coverage typically includes:
- Flatbed Towing: Ensuring your car is transported safely without putting stress on its components.
- Battery Jump-Starts: For those moments when the battery decides to quit.
- Flat Tire Service: Even classics get flats.
- Fuel Delivery: If you misjudge that gas gauge.
Having this specialized service means that if your vintage Porsche 911 breaks down on a scenic drive, you can call a number knowing that a qualified service will dispatch a flatbed, not a standard tow truck that could cause more harm than good. This is a crucial practical consideration, making Roadside Assistance Coverage for Classic Cars Explained an essential add-on for any driver.
Picture David and his wife enjoying a Sunday drive through the Colorado mountains in their 1957 Chevrolet Bel Air. Suddenly, a minor mechanical issue leaves them stranded on the side of a winding road. Instead of panicking about how to get his classic home without damaging it further, David simply calls his classic car insurer's roadside assistance line. Within an hour, a professional with a flatbed tow truck arrives, carefully loads the Bel Air, and transports it directly to his preferred mechanic, saving David a lot of stress and potential repair costs from improper towing.
Navigating Usage-Specific Coverages
Classic cars aren't driven like modern vehicles. They have specific uses, from leisurely drives to competitive events, and their insurance policies reflect these distinct patterns.
Coverage for Car Shows, Events, and Tours
One of the greatest joys of owning a classic car is sharing it with others, whether that's at a local Cars and Coffee, a national concours d'elegance, or a multi-day rally. These events, while fun, come with their own set of risks, from accidental damage in crowded parking lots to potential theft during transit or while on display.
Many specialty classic policies include coverage for these specific usage scenarios. This can extend to:
- Transit Coverage: Protecting your car while being transported to and from an event.
- While on Display: Coverage for damage or theft during the event itself.
- Touring/Rally Coverage: Ensuring you're covered during organized drives or non-competitive rallies.
This specialized coverage gives you the freedom to participate in the classic car community without constantly worrying about potential financial losses. It's about protecting your passion while you're out living it. Companies like Grundy and Hagerty understand the importance of these events to collectors.
Consider Maria, a proud owner of a restored Datsun 240Z, who regularly attends local car shows in Arizona. During one such event, while her car is parked and on display, an excited spectator accidentally leans against the fender, leaving a noticeable dent. Thanks to her classic car policy, which includes coverage for show and event participation, the damage is covered, and she can get it repaired without dipping into her savings. This specific protection allows her to continue showcasing her beloved classic without undue worry.
Trip Interruption for Long-Haul Adventures
Sometimes, a classic car isn't just for local cruises; it's for epic road trips. Imagine taking your vintage Mustang on a journey across state lines or down legendary routes like Route 66. While thrilling, these longer trips carry a higher risk of unexpected breakdowns or issues far from home.
Trip interruption coverage is a fantastic add-on for collectors who love to embark on these longer adventures. If your classic breaks down a significant distance from home (often 100 miles or more) and requires an overnight stay for repairs, this coverage can help with:
- Lodging Expenses: Covering hotel costs while you wait for repairs.
- Rental Car Costs: Providing a rental car to continue your journey or return home.
- Meals: Contributing to meal expenses during the delay.
This coverage takes some of the sting out of an unexpected delay, allowing you to enjoy your journey with greater peace of mind, knowing that if something goes wrong, you won't be left completely stranded and out of pocket.
Let's say the O'Malley family from Illinois decides to take their classic Volkswagen Beetle on a leisurely two-week tour through the scenic backroads of Tennessee. Halfway through their trip, the Beetle develops an unforeseen mechanical issue that requires a few days in a specialized shop. Their classic car insurance policy with trip interruption coverage would cover their hotel stays and a rental car to continue exploring or return home, significantly reducing the financial burden and stress of an unexpected delay.
Storage-Only and Laid-Up Coverage
Not all classic cars are driven regularly. Many are project cars, non-running display pieces, or winterized vehicles that spend months in storage. For these situations, having a full-blown "driving" policy might be overkill and unnecessarily expensive.
Storage-only or laid-up coverage is designed for vehicles that are strictly stored and not driven. This type of policy typically includes comprehensive coverage (protecting against theft, fire, vandalism, natural disasters) but excludes liability and collision, as the car isn't on the road. This can significantly reduce premiums while still protecting your investment from non-driving-related risks. It's perfect for cars undergoing lengthy restorations, seasonal vehicles, or those that are simply part of a static collection. This can be especially useful for Classic Car Insurance Without a Daily Driver needs.
Imagine Robert, who lives in New York, owns a stunning 1963 Split-Window Corvette that he keeps in a secure, climate-controlled facility. He only takes it out for special events a few times a year. For the majority of the year, it's laid up. He opts for storage-only coverage, which provides excellent comprehensive protection against fire, theft, or damage while it's stored, but at a much lower premium than a full driving policy. This allows him to protect his significant investment without paying for liability and collision coverage he doesn't need for a car that isn't actively being driven.
Understanding Deductibles and Payouts
Just like with regular car insurance, classic car policies come with deductibles and specific processes for handling claims and payouts. Understanding these elements is key to making informed decisions about your coverage.
Choosing the Right Deductible for Your Classic
A deductible is the amount you agree to pay out-of-pocket before your insurance coverage kicks in for a claim. For classic car insurance, deductibles work much the same way. You'll typically have options ranging from a low deductible (e.g., $0, $100, $250) to higher amounts (e.g., $500, $1,000, or even more).
Choosing the right deductible involves balancing premium costs with your financial comfort level. A higher deductible will usually result in lower annual premiums, as you're taking on more of the initial risk. Conversely, a lower deductible means you'll pay more upfront for your policy, but less out-of-pocket if you need to file a claim. Given the potentially high cost of classic car repairs, some collectors prefer a lower deductible for peace of mind, even if it means a slightly higher premium. It's a personal choice based on your risk tolerance and financial situation. For a deeper dive into the cost implications, check out Classic Car Insurance Deductibles Explained.
Consider Emily, a collector in Virginia with a cherished 1969 Charger. She's a careful driver, but accidents can happen. She decides to opt for a $250 deductible. While her annual premium might be slightly higher than if she chose a $1,000 deductible, she knows that if she ever needs repairs, her out-of-pocket expense will be minimal, which is a huge comfort given the specialized parts and labor required for her muscle car.
How Claims Affect Your Classic Car Policy
When a claim occurs with a classic car, the process is usually handled with a bit more white-glove service than a standard claim. Because of the Agreed Value policy, there's less back-and-forth about the car's worth in a total loss situation. For repairs, specialty insurers understand the need for specialized shops, original parts, and expert craftsmanship to maintain the car's integrity and value. They typically work with you to ensure your classic goes to a reputable shop that understands the nuances of vintage vehicle repair.
While filing a claim can still be a hassle, the goal of a specialty classic insurer is to restore your car to its pre-loss condition or provide you with the full Agreed Value if it's a total loss, ensuring your investment is truly protected. Unlike standard policies where a minor claim might significantly hike your rates, classic car insurers often consider the infrequent use of these vehicles, which can sometimes lead to less drastic rate increases after a single claim, depending on the severity and circumstances. You can learn more about how to navigate this process in our guide on How to File a Classic Car Insurance Claim.
Common Exclusions and What Classic Car Insurance Doesn't Cover
It's just as important to understand what your classic car insurance policy doesn't cover as it is to know what it does. Misunderstandings about exclusions can lead to nasty surprises when you need coverage most.
Daily Driving and Commuting Limitations
This is perhaps the most significant exclusion for many classic car policies. Specialty classic car insurance is priced affordably precisely because insurers assume your car is not a daily driver. These policies are generally intended for vehicles used for pleasure driving, car shows, club events, and occasional tours. They are not meant for commuting to work, running errands multiple times a week, or serving as your primary mode of transportation.
If you attempt to use a classic car insured under a pleasure-use policy as a daily driver, you could risk having a claim denied. Insurers may have specific mileage limitations (e.g., 2,500, 5,000, or 7,500 miles per year) or explicit clauses about the nature of usage. If you need to drive your classic more frequently, some specialty insurers like Hagerty do offer programs for "modern collectibles" or more flexible mileage options, but these are distinct from traditional classic policies. It's crucial to be honest about your intended usage to ensure your coverage is valid. For those who enjoy more frequent drives, it's worth exploring options like Classic Car Insurance for a Daily Driver.
Let's consider Mike, who works from home in Wisconsin but occasionally drives his classic 1978 Firebird Trans Am to pick up groceries or drop off his kids at school. While these aren't traditional commutes, if he's doing it frequently and exceeding his policy's stated mileage limit or pleasure-use restrictions, he could be in hot water. If he gets into an accident during one of these "daily driver-esque" trips, his insurer could deny the claim, leaving him with a totaled car and no payout, all because he wasn't adhering to the policy's usage terms.
Racing and Track Day Exclusions
For many classic car enthusiasts, the thrill of the track, whether it's drag racing or road course events, is a major draw. However, nearly all standard classic car insurance policies explicitly exclude coverage for competitive racing, timed events, or open track days. The risks associated with these activities are simply too high for typical collector car insurance.
If you plan to take your classic on a track, even for non-competitive events, you will need to seek out separate, specialized track day insurance. This is a standalone policy that covers damage to your vehicle during track use. Attempting to claim track damage under a pleasure-use classic policy will almost certainly result in a denial. It’s important to understand this distinction to avoid a costly misunderstanding.
Wear and Tear: The Nature of Older Vehicles
Classic car insurance, like all insurance, is designed to cover sudden and accidental losses. It does not cover normal wear and tear, mechanical breakdowns, or gradual deterioration that is part of owning an older vehicle. For example, if your engine throws a rod due to age or lack of maintenance, your classic car insurance policy won't cover the repair costs. Similarly, if your paint is fading from sun exposure over decades, that's not an insurable event.
These policies are about protecting against unexpected damage from incidents like collisions, theft, fire, or vandalism, not the natural aging process of mechanical components or cosmetic degradation. Regular maintenance and preventative care remain the owner's responsibility to keep the car in top shape.
Building Your Perfect Classic Car Insurance Policy
Putting together the right classic car insurance policy isn't a one-size-fits-all endeavor. It requires careful consideration of your specific vehicle, how you use it, and your personal risk tolerance.
Assessing Your Needs and Your Car's Value
Before you even start looking for quotes, take a detailed inventory of your classic car. What is its current condition? Has it been restored? If so, to what level (driver, show, concourse)? What modifications, if any, have been made? Gather documentation like appraisal reports, restoration receipts, and clear photos. This information will be crucial in determining your Agreed Value and ensuring you get appropriate coverage. Think realistically about how often you drive it and for what purposes. Is it purely for shows and occasional weekend cruises, or do you take it on longer road trips? These factors will influence the types of endorsements you need. You'll find helpful resources on How to Choose Classic Car Insurance.
Here's a quick checklist to guide your assessment:
| Aspect | Considerations | Why it Matters for Insurance |
|---|---|---|
| Vehicle Type | Make, Model, Year, VIN. Is it a muscle car, antique, vintage, exotic, or modern collectible? | Affects eligibility, valuation, and specific risks. Some insurers specialize in certain types. |
| Condition | Original, restored (level of restoration), modified, project car, barn find. Documentation (photos, receipts) is key. | Directly impacts Agreed Value and eligibility for restoration coverage. Insurers need to know current state. |
| Usage | Pleasure driving, car shows, club events, touring, occasional errands, seasonal storage. Daily driver status? | Determines eligibility for classic policies, mileage limits, and the need for usage-specific endorsements. |
| Storage | Secure, locked garage (attached or detached), carport, public storage. Security features (alarm, fire suppression)? | Influences rates and may be an eligibility requirement for some policies. Secure storage demonstrates care. |
| Ownership | Single owner, multiple owners, in a trust or LLC. | May affect policy titling and who can make decisions about the vehicle and policy. |
| Additional Items | Spare parts collection, automobilia, specialized tools for your classic. | Requires separate endorsements like spare parts coverage or collectibles coverage. |
| Driver Profile | Your driving record, age, experience with classic cars, other drivers in the household. | Affects eligibility and premium rates, especially for young or inexperienced drivers. |
Working with a Specialty Insurer
When it comes to classic car insurance, going with a specialty insurer like Hagerty, Grundy, or American Collectors Insurance is almost always the best path. These companies live and breathe classic cars. They understand the nuances of valuation, the unique risks, and the specific needs of collectors far better than a general auto insurance provider might. They have dedicated claims departments staffed by individuals who know the difference between a hemi and a small block, and they often have networks of specialized repair shops. Trying to insure a classic with a standard carrier can lead to frustrating valuation disputes and inadequate coverage, potentially costing you far more in the long run. If you're wondering where to start, looking into Best Classic Car Insurance Companies is a smart move.
Regularly Reviewing Your Coverage
The classic car market isn't static, and neither are your needs or your car's condition. If you complete a major restoration, make a significant upgrade, or if market values for your specific model soar, your Agreed Value might need to be adjusted. It's a good practice to review your policy annually, or at least every few years, to ensure your Agreed Value accurately reflects your car's current worth and that your coverages still meet your needs. Don't wait until something happens to realize you're underinsured! Staying proactive will give you the best protection. You can explore how to update your policy by reading How to Increase Agreed Value at Renewal.
Disclaimer
Please remember that this article is intended for informational purposes only and does not constitute financial or legal advice. Insurance policies vary widely, and it's crucial to consult with a qualified insurance professional to discuss your specific needs and obtain personalized quotes and coverage details. Always read your policy documents carefully to understand your coverage, exclusions, and obligations.