Why Classic Car Insurance Is Cheaper Than Regular
It sounds completely counterintuitive, doesn't it? You cherish your classic car, often investing significant time and money into its upkeep, and yet, when you go to insure it, you might find the premiums are surprisingly lower than what you pay for your everyday sedan. This common perplexity stems from a fundamental misunderstanding of how specialty classic car insurance works and how it differs from a standard auto policy. This guide will walk you through the key reasons why classic car insurance often comes with a more budget-friendly price tag, ensuring you understand how to leverage these advantages for your own prized possession.
The Fundamental Shift in Risk Assessment
The biggest reason classic car insurance can be significantly cheaper boils down to how insurers perceive the risk associated with these vehicles. Unlike your modern daily driver, which faces the rigors of commuting, parking lots, and rush hour, a classic car typically lives a much more pampered life. This reduced exposure translates directly into lower actuarial risk for the insurance company.
Your Classic is a Lower Risk Bet
Think about it: when was the last time you saw a meticulously restored 1969 Chevrolet Camaro parallel-parked precariously on a busy city street during peak shopping hours? Probably never. Classic cars, by their very nature and the way their owners treat them, are inherently less risky for an insurer. They aren't stuck in bumper-to-bumper traffic every morning, exposed to fender benders. They aren't left unattended in sprawling parking lots where door dings and minor collisions are commonplace. Instead, these vehicles are often reserved for weekend cruises, car shows, club events, or leisurely drives on scenic routes. This dramatically lower frequency of use and careful handling means a much lower probability of an accident, a theft, or other damage.
Furthermore, the drivers of classic cars tend to be a specific demographic. They are often mature, experienced drivers who understand the value and fragility of their vehicle. They're not joyriding teenagers or commuters rushing to work. This inherent responsibility in classic car ownership further reduces the risk profile, making them a more attractive and less costly proposition for insurance providers. It's a calculated bet, and for classics, the odds are usually in favor of fewer claims.
Understanding the "Agreed Value" Advantage
One of the most significant differentiators in classic car insurance is the concept of "Agreed Value" coverage, and it plays a huge role in why premiums can be lower. With a standard auto policy, your car is typically covered for its Actual Cash Value (ACV), which means its market value minus depreciation at the time of a total loss. This can be a devastating outcome for an owner of a vintage vehicle, as a standard insurer might only pay out a fraction of what you believe your classic is truly worth, leaving you scrambling to replace it or cover restoration costs. This is a common frustration for collectors who have poured their heart and soul into a specific build, only to find its perceived value by a standard insurer is far less than their investment.
Agreed Value, on the other hand, is a pre-determined amount that you and your classic car insurer agree upon before your policy even begins. If your classic car is stolen or totaled, the insurer pays out this exact agreed-upon amount, no questions asked about depreciation. While this might sound like it would increase the premium, it actually stabilizes the risk for the insurer. They know exactly what their maximum payout will be from day one. This clarity, combined with the other lower risk factors, allows specialty insurers to offer more competitive rates. They're not constantly trying to re-evaluate a fluctuating market value after an incident; the value is set, providing peace of mind for both you and the insurance company. If you're looking to compare options, understanding the nuances between Agreed Value vs Stated Value vs Actual Cash Value is critical.
Usage Limitations and Mileage Restrictions
The way you use your classic car is a primary determinant of your insurance costs. Unlike a regular car that's expected to be driven daily without limitation, classic car policies come with specific stipulations about usage that drastically reduce the insurer's exposure to risk.
The Pleasure-Use Principle
Classic car insurance policies are almost universally built around the "pleasure-use" principle. This means your classic isn't insured for daily commuting, running errands, or general transportation. Instead, it's covered for activities like leisurely drives, club events, car shows, parades, and occasional trips for maintenance or repairs. This restriction is a huge factor in the lower premiums. An insurer knows that a car driven only on sunny Sundays for a few miles to a local show is exponentially less likely to be involved in an accident than a car navigating congested highways five days a week.
This fundamental difference in expected usage is a cornerstone of specialty classic car insurance. It acknowledges the specific role these vehicles play in their owners' lives – a hobby, a passion, a showpiece – rather than a workhorse. It's also why many standard insurers struggle to offer competitive rates for classics; their risk models are simply not designed for this type of limited, careful use. They calculate risk based on average daily use, which doesn't apply to classics. Understanding the Pleasure-Use Requirement Explained can help you determine if a specialty policy is right for your vehicle.
Restricted Mileage: Less Time on the Road, Less Risk
Closely tied to pleasure use are mileage restrictions. Most classic car insurance policies come with annual mileage caps, often ranging from 1,000 to 7,500 miles per year, with options like 2,500 or 5,000 miles being quite common. Some policies might even offer unlimited mileage for certain types of vehicles or drivers, but generally, the less you drive it, the lower your premium. This isn't just about reducing wear and tear on your precious vehicle; it's a direct reflection of risk. Fewer miles on the road mean less exposure to accidents, less chance of theft, and less wear on components that might fail.
For many classic car owners, these mileage limits are perfectly adequate. Most enthusiasts aren't putting thousands of miles on their vintage rides each month. They're taking them out for specific events or short, enjoyable drives. By agreeing to these limitations, you're signaling to the insurer that your vehicle is a low-risk asset. For example, a collector in Arizona who only drives their Ford Thunderbird to local car meets a few times a month will naturally have a lower risk profile than someone driving a new SUV across the state for work daily. It's this commitment to responsible, limited use that helps keep those classic car insurance rates surprisingly affordable. It's worth looking into Classic Car Insurance Mileage Limits by State to understand specific regulations that might apply to you.
The Dedicated Owner and Storage Factor
Beyond how the car is used, who owns it and where it's kept also play a crucial role in lowering insurance costs for classic vehicles. Specialty insurers recognize that classic car owners are a different breed of driver, and their storage habits reflect their dedication.
Responsible Drivers, Secure Garages
Classic car owners are, by and large, incredibly responsible and careful individuals. They've often invested significant time, effort, and money into their vehicles, whether through restoration, maintenance, or simply the initial purchase. This deep personal investment means they drive more cautiously, are highly aware of their surroundings, and actively avoid risky driving situations. They're not just protecting a mode of transport; they're safeguarding a piece of history, an investment, and a passion. Insurers understand this psychological profile translates into a much lower likelihood of reckless driving or at-fault accidents. This responsible driver profile significantly reduces the overall risk, making classic car policies more affordable.
Furthermore, secure storage is almost always a requirement for classic car insurance. Most policies mandate that the vehicle be kept in a locked, private garage when not in use. This isn't just a suggestion; it's a fundamental condition for coverage. A car stored safely behind closed doors, away from public view, is far less susceptible to theft, vandalism, or environmental damage like hail or falling branches, compared to a vehicle parked on the street or in an open driveway. This commitment to secure storage acts as a powerful preventative measure, directly reducing the potential for claims and, in turn, lowering premiums. Understanding the Garage Storage Requirement for Classic Cars can help you prepare for a classic policy.
The "Daily Driver" Requirement
Another common, and often overlooked, factor that contributes to lower classic car insurance costs is the requirement that the classic vehicle not be your primary mode of transportation. In other words, you generally need to own and insure a separate "daily driver" for regular use. This might seem like an extra hurdle, but it's a critical component of the risk assessment. By ensuring you have another vehicle for your everyday needs, the insurer solidifies the classic's role as a leisure or hobby vehicle. This reinforces the limited mileage and pleasure-use restrictions, further reducing the overall risk profile.
This requirement ensures that your classic isn't exposed to the daily grind of commuting, parking lot scrapes, or constant highway miles. It's a clear signal to the insurance company that the classic is a cherished item, brought out for special occasions, and thus less likely to incur damage. While it means an additional vehicle to maintain and insure, the benefit is often a significantly lower premium for your classic, making it a worthwhile trade-off for many enthusiasts. Some specialty carriers, like Hagerty, offer excellent coverage for these secondary vehicles, often understanding the multi-car collector's needs. If you're wondering if Do You Need a Separate Car for Classic Insurance, the answer is almost always yes for the best rates.
Specialized Coverage, Tailored Rates
Standard insurance companies often struggle with classic cars because their models aren't built for these unique vehicles. Specialty insurers, however, have developed tailored coverages and pricing structures that perfectly fit the classic car hobby, often leading to more favorable rates.
Beyond Standard Policies: What Specialty Insurers Offer
Generic auto insurance policies are designed for modern cars with rapidly depreciating values, widely available parts, and common repair shops. Classic cars, on the other hand, often appreciate in value, require specialized parts (sometimes custom-fabricated), and demand expert mechanics who understand vintage technology. When a standard insurer tries to fit a classic into their existing framework, it often results in either extremely high premiums (because they don't understand the unique, lower risks) or inadequate coverage (especially regarding valuation).
Specialty classic car insurers, like Hagerty or American Collectors Insurance, are different. They understand the nuances of the collector car market inside and out. Their policies are built from the ground up to protect classics, offering features like Agreed Value (as discussed), spare parts coverage, restoration coverage, and even automobilia coverage. This specialization means they can accurately assess the true risk and value, leading to more appropriate and often lower premiums. They're not guessing; they're working with a deep understanding of the classic car community, its values, and its behaviors. This is why Classic Car Insurance vs Regular Insurance: What's Required highlights these distinct differences.
Discounts Built for Enthusiasts
Classic car insurance isn't just cheaper because of lower risk; it's also cheaper because specialty insurers offer a range of discounts specifically catering to the classic car enthusiast. These aren't your typical multi-policy or good driver discounts (though those can still apply). Instead, they recognize and reward the behaviors and affiliations common among collectors.
Consider these common discounts:
- Car Club Membership: Many insurers offer a discount if you're a member of a recognized classic car club, like the Classic Car Club of America or a local Mustang owners group. This again reinforces the idea of a responsible, engaged owner.
- Multi-Vehicle Discount: If you have multiple classic cars, bundling them under a single specialty policy can often lead to significant savings per vehicle. Insurers love to cover entire collections.
- Security Features: Beyond a locked garage, if your classic has advanced security systems, alarms, or tracking devices, you might qualify for additional discounts.
- Approved Driver Age: While not always a discount, many policies favor more experienced drivers (often 25 or older), which typically aligns with the demographic of classic car owners, leading to lower base rates.
- Restoration Process: Some insurers offer discounts or flexible coverage options if your car is undergoing restoration, as it's not on the road during that time.
These specialized discounts acknowledge and reward the very characteristics that make classic car ownership a lower risk endeavor for the insurer, directly contributing to the overall affordability. Exploring Classic Car Insurance Discounts Explained can reveal more ways to save.
How Claims and Repairs Differ for Classics
The nature of claims and repairs for classic vehicles further contributes to their lower insurance costs. Specialty insurers handle these situations with a unique approach, often resulting in fewer total losses and more cost-effective outcomes in the long run.
Maintaining Authenticity and Value
When a classic car is involved in an accident, the repair process is vastly different from that of a modern vehicle. For a daily driver, the goal is often to get it safely back on the road using readily available aftermarket parts or new OEM parts, with little concern for original components. For a classic, however, authenticity and originality are paramount. Using incorrect parts or substandard repair techniques can significantly diminish a classic's value, which is precisely what specialty insurers aim to protect.
Because of this, specialty insurers often work with networks of skilled restorers and classic car mechanics who understand how to repair vintage vehicles using period-correct parts or techniques. This might sound more expensive upfront, but it reduces the risk of the car's value plummeting after a repair. In some cases, a carefully restored classic can even increase in value. For example, if a 1957 Chevrolet Bel Air sustains damage, a specialty insurer will ensure repairs are done with an eye toward preserving its historical accuracy and market value, rather than just patching it up cheaply. This approach to claims management, focused on preserving the asset's inherent worth, ultimately contributes to the overall stability and affordability of classic car insurance.
Reduced Likelihood of Total Loss
Due to the Agreed Value coverage we discussed earlier, and the general care taken with these vehicles, classic cars have a reduced likelihood of being declared a "total loss" in the same way a modern car might be. For a modern car, if the repair cost exceeds a certain percentage of its Actual Cash Value, it's often totaled. Given rapid depreciation, minor damage can quickly push a modern car into total loss territory.
With Agreed Value coverage, the bar for a total loss is much higher because the agreed-upon value is typically substantial and doesn't depreciate. Furthermore, the dedication of classic car owners often means they are deeply invested in their vehicle's survival and restoration. Insurers know that owners will go to great lengths to repair their classics, even if the cost is high, rather than just junking them. This willingness to repair, combined with the often higher agreed-upon values, means fewer total loss payouts for the insurer. When payouts for total losses are less frequent, it helps keep premiums down across the board for all policyholders. This is a critical aspect when considering How Agreed Value Affects Premiums and why it’s so beneficial for collectors.
The Long-Term Value Proposition
Classic cars are not just vehicles; they are investments, passion projects, and often appreciating assets. Specialty classic car insurance understands this unique dynamic, offering a value proposition that goes far beyond simply covering potential damages.
Protecting an Appreciating Asset
One of the most compelling aspects of classic car ownership is the potential for appreciation. Unlike most modern vehicles that lose value the moment they're driven off the lot, many classics, especially well-maintained or rare models, can actually increase in market value over time. Think about a pristine 1963 Split-Window Corvette or a sought-after 1970 Plymouth Hemi 'Cuda – their values have consistently climbed.
Standard auto insurance models are simply not equipped to handle appreciating assets; they are designed for depreciation. This is where specialty classic car insurance shines. With Agreed Value coverage, you're not just insuring against loss; you're protecting the current and future value of your investment. Many specialty policies even offer "Inflation Guard" coverage, which automatically adjusts your Agreed Value upwards by a certain percentage each year (e.g., 2-6%) to account for market appreciation, ensuring your coverage keeps pace with your car's rising worth without you having to re-appraise it annually. This proactive protection of an appreciating asset is a testament to the specialized understanding these insurers have, and it means your insurance truly works to safeguard your entire investment, making the seemingly lower premium an even better long-term deal.
Finding the Right Partner for Your Passion
Ultimately, the reason classic car insurance is cheaper than regular insurance boils down to a fundamental alignment of values and understanding between the insurer and the policyholder. Specialty carriers aren't just selling a product; they're providing a service tailored to a passionate community. They understand the unique relationship you have with your classic car, the care you put into it, and the specific way you use it. This nuanced understanding allows them to price policies more accurately and, often, more affordably.
Companies like Hagerty have built their entire business around this philosophy. They offer more than just insurance; they provide valuation tools, a community, and resources that truly benefit classic car owners. When you choose a specialty insurer, you're not just getting a policy; you're gaining a partner who genuinely appreciates and understands the collector car world. This partnership approach, where the insurer's goals align with the owner's commitment to preservation and careful use, creates a synergistic relationship that results in lower costs and superior coverage compared to trying to fit a square peg (your classic) into a round hole (a standard auto policy). It’s clear why more collectors are choosing dedicated providers when considering How to Choose Classic Car Insurance.
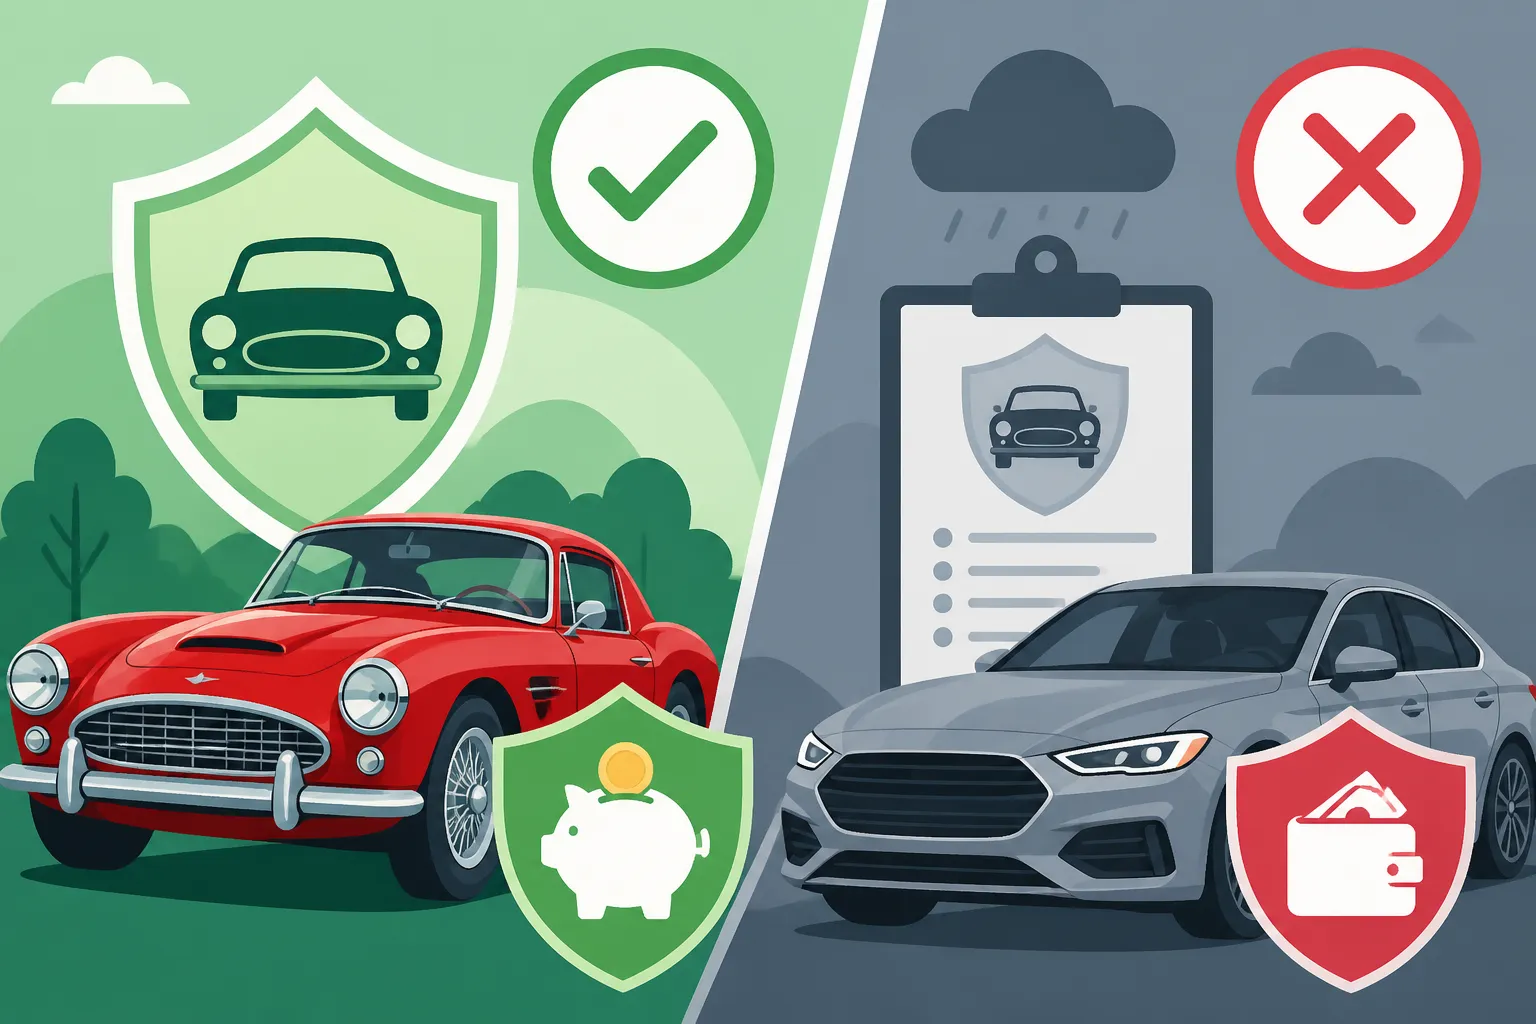
| Feature | Classic Car Insurance (Specialty) | Regular Car Insurance (Standard) |
|---|---|---|
| Valuation Method | Agreed Value (Fixed payout for total loss, pre-determined) | Actual Cash Value (Market value minus depreciation) |
| Usage Restrictions | Limited to pleasure use, car shows, club events; no daily commuting | Unrestricted daily driving, commuting, errands |
| Mileage Limits | Often includes annual mileage caps (e.g., 1,000-7,500 miles) | Typically no mileage limits |
| Storage Requirements | Usually requires secure, private garage storage | No specific storage requirements beyond reasonable care |
| Driver Profile | Targets responsible, experienced drivers with other daily vehicles | Covers wide range of drivers, including less experienced or high-risk |
| Parts & Repairs | Focus on authentic, period-correct parts and specialized repair shops | Focus on readily available OEM/aftermarket parts and general repair shops |
| Value Trend | Often covers appreciating assets, may include Inflation Guard | Covers depreciating assets |
| Cost Tendency | Generally lower premiums due to lower risk profile and specific coverage | Generally higher premiums for comparable coverage due to higher risk |
| Additional Coverage | Spare parts, restoration, automobilia, trip interruption | Rental car, towing, uninsured motorist |
Disclaimer
The information provided in this article is for general informational purposes only and does not constitute financial, legal, or insurance advice. While we strive to provide accurate and up-to-date content, insurance policies and requirements can vary significantly by state, insurer, and individual circumstances. It is essential to consult with a qualified insurance professional or agent to discuss your specific needs and obtain personalized quotes and advice for your classic car. Always read your policy documents carefully to understand your coverage, limitations, and exclusions.