How Storage Affects Classic Car Rates
It's a common headache for classic car owners: you’ve meticulously restored your dream machine, polished every chrome piece, and now you’re looking at insurance, only to find out that where you keep it can dramatically impact your premiums. The truth is, how you store your classic isn’t just a logistical detail; it's a make-or-break factor for insurers, influencing everything from eligibility to the final cost of your policy. This comprehensive guide will peel back the layers, explaining precisely how your classic car's home affects its insurance rates and what you can do about it.
The Basics of Classic Car Insurance and Storage
When it comes to insuring your beloved classic, insurers look at a whole different set of criteria compared to your daily driver. One of the most significant, and often misunderstood, factors is how and where your vehicle is stored. It’s not just about protecting the car from the elements; it’s about demonstrating a commitment to its preservation and security, which directly translates to lower risk for the insurance company.
Why Storage Matters So Much to Insurers
Think about it from an insurer's perspective: a classic car isn't just a mode of transport; it's an investment, often a passion project, and certainly a prized possession. Unlike a modern car that might sit in a parking lot all day, classic cars are typically driven sparingly and cherished. The environment they're kept in speaks volumes about how well they're protected from theft, vandalism, and environmental damage. A car left on the street or in an unsecured area is inherently at a much higher risk of damage or theft than one tucked away in a locked, private garage. This higher risk directly translates to a higher likelihood of a claim, which means higher premiums for you. If you're wondering, "Why is classic car insurance cheaper than regular?" a big part of the answer lies in these reduced risk factors, with proper storage being paramount.
The Core Principle: Risk Mitigation
At its heart, insurance is all about risk. Insurers assess the probability of a claim occurring and the potential cost of that claim. For classic cars, proper storage is one of the most effective forms of risk mitigation. A secure, enclosed storage space reduces exposure to many common perils:
- Theft: A locked garage is a significant deterrent compared to a public street.
- Vandalism: Classic cars, especially those in pristine condition, can attract unwanted attention. An enclosed space hides them from view.
- Environmental Damage: Hail, falling branches, extreme temperatures, and even prolonged sun exposure can wreak havoc on vintage paint, chrome, and interiors. A garage protects against these.
- Accidental Damage: Lesser chance of fender benders or scrapes from other vehicles if it's not parked in a crowded area.
Because classic car owners often take exceptional care of their vehicles, including how they store them, the overall risk profile is lower. This is precisely why specialty insurers like Hagerty emphasize the importance of secure storage. They understand that a responsible owner will go the extra mile to protect their investment, and they reward that diligence with more favorable rates and specialized coverage options. This commitment to risk mitigation is a cornerstone of how classic car insurance functions, differentiating it significantly from standard auto policies.
Common Storage Options and Their Impact on Rates
The type of storage you have available for your classic car isn't just a preference; it's a critical factor that can make or break your ability to get collector car insurance, and it certainly dictates your premiums. Insurers have very specific ideas about what constitutes acceptable storage, and deviating from those can lead to higher costs or outright denial of coverage.
Garaged at Home: The Gold Standard
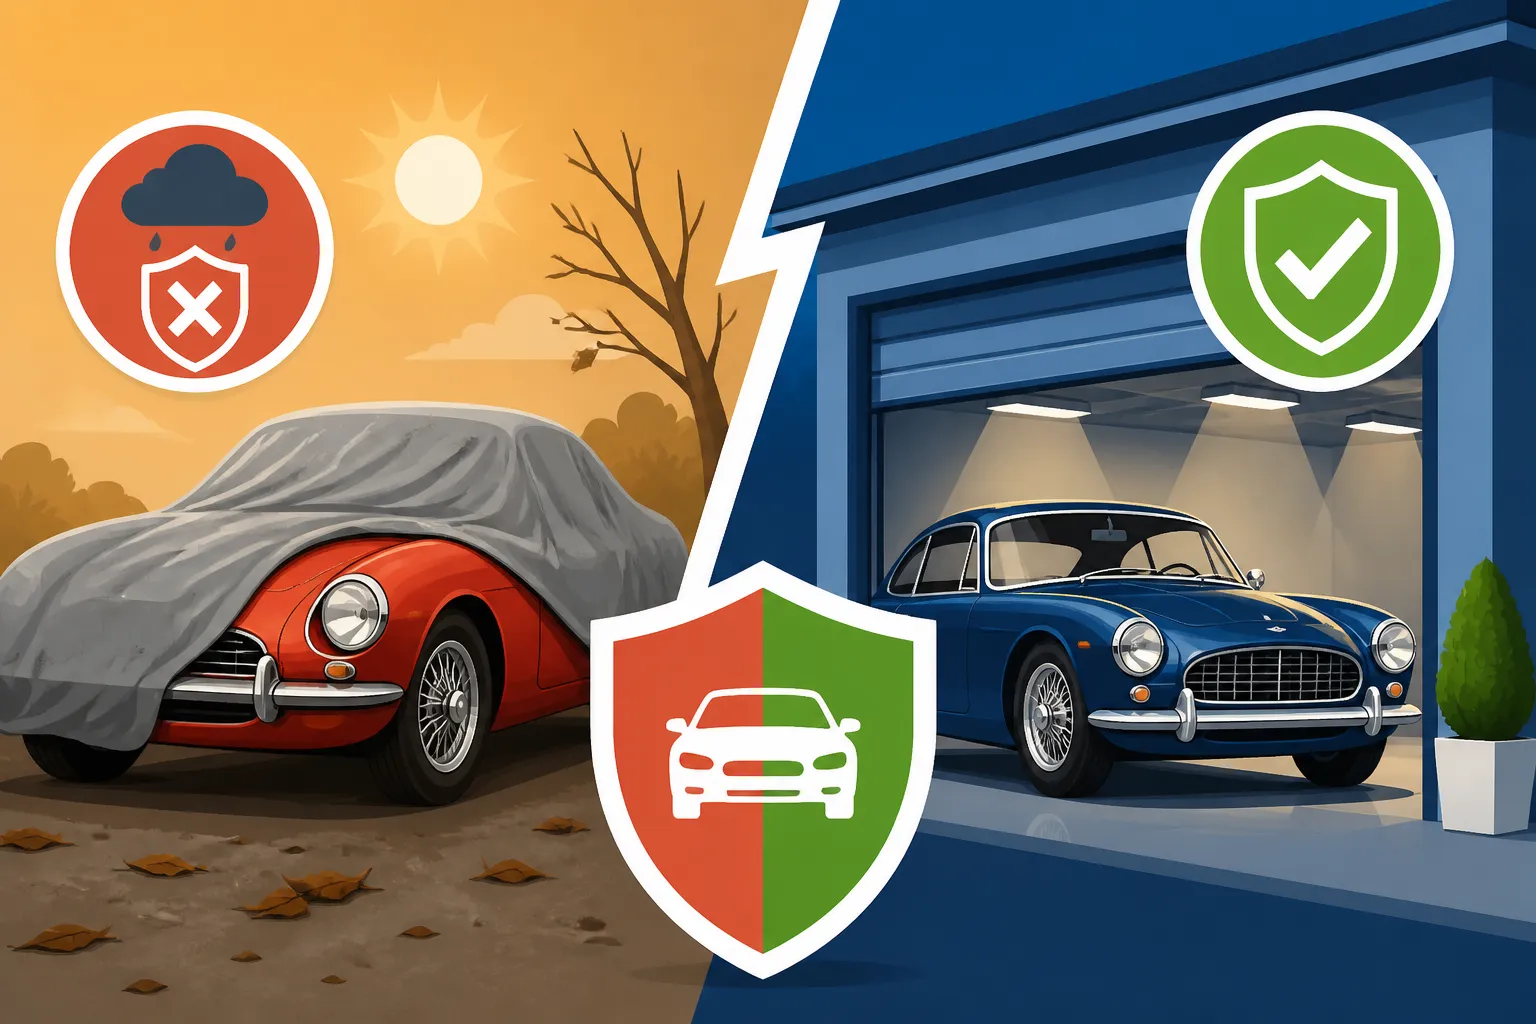
When insurers talk about proper classic car storage, they almost always envision a private, enclosed garage at your residence. This is considered the "gold standard" for a reason.
- Attached vs. Detached Garages: While both are generally acceptable, an attached garage might sometimes be viewed as slightly more secure, as it's directly connected to your home and benefits from the same security measures. A detached garage, especially if it has robust locks, an alarm, and is well-maintained, is also perfectly fine. The key is "enclosed" and "secure."
- Security Features: A simple, locked garage door is a good start, but adding further security features can impress insurers and potentially lower rates. This could include heavy-duty deadbolts, motion-sensor lighting, an alarm system linked to your home security, or even surveillance cameras. These aren't always required for a basic policy but are highly recommended and can sometimes qualify you for Classic Car Insurance Discounts Explained.
- Rate Benefits: Housing your classic in a private, locked garage at home signals to insurers that the vehicle is well-protected and not regularly exposed to the elements or public view. This significantly reduces the risk of theft, vandalism, and weather-related damage, directly translating to lower insurance premiums. Most classic car policies implicitly assume this level of storage, as highlighted by Garage Storage Requirement for Classic Cars.
Carports, Driveways, and Street Parking: The Red Flags
This is where things get tricky, and often, expensive or impossible. Parking your classic in anything less than an enclosed, secure garage is generally a non-starter for most specialty classic car insurers.
- Carports: While they offer some protection from direct sun or light rain, carports are open to the elements and highly vulnerable to theft and vandalism. Most classic car insurers, including major players like Hagerty, will be very hesitant to cover a classic stored exclusively in a carport. If they do, the premiums will be significantly higher, reflecting the increased risk.
- Driveways and Street Parking: This is almost universally unacceptable for classic car insurance. A car parked in a driveway or on the street is at maximum risk for theft, collision (from other vehicles, even parked), vandalism, and weather damage. It immediately disqualifies a vehicle from most dedicated classic car policies, as it goes against the core principle of low-risk, careful ownership. If you're asking, "Can You Insure a Classic Car Parked Outside?," the answer is almost always a resounding "no" when it comes to specialty classic car insurance. You might be forced into a standard auto policy, which will value your car at Actual Cash Value (ACV) rather than the crucial Agreed Value, leaving you severely underinsured.
- Increased Rates or Disqualification: The simple truth is, if your car isn't securely garaged, you're either looking at significantly elevated premiums (if you can even find a company willing to cover it) or a denial of coverage altogether. Insurers see these situations as directly contradicting the "pleasure use" or "limited use" clauses that help keep classic car rates low.
Professional Storage Facilities: A Mixed Bag
For collectors with multiple vehicles or those without adequate home garage space, professional storage facilities can seem like a viable option. However, their impact on rates can vary widely.
- Types of Facilities: These range from basic self-storage units to high-end, climate-controlled, secure collector car "condos."
- Basic Self-Storage: A standard, locked storage unit can be acceptable, but insurers will often want to know about the facility's overall security (gated access, surveillance, on-site management). If it's just a metal box with a padlock in a remote area, it might not be enough.
- Climate-Controlled, Secure Facilities: These are often ideal. Facilities designed specifically for classic or luxury vehicles typically offer climate control, 24/7 surveillance, restricted access, and sometimes even on-site maintenance. Many insurers, including Hagerty, view these very favorably. They offer peace of mind from environmental damage and theft, often leading to comparable rates to a secure home garage. These facilities are often listed among the Storage Options Specialty Insurers Accept.
- Costs and Benefits: While professional storage adds another expense to classic car ownership, the peace of mind and potentially favorable insurance rates can make it worthwhile. You're effectively outsourcing a significant portion of your risk mitigation to a professional entity. However, make sure the facility's security features are clearly communicated to your insurer, as not all facilities are created equal. The level of security directly influences how the insurer assesses the risk, which in turn affects your premiums.
Security Features That Can Lower Your Premiums
It’s not enough to just park your classic car in a garage; the level of security that garage provides plays a significant role in how your insurance rates are calculated. Insurers reward proactive measures that reduce the likelihood of theft or damage. Think of it as investing a little upfront in security to save on premiums and gain peace of mind in the long run.
Physical Security Enhancements
The physical barriers and deterrents you put in place around your classic car's storage spot are often the first line of defense, and insurers definitely take notice.
- Robust Locking Mechanisms: Upgrading from a standard padlock to heavy-duty deadbolts on garage entry doors or installing a secure, reinforced garage door (perhaps one that's insulated and resistant to forced entry) is a strong signal of commitment to security. For detached garages, ensuring all windows are locked and secured with grates or film can also help.
- Gated Access and Fencing: If your property has a secure, locked gate or robust fencing around the perimeter, this adds another layer of protection. It deters casual trespassers and makes it harder for potential thieves to access your garage or even survey the property unnoticed.
- Effective Lighting: Motion-sensor lighting around the garage and driveway can be surprisingly effective. Most criminals prefer to operate under the cover of darkness, and sudden, bright lights can send them scattering. It's a simple, cost-effective upgrade that boosts security.
- Surveillance Systems: Modern home security systems with cameras are more affordable and accessible than ever. High-definition cameras covering your garage entry points and the classic car itself can deter theft and vandalism, and crucially, provide evidence if an incident does occur. Make sure these systems are reliable and preferably connected to a monitoring service or accessible via your smartphone.
Advanced Anti-Theft Systems
Beyond physical barriers, technology offers powerful tools to protect your classic, and many insurers appreciate these sophisticated measures.
- GPS Tracking Devices: These are incredibly valuable for classics. If your car is stolen, a hidden GPS tracker can help law enforcement pinpoint its location, significantly increasing the chances of recovery. Many specialty insurers offer discounts for cars equipped with these devices, as they drastically reduce the potential payout for a total theft loss.
- Engine Immobilizers: An immobilizer prevents the engine from starting without the correct key or transponder. This makes hot-wiring virtually impossible, adding a strong layer of protection against theft. Many newer classics or restomods might already have these, but they can often be retrofitted to older models.
- Remote Monitoring and Alarms: Advanced alarm systems that alert your phone or a central monitoring station instantly if a breach occurs are excellent. Some systems can even monitor garage temperature or humidity, providing an early warning for environmental risks. Hagerty, for example, often highlights the benefits of comprehensive security systems when discussing How to Save on Classic Car Insurance.
Fire and Environmental Protection
Theft isn't the only risk. Fires, floods, and other environmental hazards pose a significant threat to classic cars. Taking steps to mitigate these risks can also positively influence your insurance rates.
- Fire Suppression Systems: Installing smoke detectors in your garage is a no-brainer. Even better, consider a dedicated fire suppression system, especially if you store flammable liquids or perform welding/fabrication work in the garage. These systems can drastically reduce damage in the event of a fire.
- Climate Control and Humidity Monitoring: For highly valuable or sensitive classics, maintaining a stable climate is crucial. Extreme temperature swings or high humidity can lead to rust, cracked dashboards, and deteriorating interiors. A climate-controlled garage, or at least a dehumidifier, demonstrates a commitment to preservation that insurers appreciate. This is particularly relevant for maintaining the "Agreed Value" of your vehicle, as discussed in How Agreed Value Affects Premiums.
- Flood Prevention: If your garage is in a flood-prone area, consider measures like elevated storage platforms or reinforced garage doors that can withstand water intrusion. Proactive measures against common environmental risks signal responsible ownership to your insurer, potentially leading to better rates and, more importantly, protecting your cherished vehicle.
How Specific Policy Types and Usage Affect Storage Requirements
It's not just what kind of storage you have, but also how you intend to use your classic car, and what kind of policy you're aiming for, that dictates storage requirements and, by extension, your insurance rates. Specialty classic car insurance isn't a one-size-fits-all product; it's tailored to the unique nature of collector vehicles and their owners.
Pleasure Use vs. Limited Use vs. Regular Use and Storage
Understanding the intended use of your classic car is paramount, as it directly correlates with storage expectations and insurance eligibility.
- Pleasure Use: This is the most common and ideal scenario for classic car insurance. It means your classic is used for leisurely drives, car shows, club events, and occasional errands, but not as a primary mode of transportation. Insurers assume such a vehicle will be meticulously cared for, driven sparingly, and most importantly, stored securely in a garage when not in use. This usage profile, combined with secure storage, is what allows specialty insurers to offer significantly lower premiums than standard auto policies. A classic under pleasure use is rarely exposed to the daily grind of traffic, parking lots, or inclement weather, thus dramatically reducing its risk profile. This is often covered under a "pleasure-use requirement," as detailed in Pleasure-Use Requirement Explained.
- Limited Use: Similar to pleasure use, limited use policies often come with annual mileage restrictions (e.g., 2,500, 5,000, or 7,500 miles per year). Again, the expectation is that the car is not a daily driver and spends most of its time safely stored. These mileage restrictions are a key factor in keeping rates low because reduced driving time directly translates to reduced exposure to accidents. Insurers view limited use as further evidence of careful, protective ownership, and the storage requirements remain stringent – a secure, enclosed garage is almost always a prerequisite. For a deeper dive, check out Classic Car Insurance Mileage Limits by State.
- Regular Use (Daily Driver): This is where classic car insurance deviates significantly. Most specialty classic car insurers, like Hagerty or Grundy, do not offer policies for vehicles used as daily drivers. Their entire business model is built on the low-risk profile of rarely driven, meticulously cared-for collector vehicles. If you intend to use your classic as a daily driver, you'll likely need a standard auto insurance policy, which will value your car at Actual Cash Value (depreciated value) rather than an Agreed Value, and your premiums will be considerably higher. The concept of Classic Car Insurance for a Daily Driver is usually handled by regular carriers, not specialty ones, and comes with a very different set of assumptions regarding storage and risk.
Restoration and Project Car Storage
Not all classics are road-ready show queens. Many are ongoing projects, barn finds, or vehicles undergoing extensive restoration. These cars have unique storage and coverage needs.
- Vehicle Under Construction Coverage: If you're knee-deep in a restoration, you can get specific coverage that protects the car, parts, and labor even when it's not drivable. The storage for these vehicles is still critical. Insurers expect project cars to be stored in a secure, enclosed workshop or garage. After all, if the parts are spread across your garage, those individual components need protection from theft and damage, too.
- Value Fluctuation: As a car undergoes restoration, its value typically increases. Your storage needs to reflect this rising value. A partially disassembled car in a secure, monitored garage is a much better risk than one sitting under a tarp in the backyard. Many policies, such as "Vehicle Under Construction Coverage," can be structured to allow for periodic adjustments to the Agreed Value as the restoration progresses. This ensures your investment is protected every step of the way, as discussed in Requirements to Insure a Car Under Restoration.
- Insuring Non-Running Classics: Even if your classic is a non-runner, sitting idle awaiting its turn in the shop, it still needs insurance. This "laid-up" or "storage-only" coverage still requires secure storage, typically an enclosed garage. While liability risk is minimal, comprehensive coverage (theft, fire, vandalism, natural disaster) is crucial. A policy for a non-running project car will still factor in its storage location when determining rates, ensuring the vehicle's long-term protection. For more, see Can You Insure a Classic Car You're Restoring.
Multi-Car Collections and Storage Solutions
For serious collectors with several classics, storage solutions often become more complex, but the core principles remain the same.
- Consolidated Storage: Many collectors choose to house their entire collection in one large, secure facility or an expanded home garage. This can be beneficial for insurance, as a single, highly secure location often qualifies for better rates or multi-vehicle discounts under a Multi-Car Collector Policy Requirements. Insurers appreciate the centralized risk management.
- Dedicated Collector Policies: Specialty insurers like Hagerty are experts in insuring collections. They understand that a collector might have a variety of vehicles, all requiring secure storage. These policies are often more flexible regarding the specifics of multiple storage locations, provided each location meets minimum security standards. For example, one car might be at home, another at a restoration shop, and a third at a climate-controlled storage facility – as long as each spot is secure, it can typically be covered under a unified policy.
- The "Daily Driver" Rule for Collections: Even with a collection, the rule about daily drivers usually holds. You'll need at least one other primary vehicle for everyday transportation insured under a standard policy. Your classics are then reserved for pleasure or limited use. This ensures the integrity of the classic car policy's risk profile, which heavily relies on the assumption of minimal, careful driving and secure, off-road storage.
What Happens If Your Storage Changes or Isn't Up to Snuff?
Life happens, and sometimes your storage situation changes, or you might realize your current setup isn't quite meeting the mark. What then? Ignoring these details can have serious consequences, ranging from policy cancellation to a denied claim when you need it most. Transparency and proactive communication with your insurer are key.
The Importance of Honesty and Disclosure
When you apply for classic car insurance, you'll be asked detailed questions about where your vehicle is stored. This isn't just busywork; it's a fundamental part of the underwriting process.
- Misrepresentation is a Big Deal: Intentionally misrepresenting your storage conditions (e.g., claiming it's garaged when it's consistently parked on the street) can be considered insurance fraud. At best, your policy could be canceled, and at worst, any future claims could be denied, leaving you on the hook for significant losses. Insurers often conduct spot checks or require photos of the storage location, especially for high-value vehicles.
- Claim Denial Risk: Imagine your classic, which you told your insurer was garaged, gets stolen from your driveway. When you file a claim, the insurer investigates and discovers the discrepancy. They could deny the claim based on a material misrepresentation, arguing that had they known the true storage conditions, they would have charged a different premium or not issued the policy at all. This scenario is a collector's worst nightmare.
- Validate Your Eligibility: Always be honest and confirm that your storage meets the Classic Car Insurance Eligibility Requirements of your chosen carrier. It's far better to pay a slightly higher premium for accurate coverage than to face a denied claim later.
Updating Your Policy When Storage Changes
Life is fluid, and your classic car's home might change. Whether you move, upgrade your garage, or temporarily store it elsewhere, your insurer needs to know.
- Moving Residences: If you move to a new home, even if it has a garage, you must inform your insurer immediately. The new address, the type of garage, and its security features are all relevant. Your rates might adjust up or down depending on the new location's risk profile and the garage's specifications.
- Garage Upgrades: If you install a new alarm system, add surveillance cameras, or reinforce your garage door, tell your insurer! These improvements can often lead to discounts, as they demonstrably reduce risk. It's a win-win: better security for your car and potentially lower premiums for you.
- Temporary Storage: If you're taking an extended vacation and storing your classic at a friend's secure garage, or if it's spending a few months at a restoration shop, communicate this. While short-term changes might not always require a policy update, clarity is always best, especially if the new location offers a different level of security. Some policies offer specific Storage Options Specialty Insurers Accept for temporary situations.
- Consequences of Not Updating: Failing to inform your insurer about a change in storage could again lead to issues at claim time. If your car is damaged or stolen from a location not listed on your policy, the insurer might have grounds to dispute or deny the claim.
Finding Solutions for Challenging Storage Situations
Not everyone has a pristine, multi-car garage. If your storage situation isn't ideal, don't despair, but be realistic and proactive.
- Utilize Professional Storage: If you lack a secure home garage, investing in a reputable, climate-controlled classic car storage facility might be your best bet. While it adds a monthly cost, it fulfills the insurer's requirements and provides superior protection for your vehicle.
- Enhance Existing Structures: Can your existing carport be converted into a secure, enclosed garage? Can you add a locking gate to your driveway? Explore options for upgrading what you have. Even modest improvements can make a difference.
- Communicate with Insurers: Don't assume. If your storage is unusual (e.g., an extremely secure barn on private property), discuss it openly with specialty insurers like Hagerty or Grundy. They are often more flexible and understanding of unique collector situations than standard carriers, provided the actual risk is low. They might offer specific Classic Car Insurance Rules by State for non-traditional storage.
- Consider a Storage-Only Policy: If your car is non-running, undergoing restoration, or simply laid up for an extended period, you can often get a "storage-only" or "laid-up" policy. This covers comprehensive risks (theft, fire, natural disaster) while the car is stationary and securely stored. This type of policy explicitly recognizes that the car isn't being driven and therefore needs specific, secure storage.
Practical Tips for Optimizing Your Classic Car Storage and Rates
Ensuring your classic car is stored properly isn't just about meeting insurance requirements; it's about safeguarding your investment and passion. By being proactive and strategic, you can not only secure favorable insurance rates but also ensure your cherished vehicle remains in top condition for years to come.
Documenting Your Storage Environment
Proof is power, especially when it comes to insurance. Having thorough documentation of your storage setup can streamline the quote process and reinforce your claim of responsible ownership.
- Photos and Videos: Take clear, well-lit photos and a video walkthrough of your garage or storage facility. Capture the exterior, showing locks, gates, and lighting, and then the interior, showcasing the car, security systems, and overall cleanliness. This visual evidence helps the insurer understand the environment your classic calls home.
- Security Feature Details: Keep records of any security upgrades, such as receipts for alarm systems, GPS trackers, or reinforced garage doors. Note the brands, installation dates, and any monitoring services you subscribe to. Many insurers will ask for specifics to apply potential discounts.
- Appraisal Support: When getting an appraisal for your classic car (which is often crucial for setting the Agreed Value), ensure the appraiser also documents the storage conditions. A professional appraisal often includes details about where the car is kept, further validating its protected status. This directly ties into How Appraisals Affect Classic Car Insurance Cost and the overall risk assessment.
Comparing Insurers' Storage Requirements
Not all classic car insurance companies are identical in their approach to storage. It pays to shop around and understand the nuances.
- Specialty Insurers vs. Standard Carriers: Specialty insurers like Hagerty, Grundy, American Collectors, and J.C. Taylor are specifically designed for classics. They typically have stricter storage requirements (almost always a locked garage) but offer superior coverage like Agreed Value and more favorable rates. Standard carriers might cover a classic under a regular auto policy, but often without Agreed Value and with higher premiums, regardless of storage, because they don't specialize in collector risks.
- Ask Specific Questions: When getting quotes, don't just state you have a garage. Ask: "What are your specific requirements for garage security?" "Do you offer discounts for alarm systems or GPS trackers?" "How do you view climate-controlled storage versus a standard home garage?" This level of detail can help you choose the best policy, as outlined in What to Look for in a Classic Car Policy.
- Understand Regional Differences: While less common for storage, sometimes state-specific regulations or regional risk factors can influence how insurers view certain storage types. For instance, an insurer might have particular insights into theft rates in a certain metropolitan area, impacting how they view a detached garage there.
Proactive Maintenance During Storage
While not directly about insurance policy details, maintaining your classic car during storage is crucial for preventing claims and preserving its value, which indirectly supports your insurance profile.
- Battery Tender: Use a battery tender to keep the battery charged. A dead battery can be a minor inconvenience or, if extreme, can cause electrical system issues that require repair.
- Tire Care: Inflate tires to proper pressure or slightly above to prevent flat spots during long-term storage. Consider tire cradles if the car will be static for many months.
- Fluid Checks and Changes: Ensure all fluids are at proper levels. For long-term storage, some owners change oil or add fuel stabilizers to prevent degradation.
- Pest Control: Mice, rats, and other critters love to nest in stored cars, chewing wires and destroying interiors. Use bait, traps, or repellents in your garage.
- Car Cover: A breathable, indoor car cover protects against dust, accidental scratches, and minor bumps, keeping your classic pristine.
- Regular Inspections: Even in storage, periodically check on your car. Look for leaks, signs of pests, or any changes in the environment. This diligence contributes to the long-term health and value of your classic, indirectly affirming to any insurer that this is a well-cared-for asset, ultimately affecting How Storage Affects Classic Car Eligibility for specialty coverage and its overall insurability.
| Storage Type | Typical Insurer Stance (Specialty) | Impact on Rates (Compared to Garaged) | Key Considerations |
|---|---|---|---|
| Private, Locked Garage | Ideal, often Required | Lowest, most favorable | Must be enclosed, secure. Home security, alarms, surveillance can further reduce rates. Essential for Agreed Value coverage. |
| Professional Facility | Often Highly Favorable | Similar to home garage (or slightly higher) | Varies greatly by facility's security (gated, surveillance, climate control). Communicate details to insurer. Good alternative for those without home garage space. |
| Carport | Rarely Acceptable | Significantly Higher (if covered) | Open to elements, theft, vandalism. Most specialty insurers will decline. If covered, expect higher premiums and limited coverage. |
| Driveway/Street | Almost Universally Unacceptable | Not typically offered by specialty insurers | Extremely high risk of theft, vandalism, accidental damage. Disqualifies from most classic policies. You'd likely need standard auto insurance with ACV, severely underinsuring your classic. |
| Workshop (Mid-Resto) | Acceptable with specific coverage | Varies, depends on security & project stage | Requires "Vehicle Under Construction" or "Restoration Coverage". Secure, enclosed workshop is crucial. Rates reflect parts value, labor, and potential for additional claims during work. |
Ultimately, how you store your classic car is a reflection of your commitment to its preservation. Insurers recognize this commitment and reward it with specialized policies and more affordable premiums. By prioritizing secure, enclosed storage and maintaining open communication with your insurance provider, you can ensure your classic is protected, both physically and financially.
Disclaimer
Please note that this article provides general information about classic car insurance and storage. Insurance requirements, coverage options, and rates can vary significantly based on your specific vehicle, location, personal circumstances, and the insurance provider. Always consult with a qualified insurance professional to discuss your individual needs and to obtain personalized quotes and advice.