Why Agreed Value Matters for Classics
It's a familiar heartache for many classic car enthusiasts: you’ve poured your heart, soul, and hard-earned money into restoring that vintage beauty, only to find that traditional auto insurance policies simply don't understand its true worth. They often see a 50-year-old car, not a meticulously restored piece of history. This guide is here to explain why "agreed value" coverage is the absolute cornerstone for any classic car owner, ensuring your passion and investment are truly protected.
The Frustration with Traditional Auto Insurance and Classics
When you've spent countless hours in the garage, hunting down period-correct parts, or entrusted your pride and joy to a skilled restoration shop, the last thing you want to worry about is an insurance policy that devalues your efforts. Unfortunately, standard auto insurance policies are designed for modern vehicles, and their valuation methods can be incredibly disheartening for classic car owners.
The Pitfalls of Actual Cash Value ACV
Most everyday car insurance policies operate on what's called Actual Cash Value (ACV). This means that in the event of a total loss, the insurer pays out what the car was worth at the time of the loss, factoring in depreciation. For a modern car, this makes sense; a five-year-old Honda Civic is worth less than a brand-new one. The value drops steadily from the moment it leaves the lot.
However, apply this logic to a classic car, and you quickly see the problem. Imagine your meticulously restored 1965 Ford Mustang, a car you've poured $40,000 into, is involved in an unfortunate accident. If your policy is ACV, the adjuster might look up the "blue book" value for a 1965 Mustang in fair condition – which could be a fraction of what you've invested, let alone its true market value as a show-quality vehicle. You could be staring down a payout that doesn't even cover a quarter of your restoration costs, let alone the intrinsic value of your beloved pony car. This system simply doesn't recognize the appreciating nature of collector vehicles or the blood, sweat, and tears that go into them, leaving you severely underinsured and utterly frustrated.
Why Stated Value Isn't Much Better
Sometimes, a standard insurer might offer "stated value" coverage as an alternative to ACV, trying to bridge the gap for classic car owners. On the surface, it sounds better: you "state" a value for your car, and the insurer acknowledges it. However, the critical caveat is usually hidden in the fine print: the insurer may pay up to this stated amount, but they still reserve the right to pay out the actual cash value or fair market value at the time of the loss, whichever is less.
This creates a false sense of security. You might believe your 1970 Chevrolet Chevelle SS is covered for $75,000 because you "stated" that amount, but if an incident occurs, the insurer can still conduct their own valuation and pay you significantly less if they determine the market value or ACV is lower. This leaves the classic car owner in a precarious position, having paid premiums for a higher stated value only to be shortchanged when it matters most. It’s a common trap that many new collectors fall into, not realizing the significant difference between stated value and truly binding agreed value coverage. For a deeper dive into these options, you might want to read about Agreed Value vs Stated Value vs Actual Cash Value.
Understanding Agreed Value: The Collector's Best Friend
This is where "agreed value" coverage shines like a perfectly polished chrome bumper. It's the gold standard for classic, antique, and collector cars, and it's fundamentally different from anything offered by a typical auto insurance policy.
What "Agreed Value" Truly Means
Agreed value means that you and your insurance provider agree on a specific, fixed dollar amount for your classic car at the beginning of your policy term. This amount is the guaranteed payout you will receive if your vehicle is deemed a total loss, regardless of market fluctuations or depreciation. It’s a promise, written into your policy, that both parties commit to. There's no negotiation after a loss, no arguments about "blue book" values, and no surprise deductions for depreciation.
This approach acknowledges that classic cars are not mere transportation; they are investments, artifacts, and often, extensions of their owners' personalities. Companies specializing in classic car insurance, such as Hagerty or American Collectors Insurance, understand this distinction implicitly. They recognize that a lovingly maintained 1957 Chevrolet Bel Air or a rare 1963 Split-Window Corvette holds a value far beyond what any standard depreciation schedule could ever calculate. This pre-determined value provides unparalleled peace of mind, knowing that your financial and emotional investment is genuinely secured. To learn more about this specific type of coverage, check out Agreed Value Coverage Explained.
The Process of Determining Your Classic's Agreed Value
Establishing an agreed value for your classic car typically involves a collaborative process with your specialty insurer. It's not just a number you pull out of thin air; it's a carefully considered figure backed by evidence. The most common way to arrive at this figure is through a professional appraisal. An experienced classic car appraiser will examine your vehicle's condition, originality, restoration quality, provenance, and rarity to determine its fair market value. They’ll look at auction results, private sales data, and other market indicators specific to your make and model.
Beyond a formal appraisal, you'll also provide comprehensive documentation. This includes high-quality photographs from all angles, detailed records of any restoration work, receipts for significant parts or upgrades, and information about the car's history, awards, or unique features. Specialty insurers like Hagerty have extensive databases and expert valuation teams that can assist in this process, sometimes even offering valuation tools to help you determine a reasonable starting point. This ensures that the agreed value accurately reflects your car's true worth in the collector market. Understanding How Agreed Value Is Determined is key to a smooth process.
The Tangible Benefits of Agreed Value Coverage
The advantages of agreed value coverage extend far beyond simply having a number on paper. They translate into real, tangible benefits that protect your passion and simplify potentially stressful situations.
Protecting Your Investment and Passion
When you purchase a classic car, whether it’s a barn find you meticulously brought back to life or a pristine example you acquired at auction, it's more than just metal and rubber; it's an investment of both capital and emotion. Agreed value coverage directly protects this investment. If your cherished 1969 Camaro is stolen or completely destroyed in a fire, an agreed value policy ensures you receive the agreed-upon amount, allowing you to either replace the vehicle with one of comparable quality or recoup your financial outlay.
This means that all those hours spent restoring the engine, finding that elusive trim piece, or perfecting the paint job are financially recognized. It covers the rising costs of classic car parts and specialized labor, ensuring that your unique vehicle's value is truly understood. For instance, if you have substantial Restoration Coverage for Classic Cars, the agreed value can reflect these ongoing improvements, giving you peace of mind that your evolving project is continuously protected. It's about preserving not just the car, but the memories and the passion tied to it.
Streamlined Claims Process and Predictable Payouts
One of the most significant, yet often overlooked, benefits of agreed value coverage is the clarity and efficiency it brings to the claims process. In the unfortunate event of a total loss, there's no haggling, no protracted negotiations with an adjuster who might not grasp the nuances of the classic car market. The value has already been established and agreed upon by both you and the insurer upfront.
This pre-determined payout dramatically reduces stress during an already difficult time. You know exactly what to expect, and the process moves much more quickly than with a standard ACV policy where every aspect of the car’s worth might be disputed. This predictability is invaluable, especially for unique vehicles where market comparisons can be subjective and challenging. With agreed value, the focus shifts from debating worth to processing your claim, allowing you to move forward with replacing your vehicle or managing your recovery without added financial uncertainty.
Key Considerations and Best Practices with Agreed Value
While agreed value is the superior choice for classic car insurance, it's not a "set it and forget it" solution. To maintain optimal protection, there are a few important practices to follow.
Regular Valuation Updates and Documentation
The classic car market is dynamic. Values for certain models can skyrocket, while others might hold steady. If your car appreciates significantly, or if you undertake further restoration work that adds to its value, your original agreed value might become outdated. It's crucial to regularly review and update your agreed value with your insurer, typically on an annual basis or after major improvements. Keep meticulous records of all enhancements, significant repairs, or rare parts acquired, complete with receipts and "before and after" photographs.
For instance, if you install a period-correct, numbers-matching engine that took years to find and costs tens of thousands of dollars, that clearly impacts your car's value. Without updating your agreed value and providing documentation, your policy might not cover that added investment in the event of a total loss. Many specialty insurers, like Hagerty, provide resources and expertise to help collectors track market trends and advise on when an update or a new appraisal might be beneficial. This proactive approach ensures your coverage always aligns with your car's current market standing. This is also How Agreed Value Affects Premiums over time.
Choosing the Right Specialty Insurer
Not all insurance providers are created equal when it comes to classic cars. While some mainstream insurers might offer a nod toward classic car coverage, their understanding and policy structures often fall short compared to true specialty insurers. These dedicated providers live and breathe classic cars; they have expert staff, claims adjusters who are enthusiasts themselves, and a deep knowledge of the collector market.
Brands like Hagerty, Grundy, American Collectors Insurance, and J.C. Taylor are well-known names in the classic car community for a reason. They offer policies specifically tailored to the unique needs of collectors, with features like agreed value, Restoration Coverage for Classic Cars, Spare Parts Coverage Explained, and even Inflation Guard Coverage Explained to automatically increase your agreed value over time to keep pace with market appreciation. These specialized companies understand that your 1967 Mustang isn't just a car; it's a passion. Comparing quotes and policies from these dedicated providers is essential to ensure you get the comprehensive protection your classic deserves. If you're looking for options, consider exploring Best Classic Car Insurance Companies.
Agreed Value vs. Other Valuation Methods: A Clear Comparison
To fully appreciate why agreed value is paramount, it’s helpful to see it in stark contrast to the alternatives that frequently lead to collector heartbreak.
Why Stated Value and ACV Fall Short for Collectibles
The fundamental flaw with Actual Cash Value (ACV) for classic cars is its reliance on depreciation. Classics, by their very nature, often appreciate, or at least hold their value better than new cars. ACV completely ignores the restoration costs, the rarity of parts, and the unique appeal that makes a classic car valuable. It treats a 1969 Dodge Charger R/T, which could be worth well over $100,000, like any other aging vehicle, drastically undervaluing it. You end up paying for a policy that offers minimal real protection for your investment.
Stated value, while seeming like a step up, still carries significant risk. It gives the insurer an "out" to pay less than the stated amount if they determine the market value is lower. This means you could be insuring a 1980s Porsche 911 for $60,000, only for the insurer to value it at $45,000 after an accident, leaving you with a substantial financial gap. For the classic car owner, these options don't provide the financial security needed to replace a unique vehicle or recover a substantial investment. They are, in essence, designed for a different kind of asset.
The Importance of a "Guaranteed" Agreed Value
While "agreed value" is generally the term used, some elite policies or specific insurers might use "guaranteed value." This term often reinforces the absolute certainty of the payout, sometimes even specifying that the full amount will be paid without a deductible in the event of a total loss. While the distinction can be subtle and largely depends on the specific policy wording, the core principle remains the same: a pre-determined, locked-in payout.
The importance of this guarantee cannot be overstated. It eliminates all guesswork and potential disputes at the time of a loss. Whether your car is a rare Duesenberg or a beloved family heirloom like a vintage Volkswagen Beetle, knowing that its unique value is explicitly guaranteed in your policy provides unparalleled peace of mind. It’s this certainty that makes agreed value coverage not just an option, but an essential requirement for any serious classic car owner. When you're ready to explore options, remember to ask about how the agreed value is handled; for example, a Hagerty Classic Car Insurance Review might give you insights into their specific offerings.
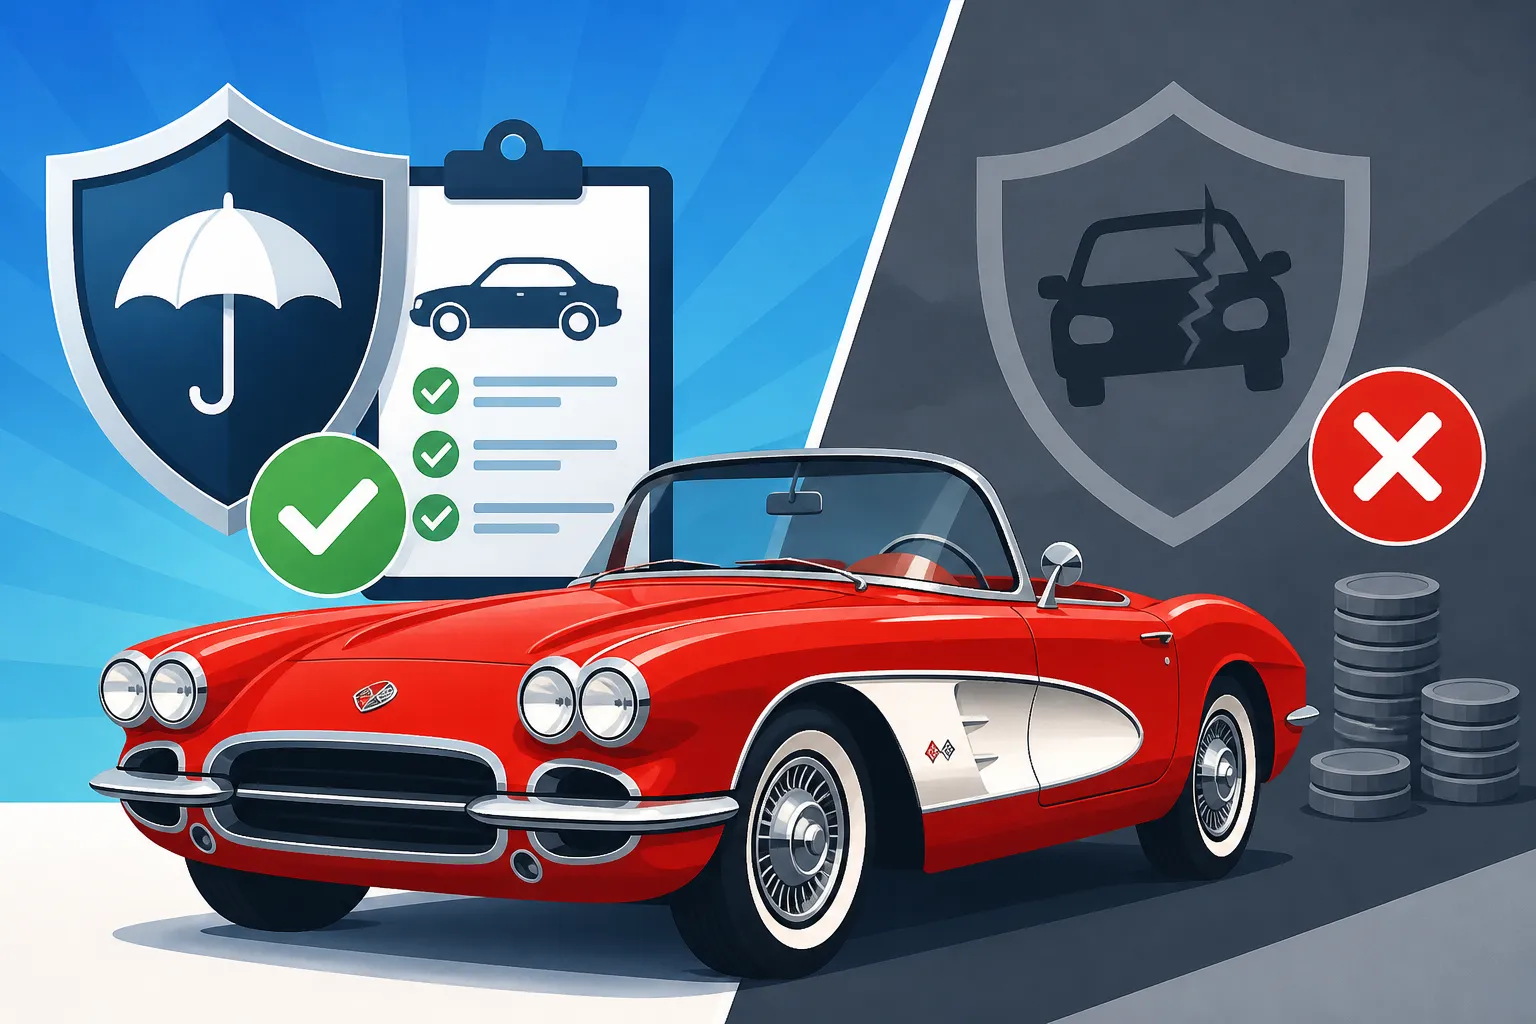
Here's a quick comparison of these valuation methods:
| Feature | Actual Cash Value (ACV) | Stated Value | Agreed Value |
|---|---|---|---|
| How Value is Determined | Original cost minus depreciation | Amount proposed by owner, subject to insurer's review at loss | Fixed amount agreed upon by owner and insurer before loss |
| Payout in Total Loss | Current market value minus depreciation (insurer decides) | Up to stated amount, but often capped at ACV or market value | Guaranteed payout of the exact agreed amount |
| For Classic Cars | Poor fit; devalues unique/restored vehicles | Risky; provides false security, can lead to underpayment | Ideal fit; protects investment and passion |
| Claims Process | Often involves negotiation and dispute | Potential for negotiation and lower payout | Straightforward, predictable payout |
| Cost | Generally lower premium | Mid-range premium | Higher premium (reflects true coverage) |
Disclaimer
The information provided in this article is for general informational purposes only and does not constitute financial, insurance, or legal advice. Classic car insurance policies can vary significantly between providers and depend on individual circumstances. It is crucial to consult with a qualified insurance professional to discuss your specific needs and obtain tailored advice. Always review your policy documents thoroughly to understand your coverage.