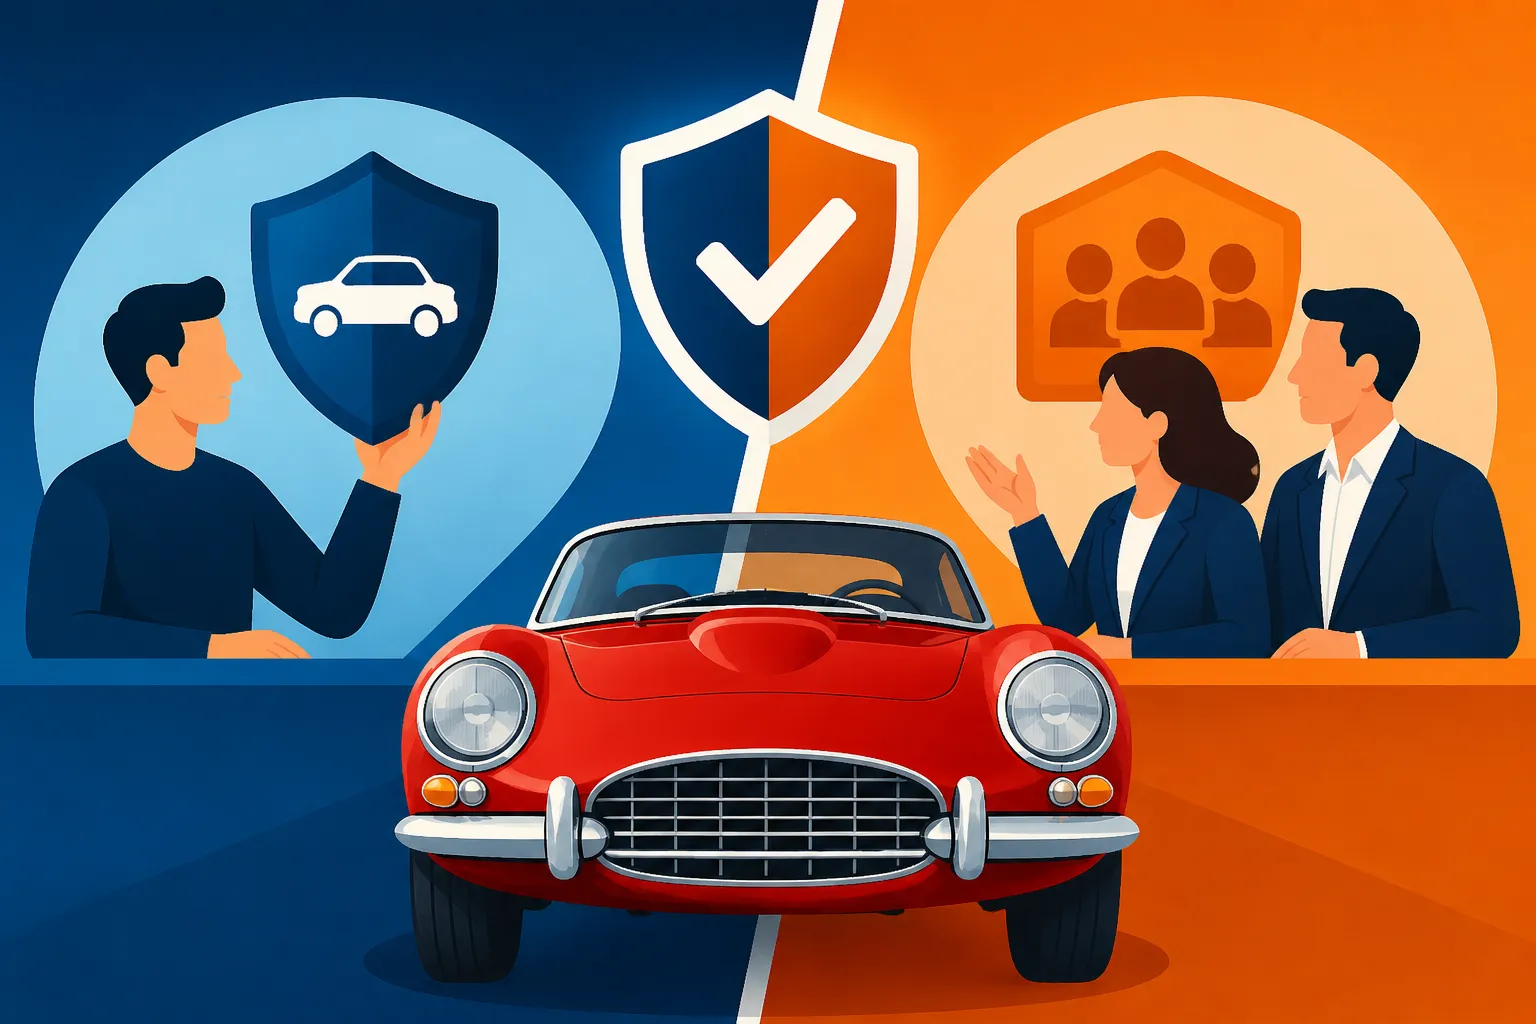
Direct vs Agency Classic Car Insurers
So, you're deep into the classic car hobby, maybe you've just acquired a new gem, or perhaps you're simply reviewing your existing coverage. The thought of insuring your cherished classic can be a minefield, especially when trying to figure out if you should go straight to a specialty insurer or work with an agent. It's a common dilemma, and one that often leaves collectors scratching their heads. This comprehensive guide will meticulously break down the differences between direct classic car insurers and agency-based options, helping you understand which path might be the best fit for your unique needs and your prized vehicle.
Understanding Direct Classic Car Insurers
Direct classic car insurers are companies that sell their policies directly to consumers without using an intermediary like an independent agent or broker. They handle everything from sales and customer service to underwriting and claims in-house. This streamlined approach can often appeal to collectors who prefer a more direct line of communication with their insurance provider.
How Direct Insurers Operate
When you interact with a direct classic car insurer, you're typically dealing with their own employees. This means you might get a quote through their website, speak with a representative on their dedicated phone line, or use their mobile app. The entire process, from getting an initial estimate to purchasing and managing your policy, is managed by the company itself. For instance, a well-known name in the classic car insurance world, Hagerty, primarily operates on this direct-to-consumer model. You can often get an instant quote online, tailor your coverage, and even file claims directly through their platforms.
This operational structure allows direct insurers to maintain tight control over their processes and messaging. They develop specialized platforms and training for their staff, ensuring that everyone you speak with is well-versed in the nuances of classic car insurance. This can be particularly reassuring when you have specific questions about Agreed Value coverage or the unique requirements of your vintage ride. They essentially cut out the "middleman," aiming to make the experience as efficient and focused as possible for the collector.
Pros of Going Direct
One of the most appealing aspects of working with a direct classic car insurer is the potential for a more streamlined and efficient experience. You're dealing directly with the source, which can mean quicker quotes and, often, a more consistent service experience since all representatives are employed and trained by the same company. Many collectors appreciate the ease of navigating a dedicated website or app designed specifically for their needs.
Another significant advantage is the deep specialization many direct insurers offer. Since they only focus on classic and collector vehicles, their staff tend to be highly knowledgeable about the unique aspects of insuring these cars, such as Agreed Value Coverage Explained. They understand the value of a meticulously restored engine, the rarity of original parts, and the specific usage patterns of collector cars, leading to more accurate underwriting and potentially better-tailored policies. This specialization often translates into a superior claims process as well, as their adjusters are familiar with classic car repair costs and reputable restoration shops. For instance, if you own a rare 1960s muscle car, a direct insurer might have specific experts who can properly assess its value and ensure fair compensation in the event of a loss.
Cons of Going Direct
While direct insurers offer many benefits, there can be some drawbacks. One potential issue is the limited range of options. When you go directly to one insurer, you are only seeing the policies and rates that they offer. This means you might miss out on potentially better deals or unique coverage packages available from other carriers that you haven't researched. It places the burden of comparison shopping entirely on your shoulders, requiring you to visit multiple websites or make numerous phone calls to get a comprehensive view of the market.
Furthermore, direct insurers might not always offer the same level of personalized, one-on-one consultation that an independent agent can provide. If you have a complex collection, multiple unique vehicles, or specific situations that don't fit neatly into an online form, you might find yourself navigating various departments or explaining your situation repeatedly to different representatives. While many direct insurers strive for excellent customer service, the relationship can sometimes feel more transactional compared to the ongoing support an agent might provide. It's a bit like buying a car directly from the manufacturer versus having a local dealership salesperson who knows your preferences.
Exploring Agency-Based Classic Car Insurers
Agency-based classic car insurers, on the other hand, rely on a network of independent insurance agents or brokers to sell their policies. These agents act as intermediaries, working on behalf of their clients to find the best insurance solutions from multiple carriers. This model introduces a human element and a layer of advocacy that many collectors find invaluable.
The Role of Independent Agents
Independent insurance agents are essentially your personal guides in the insurance landscape. Unlike captive agents who work for a single company (like a State Farm or Allstate agent), independent agents aren't tied to one insurer. They have relationships with multiple classic car insurance providers, ranging from large national carriers to smaller, niche specialty companies. Their primary role is to understand your specific needs, assess the unique characteristics of your classic vehicle or collection, and then shop the market on your behalf.
This means an independent agent can present you with quotes from several different companies, such as American Collectors Insurance, Grundy, or even some local carriers that might offer specialized regional coverage. They can compare and contrast policy features, explain the fine print, and help you understand how different options like Spare Parts Coverage Explained or Inflation Guard Coverage Explained might benefit your situation. They act as a trusted advisor, simplifying the often-confusing process of selecting the right coverage and helping you navigate How to Compare Classic Car Insurance Quotes.
Benefits of Working with an Agency
The most significant benefit of an agency is the personalized service and expertise an independent agent brings to the table. They can sit down with you, understand your passion for classics, and truly tailor a policy to your needs. This is particularly valuable for collectors with complex situations, such as a highly modified vehicle, a car under restoration, or a multi-car collection that requires specific considerations for Multi-Car Collector Policy Requirements. An agent can be a single point of contact for all your classic car insurance needs, simplifying policy management and making it easier to make adjustments as your collection evolves.
Moreover, independent agents act as advocates when it comes to claims. Should you ever need to file a claim, your agent can help you navigate the process, communicate with the insurance company on your behalf, and ensure that your interests are protected. They often have established relationships with claims departments, which can potentially expedite the process or help resolve disputes. This level of support can be incredibly comforting during what can often be a stressful time, offering peace of mind beyond just the policy itself. They know the ins and outs of various insurers' claims procedures, which can be a huge asset when you need your beloved classic repaired.
Potential Drawbacks of Agencies
While agents offer a wealth of benefits, there are a few potential drawbacks to consider. One might be the perception of added cost. While an agent's services are typically paid through commissions from the insurance companies (meaning you don't directly pay them a separate fee), some worry that this might indirectly lead to higher premiums. However, a good agent's ability to shop around and find competitive rates often offsets any such concern, potentially saving you money in the long run by securing discounts you might not have known about.
Another consideration is the potential for varying levels of expertise among agents. While many independent agents are highly knowledgeable in classic car insurance, some might specialize more in standard auto or home insurance. It’s crucial to find an agent who has a dedicated focus on collector vehicles and understands their unique valuation, usage, and storage requirements. If you choose an agent without this specific expertise, you might not get the most optimized coverage or the best advice. It's important to do your homework and seek out agents who genuinely understand the classic car market and the nuances of Classic Car Insurance vs Regular Insurance: What's Required.
Key Differences: Direct vs. Agency at a Glance
The choice between a direct insurer and an agency often boils down to your personal preference for how you interact with service providers and the complexity of your insurance needs. It's not necessarily about one being inherently "better" than the other, but rather which model aligns more closely with what you're looking for in an insurance partner.
The Personal Touch vs. Streamlined Process
With a direct insurer, the experience is often designed for efficiency and self-service. You can get quotes, manage policies, and even initiate claims online or via a mobile app at your convenience. This can be fantastic for those who prefer digital interactions and have a straightforward classic car to insure. The process is streamlined, standardized, and often very quick. For many, the ability to compare Classic Car Insurance Quotes with a few clicks on a website like Hagerty's is a huge plus.
An agency, however, offers a much more personal touch. You build a relationship with a specific agent who gets to know you, your collection, and your long-term plans. This human connection can be invaluable, especially when complex questions arise or if you prefer discussing your options face-to-face or with a dedicated point of contact. Your agent becomes an ongoing resource, offering advice and support over the years. They can also provide context and explanations that might be harder to glean from an online portal, making the process of How to Buy Classic Car Insurance feel less daunting.
Policy Customization and Flexibility
Direct insurers, while specialized, often have a more defined set of policy offerings. While you can certainly customize your coverage, the options might be within a framework set by that single company. They are experts in their products, but they don't have the breadth of options from competing carriers. This isn't to say their policies aren't comprehensive, but rather that your choices are limited to what that one entity provides.
Independent agents, by contrast, offer unparalleled flexibility and customization. Because they work with multiple carriers, they can mix and match policies, find niche coverages, and essentially build a bespoke insurance portfolio for your classic cars. If one company doesn't offer the exact restoration coverage you need, an agent might know another that does. This flexibility can be crucial for unique vehicles, highly specialized collections, or collectors with very specific demands for their Classic Car Insurance Add-Ons and Endorsements. They can truly scour the market to find the perfect fit, rather than you having to fit into a pre-existing mold.
Cost Implications and Comparison
When it comes to cost, there's a common misconception that direct insurers are always cheaper because they cut out the middleman. While this can sometimes be true, it's not a universal rule. Direct insurers invest heavily in marketing and technology, and these costs are factored into premiums. An independent agent, with access to multiple carriers, can often find competitive rates and discounts that you might not uncover on your own. They might even be able to bundle your classic car policy with other insurance needs, potentially leading to overall savings.
The key is that both models can offer competitive pricing, but the way you get to that pricing differs significantly. With a direct insurer, you're doing the legwork of comparing yourself. With an agent, they do that comparison shopping for you, providing you with a curated selection of options. Ultimately, the "cheapest" option isn't always the "best" when it comes to classic car insurance, as proper coverage and an appropriate Agreed Value are far more critical than shaving a few dollars off the premium. It's often worth paying a little more for specialized coverage that truly protects your investment. This is often highlighted in articles discussing How Much Does Classic Car Insurance Cost and Why Classic Car Insurance Is Cheaper Than Regular.
Here's a quick comparison of the two approaches:
| Feature | Direct Classic Car Insurers | Agency-Based Classic Car Insurers |
|---|---|---|
| Provider | Single insurance company | Multiple insurance companies |
| Sales Channel | Online, phone, company representatives | Independent agents/brokers |
| Service Model | Streamlined, self-service, digital-first | Personalized, advisory, relationship-based |
| Policy Options | Limited to one company's offerings | Wide range from multiple carriers |
| Comparison Shopping | You do the research and compare | Agent shops and compares for you |
| Claims Advocacy | You interact directly with claims department | Agent can assist and advocate on your behalf |
| Expertise | Deep expertise in their own products | Broad expertise across various carrier products & market |
| Relationship | Transactional with company, less personal | Personal relationship with a dedicated agent |
When Each Option Makes Sense for Your Collection
The best choice for your classic car insurance truly depends on your specific circumstances, your comfort level with technology, and the nature of your collection. There isn't a one-size-fits-all answer, which is why understanding the nuances of both direct and agency models is so important.
Ideal Scenarios for Direct Insurers
Going with a direct classic car insurer can be an excellent choice if you appreciate efficiency and a straightforward process. If you own a single classic car, perhaps a relatively common model like a vintage Ford Mustang or a Chevrolet Corvette, and your usage is fairly standard (limited mileage, pleasure driving, garage stored), a direct insurer might be perfectly suited for you. You're comfortable with online research, comparing quotes yourself, and managing your policy through web portals or apps. You know exactly what kind of coverage you need, such as specific Classic Car Insurance Eligibility Requirements, and you're confident in your ability to communicate directly with the insurer if issues arise.
Furthermore, if you are looking for specific types of coverage that a well-known direct specialty insurer like Hagerty is famous for, such as their robust Agreed Value Coverage Explained or roadside assistance tailored for classics, going direct might be your best bet to access those specialized benefits efficiently. Many first-time collectors also find direct insurers appealing due to their user-friendly platforms and clear explanations of coverage options, making the entry into classic car insurance less intimidating.
Ideal Scenarios for Agency Insurers
An agency-based approach shines when your classic car insurance needs are more complex or when you highly value personalized guidance. If you own a diverse collection of classics—perhaps a vintage muscle car, a pre-war antique, and a modern collectible—an independent agent can help you craft a comprehensive policy that addresses the unique needs of each vehicle. This is especially true for cars with significant modifications, rare imported models, or vehicles that are still undergoing restoration, where specific Restoration Coverage for Classic Cars or Requirements for Insuring a Modified Classic are essential.
If you're a busy individual who prefers to delegate the legwork of comparison shopping and policy management, an agent can be an invaluable asset. They handle the details, ensure you're getting competitive rates from multiple carriers, and act as your advocate if you ever need to file a claim. For collectors who value building a long-term relationship with an insurance professional who understands the ever-evolving classic car market and can offer expert advice on What to Look for in a Classic Car Policy, an independent agent is often the superior choice. This is also beneficial for those who want a single point of contact for all their insurance, including their daily drivers and home, allowing for potential multi-policy discounts.
Hybrid Approaches and Considerations
It's also worth noting that the lines can sometimes blur, and a hybrid approach might even be possible or beneficial. You might start by getting a few direct quotes online from prominent specialty insurers to get a baseline understanding of pricing and coverage options. Many collectors use the convenient online tools offered by companies like Hagerty to quickly gauge potential costs for their vehicles.
Once you have this initial information, you could then take those quotes to an independent agent. An experienced agent might be able to find even better deals, suggest alternative coverages you hadn't considered, or identify potential gaps in the direct policies. They can leverage their relationships with multiple carriers to either beat the direct quotes or offer added value through enhanced coverage or service. This way, you benefit from the efficiency of direct quoting while still gaining the advocacy and broader market access of an independent agent. Ultimately, the goal is always to secure the most comprehensive and cost-effective coverage that truly protects your cherished classic, and a careful blend of both strategies can sometimes lead to the optimal outcome.
Making Your Decision: Practical Steps and Considerations
Choosing the right classic car insurer is a critical decision that impacts the security of your investment and your peace of mind. It’s not a choice to be rushed; rather, it requires thoughtful consideration of your personal preferences and the specific needs of your vehicle.
Researching and Gathering Quotes
Regardless of whether you lean towards a direct insurer or an agency, your first step should always be thorough research. Start by understanding what makes a car a classic, antique, or vintage to ensure you're looking for the right type of insurance. You can find more information on When a Car Qualifies as Classic or When a Car Qualifies as Antique. Then, begin by identifying reputable specialty classic car insurers. For direct options, companies like Hagerty are usually at the top of the list. Visit their websites, explore their coverage options, and utilize their online quote tools. Gather at least three to five quotes to give you a good benchmark for pricing and coverage details.
If you're considering an agency, seek out independent agents in your area who specifically advertise expertise in classic or collector car insurance. Ask for referrals from other collectors in your local car club or online forums. When you meet with an agent, be prepared to discuss the specifics of your vehicle(s)—its make, model, year, condition, modifications, storage, and how you use it. Provide them with the quotes you've already gathered from direct insurers; this can help them demonstrate their value by finding comparable or superior policies. Remember, the goal isn't just the lowest price, but the best value, which includes comprehensive coverage and excellent service.
Evaluating Customer Service and Claims
The quality of customer service and the claims process can make or break your insurance experience, especially with a beloved classic. When interacting with direct insurers, pay close attention to how quickly your inquiries are answered, the clarity of their communication, and the helpfulness of their representatives. Look for online reviews and ratings specifically pertaining to their classic car insurance divisions. A smooth, knowledgeable experience during the quote process often translates to better service down the line.
For agency-based options, discuss the agent's involvement in the claims process. Will they be your point person, or will you be directed to a separate claims department? Ask about their track record with helping clients through claims and what kind of support you can expect. Research reviews of the specific carriers they recommend, focusing on how those companies handle classic car claims. Knowing that you have a proactive advocate in your corner if disaster strikes can provide immense peace of mind. Remember, the ability to get your classic repaired properly, often with specialized parts and expertise, is paramount. You'll want to review aspects like Classic Car Insurance Companies Compared and Classic Car Insurers with the Best Claims Service.
Long-Term Relationship and Policy Management
Think about the long game. Classic car ownership is often a lifelong passion, and your insurance needs might evolve over time. You might acquire new vehicles, embark on restoration projects, or your car's value could appreciate significantly. Consider which model will best support these changes.
With a direct insurer, you'll manage these updates through their online systems or customer service. This can be efficient, but it requires you to be proactive in reviewing your policy and communicating changes. For instance, you'll need to know How to Update Coverage After Restoration or How to Increase Agreed Value at Renewal. With an independent agent, they often provide proactive reminders for policy reviews, help you adjust your Agreed Value as your car appreciates, and streamline adding new vehicles to your collection. They can become a trusted partner who understands your evolving needs and ensures your classic car insurance keeps pace with your hobby. This long-term relationship can be a significant benefit, especially for those with growing collections or cars that are continually gaining value.
Disclaimer
Please remember that insurance policies and requirements can vary significantly by state and individual circumstances. This information is intended for general guidance only and does not constitute professional insurance advice. Always consult with a qualified insurance professional to discuss your specific needs and ensure you have appropriate coverage for your classic vehicle.