Classic Car Insurance Requirements Explained
Stepping into the world of classic cars is a dream for many, but it often comes with a heap of questions, especially when it comes to insurance. It's not like insuring your everyday commuter, and trying to figure out the specific classic car insurance requirements can feel like navigating a winding, unpaved backroad in the dark. Many enthusiasts find themselves frustrated, wondering why their beloved vintage ride doesn't fit neatly into a standard auto policy. This guide aims to shine a bright light on those often-confusing requirements, detailing what you need to know to properly protect your prized possession.
Understanding What Makes a Car "Classic" for Insurance
The very first hurdle many classic car owners face is the definition itself. What one person calls a classic, an insurance company might call an old car. The distinction isn't just semantics; it's critical to whether your vehicle qualifies for a specialized policy, which typically offers superior coverage and often lower premiums than standard auto insurance. This isn't about age alone; it's a combination of factors that define a vehicle's collectibility and its intended use.
Age and Eligibility Criteria
When we talk about "classic," "antique," or "vintage," these terms often get thrown around interchangeably, but they have distinct meanings in the insurance world. Generally, a car needs to be at least 20 to 25 years old to be considered a classic, though this can vary slightly by insurer. For instance, some companies might start considering a car "collectible" as young as 15 years old, especially if it's a specific high-performance model or a rare import. On the other hand, an "antique" designation usually kicks in around 45 years old or older, with "vintage" often falling in the 20-30 year range, though again, these aren't hard and fast rules across the board. The key is that it's no longer just transportation; it's a piece of history.
It's important to remember that these age brackets are a starting point. Simply being old doesn't automatically qualify a vehicle for classic car insurance. Many insurers are also starting to recognize "youngtimers" – vehicles from the 1980s and 1990s that are rapidly gaining collector status. For example, a pristine 1989 BMW M3 or a well-preserved 1995 Toyota Supra might qualify even if they just barely cross the 20-year mark, whereas a beat-up 1998 Honda Civic, while 25 years old, likely wouldn't. Each insurer has its own specific guidelines for Classic Car Insurance Age Requirements for Vehicles, so it’s always best to check with a specialist.
Condition and Valuation Requirements
Beyond age, the condition of your vehicle is paramount. Classic car insurers are looking for cars that are well-maintained, restored, or in excellent original condition. They want to see a commitment from the owner to preserving the vehicle's integrity and value. A car that's rusting away in a field, even if it's a desirable model, typically won't qualify for a specialty policy unless it's explicitly covered as a "project car" or "car under restoration" with a specific plan. This focus on condition directly relates to how the insurer assesses risk and, crucially, how they determine the vehicle's insured value.
This ties into one of the most significant benefits of classic car insurance: agreed value coverage. Unlike standard auto policies that pay out "actual cash value" (which factors in depreciation), an agreed value policy means you and the insurer agree on the car's value before the policy begins. This value is then what you would receive in the event of a total loss, removing the guesswork and potential disappointment. To establish this value, especially for higher-end or heavily restored vehicles, an appraisal is often required, confirming the car's condition, modifications, and overall worth. This ensures both you and the insurer are on the same page regarding your investment.
Vehicle Type and Collectibility
Not all vehicles are created equal in the eyes of a classic car insurer. While common cars like a 1965 Ford Mustang or a 1957 Chevrolet Bel Air are almost universally accepted, what about a classic truck or a classic motorcycle? Most specialty insurers, including Hagerty, offer policies for a wide range of collector vehicles, from antique tractors and military vehicles to vintage motorcycles and classic trucks. The key factor here is collectibility – whether the vehicle has appreciating value or is considered special.
Beyond traditional cars and trucks, many policies also cover modified cars, hot rods, street rods, and even kit cars or replicas, provided they meet certain safety and build quality standards. The more unique your vehicle, the more specific the requirements might become. For instance, a highly customized restomod might require detailed documentation of all modifications and their associated costs. It's about demonstrating that your vehicle is a special interest item, cherished and maintained, rather than just an old mode of transport.
The "Why" Behind Specialty Classic Car Insurance Requirements
It might seem like a lot of hoops to jump through, but these specific requirements aren't arbitrary. They exist for very good reasons that ultimately benefit you, the collector. Standard insurance policies are designed for daily drivers, which face different risks and valuation challenges. Specialty classic car insurance, on the other hand, is crafted to protect the unique nature and value of your cherished automobile, often resulting in more comprehensive coverage at a more affordable price.
Protecting Your Investment with Agreed Value
One of the most compelling reasons for specialty classic car insurance requirements revolves around the concept of agreed value. When you insure a standard car, the policy typically uses "actual cash value" (ACV) to determine payouts after an accident. ACV accounts for depreciation, meaning your 10-year-old sedan, even if it was $30,000 new, might only be valued at a fraction of that today. For a classic car, this approach is disastrous; a meticulously restored 1969 Camaro isn't depreciating, it's often appreciating!
Specialty insurers understand this. They require documentation and sometimes appraisals to establish an Agreed Value Coverage Explained upfront. This means that if your prized possession is ever totaled or stolen, you'll receive the amount you both agreed upon, not some depreciated value. This is a huge piece of mind, ensuring that your financial investment in restoration, maintenance, and acquisition is truly protected. Without these requirements, insurers couldn't offer such a tailored and advantageous valuation method.
Lower Risk Profile of Collector Cars
The stringent requirements for classic car insurance also stem from the inherently lower risk profile of these vehicles compared to regular cars. Classic cars are typically driven fewer miles, used for pleasure only, and stored securely. This reduced exposure to typical road hazards, daily commutes, and inclement weather translates to fewer claims and less severe damage, which in turn leads to lower premiums. Insurers need to enforce these usage and storage requirements to maintain that lower risk profile.
Think about it: a car driven only on sunny weekends to a local car show or a Sunday cruise is far less likely to be involved in an accident than a car battling rush-hour traffic every day. These reduced risks allow specialty insurers to offer policies that are often significantly cheaper than what you'd pay for standard coverage on a comparable vehicle, despite the higher agreed value. The requirements are a way for the insurer to verify that your vehicle truly falls into this low-risk category.
Tailored Coverage Options
The "why" also extends to the specialized coverage options that classic car policies provide. Standard auto insurance simply doesn't offer things like coverage for spare parts, inflation guard, or even specific coverage for a vehicle under restoration. Classic car owners often accumulate valuable parts, invest significant sums in restoration, and see their vehicle's value increase over time. Specialty policies are designed to address these unique needs, but these unique needs also come with unique requirements.
For example, to get Restoration Coverage for Classic Cars, an insurer might require a detailed plan of your restoration project, including estimated costs and timelines. For spare parts coverage, they may ask for an itemized list and valuation of those parts. These requirements ensure that the coverage you receive is precisely tailored to your specific situation, protecting every aspect of your classic car hobby. Without understanding your unique needs through these requirements, insurers couldn't offer such a bespoke and comprehensive policy.
Common Driver and Household Requirements
It's not just your classic car that needs to meet certain criteria; you, the owner, and other drivers in your household also play a significant role in eligibility. Specialty classic car insurers are looking for responsible custodians who will treat their collector vehicles with the care and respect they deserve. This often means having a clean driving record and ensuring the classic isn't your only mode of transport.
Primary Driver Experience and Record
Classic car insurers typically look for drivers with a solid track record behind the wheel. They prefer to insure individuals who demonstrate responsible driving habits, which usually translates to a clean driving record free of major accidents, serious moving violations, or DUI/DWI convictions. This isn't to say a single minor speeding ticket will disqualify you, but a pattern of risky behavior will likely make it difficult to obtain a specialty policy. The logic is simple: a responsible driver is less likely to put a valuable classic car at risk.
Some insurers also have minimum age requirements for the primary driver. While there isn't a universal age, many prefer drivers to be at least 25 years old. This isn't an ageist policy, but rather reflects statistical data that suggests older, more experienced drivers typically have fewer accidents. However, some progressive insurers are starting to offer Classic Car Insurance for Teenagers in the Household or young collectors, often with specific stipulations or higher premiums. It's always worth checking with a specialist insurer like American Collectors Insurance, as their policies can be more flexible than standard carriers.
Other Household Drivers and Their Eligibility
It's crucial to be upfront about anyone else in your household who might drive the classic car. Most classic car policies require all licensed drivers in the household to be listed on the policy, even if they only occasionally drive the vehicle. Just like the primary driver, these additional drivers will need to meet the insurer's eligibility criteria regarding driving record and experience. If your teenage son has a lead foot and multiple infractions, it could impact your ability to get a policy or significantly increase the premium, even if he only plans to drive the classic once a year.
In some cases, if a household member doesn't meet the eligibility requirements, they might need to be specifically excluded from the policy. This means that if they were to drive the car and get into an accident, there would be no coverage. It's a tough conversation, but transparency with your insurer is key to ensuring proper coverage and avoiding claims disputes. Always discuss your household's driving situation thoroughly when applying for Household Driver Requirements Explained.
Maintaining a Separate Daily Driver
One of the most consistent requirements for classic car insurance is that the vehicle not be used as a primary or daily driver. This is foundational to the lower risk profile we discussed earlier. Insurers expect you to have a separate, modern vehicle for your everyday transportation needs. This helps reinforce that the classic car is truly a collector's item, used for pleasure, shows, or occasional cruises, rather than for commuting, grocery runs, or regular errands.
This requirement is often referred to as the Daily Driver Requirement Explained. It's designed to limit the classic's exposure to common road hazards and excessive mileage. While some specialty insurers are starting to offer more flexible options for a Classic Car Insurance for a Daily Driver, these policies usually come with different stipulations, such as higher mileage limits or slightly different premium structures. For the vast majority of classic policies, having a dedicated daily driver is a non-negotiable requirement.
Storage and Usage Restrictions
The way you store and use your classic car is just as important as its age and your driving record. These requirements directly influence the risk assessment and are a cornerstone of specialty classic car insurance. They ensure that your prized possession is kept safe and only used in ways that align with its collectible status.
Secure Storage Location Requirements
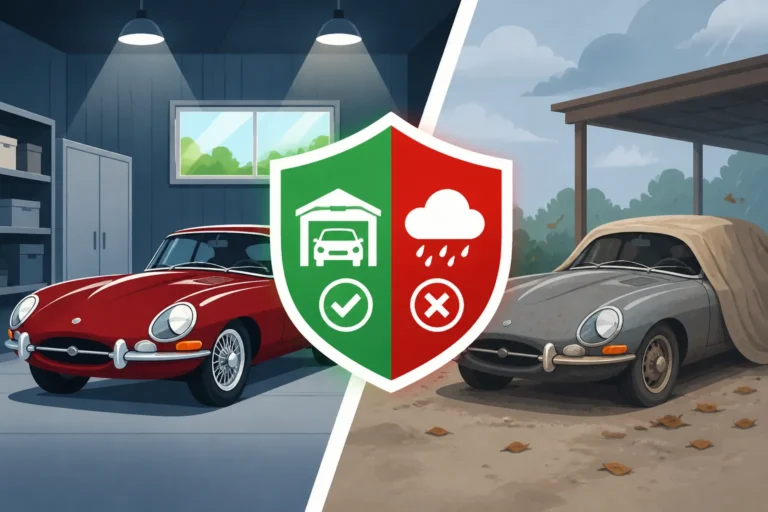
Classic car insurers nearly universally require that your vehicle be stored in a secure, enclosed, and locked facility when not in use. This isn't just a suggestion; it's a fundamental requirement for most policies. Think of a private garage, a dedicated storage unit, or another secure building. The goal is to protect the vehicle from theft, vandalism, and environmental damage. A car parked indefinitely on the street or under an open carport might struggle to meet these criteria, as it's exposed to significantly higher risks.
Many policies specifically look for a "Garage Storage Requirement for Classic Cars." This means a fully enclosed, private garage, preferably attached to your home or a dedicated secure off-site facility. The rationale is clear: a locked garage provides a much greater deterrent to theft and offers better protection against weather elements like hail, intense sun, or heavy rain. While some insurers might offer limited coverage for cars stored in a carport or even outside in specific, low-risk scenarios, it's rare and often comes with higher premiums or stricter conditions. Always confirm your storage solution with your insurer to ensure compliance.
Limited Mileage and Usage Guidelines
Another critical requirement for classic car insurance is strict adherence to mileage limits and usage guidelines. These vehicles are meant for pleasure driving, car shows, club events, and occasional tours, not daily commuting. Most specialty policies come with annual mileage caps, which can range anywhere from 1,000 to 7,500 miles per year, with 2,500 to 5,000 miles being quite common. This limits the exposure of your classic to road hazards and wear and tear, contributing to the lower premiums.
These mileage limits are usually tiered, allowing you to choose a plan that best fits your driving habits. For example, if you only take your classic out for a few local shows and Sunday drives, a 1,000-mile limit might be perfect. If you plan to attend more distant events or enjoy longer scenic drives, a 3,000 or 5,000-mile limit might be more appropriate. Companies like Grundy offer flexible mileage programs, but the underlying principle remains: these are not meant to be high-mileage vehicles. It’s essential to be realistic about your intended use to avoid issues if you need to file a claim. You can explore options like Unlimited Mileage Classic Car Insurance Explained but be aware that such flexibility often comes with specific conditions or a higher premium.
Pleasure Use vs. Regular Driving
The distinction between "pleasure use" and "regular driving" is paramount in classic car insurance. "Pleasure use" typically means occasional driving for enjoyment, such as going to car shows, club events, parades, or scenic drives. It explicitly excludes using the vehicle for commuting to work, running routine errands, or any commercial purposes. This Pleasure-Use Requirement Explained is a core tenet of specialty policies.
If you violate this pleasure-use clause and use your classic for daily transportation, your insurer could deny a claim, cancel your policy, or reclassify it under a standard auto policy, which would likely result in significantly higher premiums and different coverage terms. The intent is to insure a hobby, a passion, not a transportation workhorse. Be honest about your intentions and choose a policy that matches your actual usage to avoid any nasty surprises down the road.
Valuation and Appraisal Necessities
Getting the value right is one of the most vital aspects of insuring a classic car. Unlike a modern car whose value is easily found in Kelley Blue Book, a classic's worth can be highly subjective, depending on its condition, originality, rarity, and market demand. This is where specialty insurers really differentiate themselves, and why certain valuation requirements are in place.
The Role of Appraisals in Agreed Value Policies
For many high-value or unique classic cars, an independent appraisal is a common requirement to establish the "agreed value." This isn't just a formality; it's a professional, third-party assessment of your vehicle's condition, originality, and market value. A certified appraiser will meticulously inspect your car, take photos, and review any documentation you provide, such as restoration receipts or provenance. Their report then serves as the objective basis for the agreed value between you and the insurer.
This appraisal process is crucial for both parties. For you, it ensures that in the event of a total loss, you receive the full, accurate value of your investment. For the insurer, it provides a clear, documented understanding of the risk they are taking on. While some insurers, like Hagerty, might use their extensive internal valuation databases for certain common classics up to a specific value without requiring an appraisal, for truly rare, custom, or high-value vehicles, an appraisal is almost always necessary. Understanding How Classic Car Appraisals Work for Insurance is key to securing appropriate coverage.
Documenting Modifications and Restoration Costs
Many classic cars aren't in their original factory state. Owners often undertake extensive restorations, add performance modifications, or customize their vehicles. If your classic has undergone such work, meticulously documenting these changes and their associated costs is an absolute requirement for proper insurance coverage. This documentation helps to justify the increased value of the car beyond its stock condition.
Keep detailed records of all receipts for parts and labor, before-and-after photographs, and any professional invoices from body shops, mechanics, or custom builders. This isn't just about proving the expense; it's about demonstrating the quality of the work and how it enhances the vehicle's value. Without this paper trail, it can be incredibly difficult to convince an insurer that your custom engine build or concours-level paint job significantly increased the car's worth, potentially leading to underinsurance if a claim arises. Be proactive in documenting every dollar and hour spent.
Regularly Updating Your Vehicle's Value
The classic car market can be dynamic, with values fluctuating based on trends, auction results, and economic conditions. What your car was worth three years ago might not be what it's worth today, especially for appreciating assets. Because of this, specialty insurers often recommend, and sometimes require, that you periodically review and update your vehicle's agreed value. This typically happens at renewal time or if you've made significant improvements to the car.
Failing to update your agreed value could mean you're underinsured if your car's market value has significantly increased. Conversely, if values have dipped (though less common for true classics), you might be paying for more coverage than necessary. Staying in touch with your insurer and providing updated documentation or appraisals ensures that your policy accurately reflects your vehicle's current worth. This ongoing partnership helps protect your investment over the long haul.
State-Specific Registration and Insurance Mandates
While classic car insurance offers unique benefits, it doesn't exempt you from basic state laws. Every state has its own rules regarding vehicle registration, emissions, and minimum liability insurance. Navigating these mandates while also securing specialty classic car insurance can sometimes feel like a puzzle, but it’s a necessary step to ensure your classic is street-legal.
Minimum Liability Requirements for Classics
Just like any other vehicle on the road, your classic car must meet your state's minimum liability insurance requirements. These requirements mandate a certain amount of coverage for bodily injury and property damage you might cause to others in an at-fault accident. While specialty classic car policies excel in protecting your car with agreed value, they still include the necessary liability coverage to comply with state laws. You can check your state's Department of Motor Vehicles or equivalent agency for specific figures.
For instance, Classic Car Liability Requirements by State can vary wildly. In Florida, the minimum is 10/20/10 (meaning $10,000 for bodily injury per person, $20,000 for bodily injury per accident, and $10,000 for property damage). In Maine, it's 50/100/25. It's crucial to ensure your classic car policy's liability limits meet or exceed these state minimums. While these minimums are often quite low, many collectors opt for higher liability limits to better protect their assets, as an at-fault accident could lead to significant financial repercussions beyond those minimums.
Antique and Historic Plate Regulations
Many states offer special license plates for classic, antique, or historic vehicles. These plates often come with reduced registration fees, and in some cases, exemptions from certain regulations. However, obtaining these plates also comes with its own set of rules, which can vary greatly from state to state. For example, in Virginia, a vehicle must be at least 25 years old to qualify for antique plates, and its use is typically restricted to exhibitions, club activities, parades, and occasional pleasure driving, much like classic car insurance stipulations.
Understanding these Historic Vehicle Registration Explained is vital, as they often align with the usage restrictions of your classic car insurance. Some states may even prohibit a vehicle with antique plates from being used for daily transportation or commuting. Always consult your state's DMV or equivalent agency to understand the specific age requirements, usage limitations, and application process for these special plates. They can be a great way to showcase your car's heritage and save on registration costs, but only if you adhere to their rules.
Emissions and Safety Inspection Exemptions
Another significant benefit of owning a classic car in many states is the exemption from modern emissions and safety inspections. Given that many older vehicles were not designed with catalytic converters or advanced safety features, requiring them to pass contemporary tests would be unreasonable, if not impossible. States recognize this and often provide waivers for vehicles of a certain age, allowing them to remain on the road.
These Classic Car Emissions Test Exemptions by State can save collectors both time and money. For instance, in California, vehicles manufactured before the 1976 model year are generally exempt from smog checks. In New York, vehicles over 25 years old are typically exempt from safety and emissions inspections. However, these exemptions are not universal. It’s crucial to verify your specific state and vehicle year against current regulations. Relying on an outdated understanding could lead to registration issues or fines, so always double-check with your local DMV.
Key Coverage Requirements to Consider for Your Classic
Beyond the fundamental requirements for eligibility, understanding the different types of coverage available and what your classic truly needs is essential. This isn't just about meeting mandates; it's about comprehensive protection for your valuable asset, which often goes far beyond what a standard auto policy offers.
Beyond Basic Liability: Comprehensive and Collision
While liability insurance is legally required, for a classic car, it's really just the bare minimum. To truly protect your investment, you absolutely need comprehensive and collision coverage. Collision coverage pays for damage to your classic car resulting from an accident, regardless of who is at fault. Comprehensive coverage, on the other hand, protects against non-collision incidents such as theft, vandalism, fire, natural disasters (like hail or floods), falling objects, and animal impacts.
Given the irreplaceable nature of many classic car parts and the significant investment in restoration, these coverages are not just recommended, they are practically essential. Imagine a tree falling on your perfectly restored 1967 Mustang or it being stolen from a show – without comprehensive coverage, you'd be out of luck. Most specialty classic car policies bundle these coverages, ensuring that your agreed value is protected against a wide array of potential damages and losses. This goes to the heart of why Do Classic Cars Need Full Coverage is almost always the answer.
Specialty Coverages: Spare Parts and Restoration
One of the most valuable aspects of specialty classic car insurance policies is their ability to cover items and situations unique to the collector car hobby. For example, many collectors accumulate a stash of rare or expensive spare parts, from engine components to trim pieces. Standard auto policies wouldn't touch these. However, most classic car insurers offer Spare Parts Coverage Explained as an add-on, protecting your inventory of valuable components.
Similarly, if you're in the midst of a restoration project, your car's value increases incrementally as work progresses. Restoration Coverage for Classic Cars is designed for this exact scenario. It allows you to adjust the agreed value of your vehicle as you invest more into it, ensuring that all your hard work and financial outlay are protected at every stage of the build. This type of coverage is invaluable for project car owners, as it recognizes the evolving value of a car under construction.
Roadside Assistance and Trip Interruption
Even the most meticulously maintained classic can have an off day. A flat tire, an unexpected electrical gremlin, or a fuel pump issue can leave you stranded. Standard roadside assistance often isn't equipped to handle classics, especially those requiring flatbed towing to prevent damage to the drivetrain or chassis. Specialty classic car policies recognize this and often include or offer specialized roadside assistance.
This typically means guaranteed flatbed towing to the nearest qualified repair shop, ensuring your classic is transported safely and without further damage. Beyond towing, some policies also offer Trip Interruption Coverage for Classic Cars. Imagine you're on a multi-day tour and your classic breaks down hundreds of miles from home. This coverage can help with lodging, rental car, or transportation expenses while your car is being repaired, allowing you to continue your journey or get back home without excessive out-of-pocket costs. These add-ons provide practical peace of mind that your standard auto policy simply cannot match.
Navigating the Application Process and Avoiding Pitfalls
Applying for classic car insurance isn't overly complicated, but it does require attention to detail and a clear understanding of what information your chosen insurer needs. Being prepared and knowing common reasons for denial can save you a lot of hassle and ensure a smooth journey to protecting your classic.
Gathering Necessary Documentation
To get a classic car insurance quote and eventually a policy, you'll need to gather several pieces of documentation. This typically includes:
- Vehicle Information: Make, model, year, VIN, current odometer reading.
- Ownership Proof: Title or registration.
- Agreed Value Support: Photos of the vehicle (interior, exterior, engine bay, trunk), any recent appraisals, receipts for restoration work or significant modifications.
- Driver Information: Driver's licenses for all household drivers, driving history reports.
- Storage Details: Description and photos of your secure storage facility.
- Daily Driver Proof: Proof of insurance for your primary, daily-use vehicle.
The more detailed and organized you are with your documentation, the smoother the application process will be. For example, a specialist like Hagerty will appreciate clear, well-lit photos that showcase your car's condition, which helps them accurately assess its value and risk. Being thorough here prevents delays and ensures you get an accurate quote tailored to your specific classic. Learning Documents Needed for a Classic Car Quote can streamline this process.
Common Reasons for Classic Car Insurance Denial
While classic car insurance is accessible to many, there are common reasons why an application might be denied. Knowing these can help you avoid them:
- Poor Driving Record: A history of multiple accidents, serious traffic violations, or DUIs/DWIs for any household driver is a major red flag. Specialty insurers are looking for responsible drivers.
- Lack of a Daily Driver: If the classic is your only vehicle, it will likely be denied, as specialty policies are not for primary transportation.
- Inadequate Storage: Storing the car on the street, in an open driveway, or in an unsecured carport typically won't meet the requirements.
- Excessive Mileage: If you plan to drive the car more than the policy's annual mileage limit allows, you might be denied, or offered a different type of policy.
- Condition Issues: A car in very poor, neglected, or unsafe condition that doesn't qualify as a "project car" might not be accepted.
- Age of Vehicle: If the car doesn't meet the minimum age requirement for "classic" or "collectible" status by that particular insurer.
Understanding What Disqualifies a Car from Classic Insurance is crucial. If you fall into one of these categories, it's best to address the issue before applying, or seek out an insurer that offers more flexible options, though they might come with different premium structures.
Choosing the Right Specialty Insurer
Not all insurance companies are created equal when it comes to classic cars. While your standard auto insurer might offer "classic car" coverage, it's often a rider on a standard policy and may not provide the true agreed value and specialized benefits of a dedicated classic car insurer. Companies that specialize in collector vehicles, such as Hagerty, Grundy, American Collectors Insurance, and J.C. Taylor, live and breathe classic cars.
These specialist companies have deep knowledge of the collector car market, dedicated claims departments that understand classic car repair, and a range of policies tailored to specific needs, from cars under restoration to multi-vehicle collections. They understand the nuances of agreed value, spare parts, and pleasure use, and their staff are often enthusiasts themselves. When you're looking to How to Choose Classic Car Insurance, always prioritize a specialty insurer over a general one, as they are best equipped to protect your unique investment.
Disclaimer
Please note that this guide provides general information about classic car insurance requirements. Insurance policies and regulations vary by state, insurer, and individual circumstances. It is crucial to consult with a qualified insurance professional and review specific policy documents to understand the exact terms, conditions, and coverage that apply to your classic vehicle. This content is not intended as legal, financial, or insurance advice.