How Garage Type Affects Your Premium
It’s a common scenario: you’ve finally acquired that dream classic car, polished it to a mirror sheen, and now you’re looking into insurance. You expect questions about mileage, value, and your driving history, but then the insurer asks about your garage. Your garage? It might seem like a strange detail, but how and where you store your cherished classic is a huge factor for specialty insurers and can significantly impact your classic car insurance premium. This guide will walk you through exactly why your garage type matters, how it influences your rates, and what you can do to ensure your vintage ride is both safe and affordably insured.
Understanding Why Your Garage Matters to Insurers
When it comes to insuring a classic car, the rules are often quite different from a standard daily driver. Insurers specializing in classics, like Hagerty, understand that these vehicles aren't just transportation; they're investments, passions, and often, works of art. Because of this, they assess risk through a unique lens, and the environment where the car spends most of its time is a top-tier consideration.
The Core Principle: Risk Assessment
Think about it from an insurer's perspective. Their primary job is to evaluate the likelihood of something bad happening to your car and how much it might cost them. A classic car, especially one with significant value, represents a substantial risk for theft, vandalism, and accidental damage. The place where you keep it, particularly overnight and for extended periods, directly mitigates or exacerbates those risks.
If your beautiful 1967 Mustang convertible is tucked away in a sturdy, locked garage, the chances of it being stolen or damaged by a stray tree branch are vastly lower than if it's parked out on the street. Insurers use this information to determine your risk profile. The lower the perceived risk, the lower your premium. This isn't just about protecting the car from outright theft; it's also about safeguarding it from everyday perils like weather exposure, accidental bumps, or even curious onlookers who might cause minor damage. Every little bit of protection translates into a better risk assessment for the insurer, and ultimately, a more favorable rate for you. This is why knowing what affects classic car insurance rates is so crucial.
Protecting Your Investment from the Elements
Beyond theft, classic cars are particularly vulnerable to environmental factors. Unlike modern vehicles with advanced paint protection and rust inhibitors, older cars often lack these defenses. Exposure to the elements can cause rapid deterioration, leading to costly repairs that diminish the car’s value.
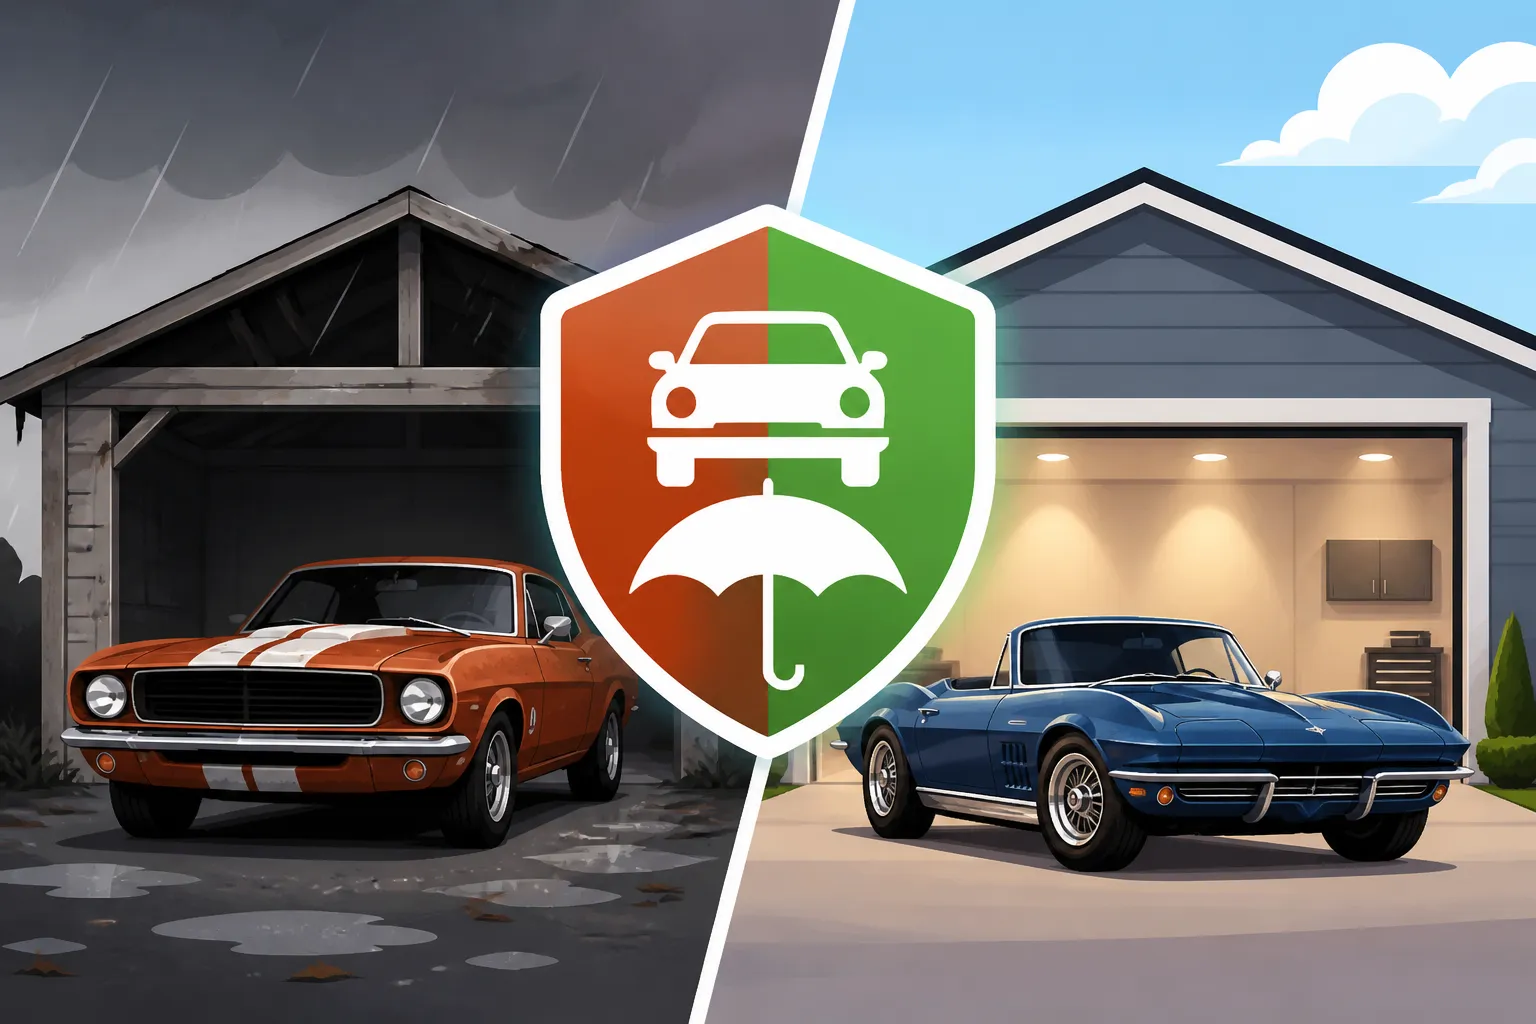
Rain, snow, hail, intense sun, and even humidity can take a severe toll on classic paint, chrome, interiors, and mechanical components. A solid, enclosed garage provides a crucial barrier against these natural threats. It protects the car from direct rainfall that can lead to rust, from harsh UV rays that fade paint and crack dashboards, and from hail that can cause devastating body damage. Imagine a classic car caught in a hailstorm while parked in an uncovered driveway versus one safe inside a garage. The difference in potential damage, and therefore the insurance payout, is immense. Insurers know this, and they factor it into their calculations. A secure garage is not just a preference; for many classic car insurance policies, it’s a non-negotiable requirement. Many policies even outline specific Garage Storage Requirement for Classic Cars.
Different Garage Types and Their Impact on Premiums
Not all garages are created equal in the eyes of a classic car insurer. The construction, security features, and even proximity to your home can all play a role in how much you pay. Understanding these distinctions is key to getting the best possible rate.
Attached vs. Detached Garages
There's a subtle but significant difference in how insurers view attached versus detached garages. An attached garage is physically connected to your home, often sharing a wall and having direct entry into your living space. This setup generally offers a higher level of security. Why? Because it’s harder for a thief to operate unnoticed when they’re essentially inside your home's perimeter. There's also usually less distance for them to travel with tools or for getting the car out, increasing the chances of being detected by you or your family. The fact that the garage is part of your main residence often means it benefits from the same security systems (alarms, surveillance) as your home.
A detached garage, on the other hand, is a separate structure on your property. While it still offers good protection, it might be perceived as slightly less secure than an attached one. There's usually a greater distance from the main house, which could give a determined thief more time and privacy to break in and get a car out before anyone inside the house notices. However, a well-built, securely locked detached garage with its own alarm system can still qualify for excellent rates. The key here is the level of security and how easily accessible it is to unauthorized individuals. If your detached garage is fortified like a bunker, an insurer will likely view it very favorably.
Secure vs. Less Secure Storage Options
Beyond the attached/detached distinction, the overall security of the storage space is paramount. A "secure" garage, in the eyes of an insurer, typically means a fully enclosed, private structure with a locking door. The more robust the locking mechanism, the better. Think about a heavy-duty, solid wood or metal garage door with a sturdy deadbolt or an automated opener that locks electronically. Even better are garages with additional security measures like alarm systems connected to a monitoring service, motion-sensor lighting, or even surveillance cameras. These features actively deter theft and vandalism, signaling to the insurer that you're serious about protecting your asset.
In contrast, a less secure storage option might include a garage with a flimsy door, a broken lock, or one that's easily accessible from a public thoroughfare. If your classic is just behind a residential garage door that's routinely left open or has a faulty lock, that immediately flags a higher risk. This is where companies like Hagerty really focus their inquiries – they want to know the specifics of how your car is housed. You'd be surprised how many collectors overlook these seemingly minor details, only to find their premiums are higher than anticipated. It’s a good idea to compare different Classic Car Insurance Requirements Explained before settling on a policy, as storage can be a key differentiator.
Carports and Outdoor Storage: The Premium Spike
This is where things get tricky and often more expensive. If your classic car is regularly stored under a carport or, worse, completely outdoors in a driveway or on the street, expect your classic car insurance premium to be significantly higher, if you can even get a policy at all. Many specialty classic car insurers will flat-out refuse to cover a classic car that isn't stored in a secure, enclosed garage.
Why such a drastic difference? A carport offers minimal protection. It shields the car from direct overhead rain and sun, but it provides absolutely no security against theft or vandalism. The vehicle is openly visible and easily accessible to anyone walking by. This dramatically increases the risk of both opportunistic theft (e.g., someone breaking a window to grab items, or even stealing the car if keys are accessible) and damage from severe weather like wind-blown debris, side-driving rain, or hail.
Outdoor storage, like a driveway or street parking, is the highest risk scenario imaginable for a classic. The car is fully exposed to all elements, every passerby, and every potential thief. The chance of damage from accidents (another car backing into it), vandalism, or natural disasters is exponentially higher. For many insurers, it signals a lack of care or commitment to protecting the vehicle, making them incredibly wary. If you’re wondering, "Can you insure a classic car parked outside?", the answer is usually no with a specialty insurer, or yes, but at a premium so high it negates the benefit of a classic policy. If you must store your car outside, you might need to look into a standard auto policy, which will value your car at Actual Cash Value (depreciated value) rather than an Agreed Value Coverage Explained typical for classics.
Here’s a simplified breakdown of how storage types generally influence classic car insurance premiums:
| Storage Type | Security Level | Environmental Protection | Typical Premium Impact | Insurer Acceptance |
|---|---|---|---|---|
| Attached Garage | High (part of home) | Excellent | Lowest Risk, Lowest Rate | Widely Accepted |
| Detached Secure Garage | High (with good locks/alarms) | Excellent | Low Risk, Low Rate | Widely Accepted |
| Shared/Community Garage | Moderate (varies by security) | Good | Moderate Risk, Moderate Rate | Varies (often requires specific security) |
| Carport | Low (open sides) | Partial (overhead only) | High Risk, Higher Rate | Often Rejected / Limited |
| Outdoor Parking (Driveway/Street) | Very Low (fully exposed) | None | Very High Risk, Highest Rate | Rarely Accepted / Major Carriers Only (ACV) |
How to Potentially Lower Your Premium Based on Storage
Even if you already have a garage, there are steps you can take to make it even more appealing to insurers and potentially shave some dollars off your premium. It's all about demonstrating a proactive approach to protecting your classic.
Enhancing Garage Security
Upgrading your garage security is often the most impactful way to lower your classic car insurance cost. Insurers love to see that you've invested in keeping your vehicle safe. Start with the basics:
- Robust Locks: Ensure your garage door has a strong, functioning lock. If it's an older manual door, consider adding a deadbolt or an internal lock. For automatic doors, verify the opener's security features and consider smart garage door openers that let you monitor and control access remotely.
- Alarm Systems: Installing an alarm system in your garage, ideally one that’s integrated with your home security system or independently monitored, is a huge plus. This provides an immediate deterrent and alerts authorities quickly in case of a break-in.
- Lighting: Motion-sensor lights outside and inside your garage can deter potential thieves. Good lighting eliminates dark corners where someone might try to operate unnoticed.
- Cameras: Security cameras, visible or hidden, can provide peace of mind and crucial evidence if something goes wrong. Many modern systems offer remote viewing via smartphone apps.
When you're getting a How to Get a Classic Car Insurance Quote, be sure to highlight all these security features. Provide details about the type of locks, alarm system, and monitoring service you use. This information helps the underwriter understand that your car is genuinely well-protected, leading to a better assessment of your risk and potentially a lower rate.
Documenting Your Storage Solution
Don't just tell your insurer about your secure garage; show them! Comprehensive documentation can go a long way in validating your claims and reinforcing your commitment to protection.
Take clear, well-lit photos of your garage, both inside and out. Show the sturdy construction, the locking mechanisms on the doors, any alarm system keypads or sensors, and surveillance cameras. If you have a dedicated classic car lift or special storage equipment, photograph that too – it shows a professional approach to care. Some collectors even go as far as documenting their entire collection and storage setup with a professional appraisal, which can be invaluable for insurance purposes.
Beyond photos, keep records of any security system installations, professional alarm monitoring contracts, or even receipts for upgraded locks. This documentation serves as tangible proof of your protective measures. When you talk to an insurer like Hagerty, being able to present this kind of detailed information makes their job easier and often results in more favorable terms. This attention to detail can directly contribute to How to Save on Classic Car Insurance.
The Importance of Designated Classic Car Storage
For some collectors, especially those with multiple vehicles or those living in urban areas without adequate home garage space, off-site, designated classic car storage facilities are an excellent option. These facilities are specifically designed to house high-value vehicles, often offering climate control, advanced security systems (24/7 surveillance, armed guards, biometric access), and sometimes even trickle chargers.
While these facilities come with a cost, they often lead to the best possible insurance rates because the risk profile is exceptionally low. Insurers trust these professional storage solutions. If you opt for such a facility, ensure you get documentation from them detailing their security measures. Presenting this to your insurer can unlock the lowest possible premiums for your classic. It's a prime example of how Storage Options Specialty Insurers Accept can influence your policy.
Common Misconceptions and What to Watch Out For
Navigating classic car insurance can be tricky, and some common misunderstandings can lead to unexpected coverage gaps or higher costs. It's vital to be clear on what your policy truly covers and what it expects from your storage arrangements.
"My Homeowners Policy Covers It, Right?"
This is one of the biggest pitfalls collectors fall into. Many assume that because their classic car is parked in their home garage, their standard homeowner's insurance policy will cover it if something happens. Unfortunately, this is almost never the case for a truly collectible vehicle, especially when it comes to comprehensive damage or theft.
Homeowners policies are designed to cover the structure of your home and its contents, and while they might offer minimal coverage for a car within the garage, it's typically very limited and often excludes vehicles entirely or covers them only for a tiny, depreciated amount (Actual Cash Value). They definitely won't offer the specialized protection, like Agreed Value Coverage for Classic Cars Explained, that classic car insurance provides. If your $75,000 vintage Porsche is stolen from your garage and you're relying solely on your homeowners policy, you're likely to be severely undercompensated, if compensated at all. Always ensure you have a dedicated classic car policy for your treasured vehicle. These policies are crafted specifically to protect the unique value and needs of a collectible car, including how it's stored.
The 'Daily Driver' Garage Fallacy
Another common misunderstanding is thinking that the garage requirements for a classic car policy are the same as for a regular daily driver. They are not. Most standard auto insurance policies for modern vehicles don't care much about where your car is parked overnight, as long as it's legal. They assume your car will be driven frequently and exposed to various risks as part of its daily routine.
Classic car insurers operate on a different premise. They expect classic cars to be used sparingly, primarily for pleasure drives, car shows, and club events, not as regular transportation. This "pleasure-use" requirement is often tied directly to the expectation of secure storage. If you tell an insurer you have a secure garage, but then use your classic as a Classic Car Insurance for a Daily Driver, you could run into serious issues during a claim. For instance, if your policy has a strict mileage limit and requires garage storage, but you've been driving it daily and parking it outside frequently, an insurer could deny a claim if they find out you misrepresented your usage and storage habits. Be honest and clear with your insurer about how you use and store your vehicle to ensure proper coverage and avoid unpleasant surprises. If your classic needs to be driven more frequently, discuss this with potential insurers as some, like Hagerty and American Collectors Insurance, offer more flexible mileage plans, though they might still have garage storage stipulations.
Ultimately, your garage isn't just a place to park; it's a critical component of your classic car's overall protection and directly influences the cost and availability of your insurance. Invest in good security, document everything, and be transparent with your insurer, and you'll be well on your way to securing excellent coverage for your automotive pride and joy. To learn more about tailoring your policy, check out How to Build a Complete Classic Car Policy.
Disclaimer
Please remember that insurance policies, coverage, and requirements can vary significantly. This guide provides general information and recommendations. Always consult directly with a qualified insurance professional or your chosen classic car insurance provider to discuss your specific needs, understand your policy details, and confirm eligibility and coverage specifics for your unique situation.