Coverage for a Multi-Car Collection
Owning a collection of classic cars is a dream come true for many, but the logistical headache of insuring each prized possession can quickly turn that joy into frustration. Juggling multiple policies with different renewal dates, varying coverage limits, and a patchwork of rules for each vehicle is not just inconvenient—it can lead to coverage gaps and unnecessary expenses. This comprehensive guide will walk you through everything you need to know about getting coverage for a multi-car collection, ensuring all your beauties are protected under one streamlined policy.
Understanding Multi-Car Collection Policies
When you've poured your heart, soul, and hard-earned cash into building a collection of classic cars, the last thing you want is a generic insurance policy that doesn't understand their unique value. A multi-car collection policy is specifically designed for enthusiasts like us, offering a tailored approach that standard auto insurance simply can't match. It’s more than just adding several vehicles to a single account; it's about a consolidated, specialized strategy that recognizes the collective passion and investment you’ve made.
What Makes a Policy "Multi-Car Collection"?
At its heart, a multi-car collection policy isn't just about insuring multiple vehicles; it's about insuring a collection of vehicles. Instead of separate policies for each classic — say, one for your '67 Mustang, another for your '57 Chevy Bel Air, and a third for your vintage Porsche 911 — a collection policy brings them all under one umbrella. This means a single premium, a single renewal date, and a unified set of terms and conditions that apply to every vehicle listed.
Imagine Mr. Johnson, a passionate collector from Phoenix, Arizona, with his three classic Mustangs: a meticulously restored '65 convertible, a '69 Mach 1 undergoing a frame-off restoration, and a clean '70 Boss 302 he drives to local shows. If he tried to insure each of these through individual policies with different carriers, he’d be buried in paperwork, struggling to remember which policy covered what, and likely missing out on significant savings. A multi-car collection policy simplifies this immensely, recognizing that these aren't just three random cars; they are a cohesive collection deserving of consistent, specialized protection. This approach simplifies claims, making it far less confusing if, heaven forbid, something happens to one of your treasured machines.
The Core Advantages for Collectors
The benefits of a multi-car collection policy extend far beyond mere convenience. For dedicated enthusiasts, these policies offer financial and administrative advantages that are simply unavailable through standard or piecemeal coverage.
Firstly, cost savings are a huge draw. Specialty classic car insurers understand that collectors often treat their vehicles with an exceptional level of care, drive them sparingly, and store them securely. Because the risk profile for a classic car collection is generally lower than for a fleet of daily drivers, insurers can offer more favorable rates. When you bundle several classics together, these savings are often amplified through multi-car discounts. This is why many collectors find that a multi-car policy from a specialist like Hagerty or Grundy is often significantly more affordable than trying to insure each classic separately through a standard carrier. It’s an acknowledgment of your dedication to preservation and careful ownership. You might be surprised just how much you can save, and that extra cash can go right back into your passion, perhaps for a new set of tires or that elusive part you've been searching for.
Secondly, the administrative simplification is a game-changer. Instead of receiving multiple bills, dealing with several agents, and tracking different policy expiration dates, you have one point of contact and one streamlined process. This means less time on the phone with insurance companies and more time in the garage, enjoying your cars. This consolidated approach also ensures consistent coverage terms across your entire fleet. You won't have to worry about one car having a better agreed value clause or superior roadside assistance than another. Every car in your collection benefits from the same high level of protection, giving you unparalleled peace of mind. This consistency is particularly important when considering specific terms like those found in Classic Car Insurance Requirements Explained.
Key Coverage Components for Your Fleet
When you're insuring a collection, you're not just covering vehicles; you're protecting investments, memories, and countless hours of labor. Therefore, the types of coverage you select are paramount. A robust multi-car policy will offer specialized options that cater directly to the unique needs of classic and collector vehicles, ensuring that the true value of each car in your collection is recognized and protected.
Agreed Value Across All Your Classics
This is perhaps the most critical component of any classic car insurance policy, and it's even more vital when you have a multi-car collection. Unlike standard auto insurance, which typically uses "Actual Cash Value" (ACV) or "Stated Value" that can leave you drastically underinsured, an "Agreed Value" policy ensures that you and the insurer agree on your car's value before the policy is issued. In the event of a total loss, you receive that exact agreed-upon amount, no depreciation deductions.
For a multi-car collection, this means each vehicle gets its own specific agreed value. This is incredibly important because a '69 Camaro Z/28, a '63 Corvette Split-Window, and a 1932 Ford hot rod will all have vastly different market values, even if they're part of the same collection. Your insurer should work with you to establish these values, often relying on appraisals, market data, and your vehicle's documentation. Updating these values periodically is also crucial, especially for cars that appreciate. For instance, if your Datsun 240Z has significantly increased in market value since you last renewed, you'll want to ensure its agreed value reflects that. An insurer like Hagerty offers robust valuation tools to help keep these figures current. You can learn more about how this works in detail in our guide on Agreed Value Coverage Explained. Without agreed value coverage, you risk a devastating financial loss should one of your prized possessions be totaled, making it a non-negotiable for serious collectors.
Comprehensive and Collision for Each Vehicle
While agreed value protects against total loss, comprehensive and collision cover the more common, albeit still heartbreaking, incidents that can befall your classics. These coverages apply to each individual vehicle within your multi-car collection policy.
- Collision Coverage: This pays for damages to your insured classic resulting from a collision with another vehicle or object, regardless of who is at fault. Think about cruising to a local car show and someone backs into your cherished 1957 Chevrolet Bel Air in the parking lot. Or, maybe you misjudge a tight turn in your garage and scrape a fender. Collision coverage ensures these repairs are covered, protecting the investment in your vehicle's pristine condition. Given the rising cost of classic car repairs and specialized parts, having solid collision coverage is paramount.
- Comprehensive Coverage: This steps in for damages not caused by a collision. We're talking about theft, vandalism, fire, natural disasters like hail or floods, or even striking an animal. Imagine a severe hailstorm rolling through while your collection is stored, causing dimples across several cars. Comprehensive coverage would handle those repairs. It also covers theft, which, unfortunately, is a real concern for highly desirable classic vehicles. You absolutely want to ensure your coverage is robust, as detailed in discussions like Do Classic Cars Need Full Coverage. These coverages are crucial for every car in your collection, providing a safety net against unforeseen events that could otherwise lead to massive out-of-pocket expenses.
Liability Coverage for the Entire Collection
Even if your classics are driven sparingly, liability coverage is not optional; it's a legal necessity in most places and a financial safeguard for your assets. This coverage protects you if you're at fault for an accident that causes bodily injury or property damage to others while driving one of your collection vehicles.
A multi-car collection policy will typically apply liability coverage to any of your listed vehicles being operated. This means if you lend your 1965 Corvette to a trusted friend for a charity rally (with permission and within policy guidelines, of course) and they are involved in an at-fault accident, your liability coverage would respond. The key here is ensuring you have sufficient liability limits. Given the potential for significant legal judgments, especially in accidents involving serious injury, having high liability limits is crucial to protect your entire collection and other personal assets. Many states have minimum liability requirements, but these are often woefully inadequate for collectors. Always consider umbrella insurance for an extra layer of protection above your auto policy's limits. For specific state details, check out our article on Classic Car Liability Requirements by State. Don't skimp on liability; it's the foundation of protecting yourself financially.
Specialized Add-Ons for Collectors
Beyond the core coverages, specialty classic car insurance really shines with its array of add-ons designed specifically for the collector lifestyle. These endorsements address unique scenarios that standard policies simply wouldn't consider, offering granular protection that truly understands your passion.
Restoration and Vehicle Under Construction Coverage
For many collectors, the journey of bringing a classic back to life is as rewarding as owning the finished product. But what happens if something goes wrong during a restoration? Standard policies often fall short, valuing a partially disassembled car at far less than your investment. That's where restoration and vehicle under construction coverage comes in.
This specialized add-on protects your classic while it's in various stages of restoration, whether it's a bare frame, a body-in-white, or a nearly complete show car. It recognizes that the value of your project increases significantly with every hour of labor and every new part installed. Instead of a fixed value, this coverage often allows you to periodically update the agreed value as you invest more into the project. For example, if you began restoring a '69 Charger as a non-running project, and after a year, you've invested tens of thousands in engine work, body repairs, and a fresh paint job, this coverage ensures your policy value keeps pace with your investment. It covers theft of parts, fire in the garage, or damage while being transported to a specialist shop. Without it, a garage fire could wipe out years of effort and investment with little compensation. Our article on Restoration Coverage for Classic Cars delves deeper into how this works and why it's vital for any active project car.
Spare Parts, Tools, and Automobilia Coverage
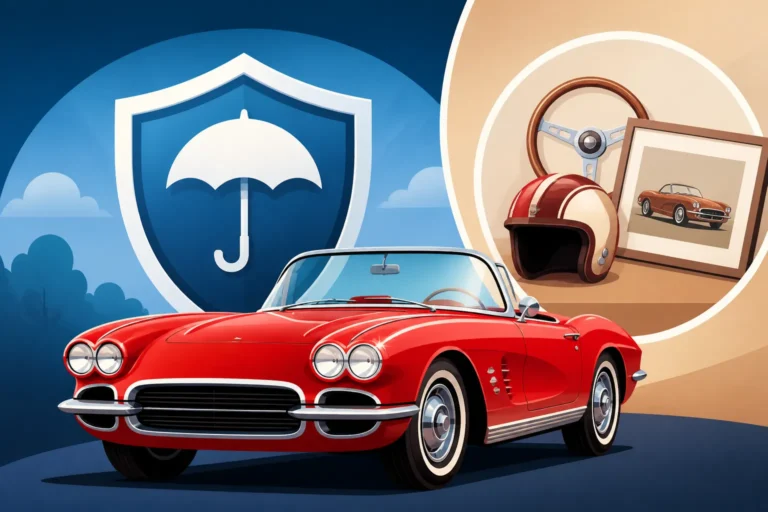
Collectors often have garages brimming with more than just cars. Rare New Old Stock (NOS) parts, unique vintage tools, automotive artwork, and signed memorabilia can represent a significant financial and sentimental investment. Standard home insurance policies typically have low limits for such specialized items, leaving you exposed.
This add-on is designed to protect these irreplaceable assets. It provides coverage for spare parts intended for your insured classics, whether they're still in their boxes or awaiting installation. Imagine Mr. Smith, whose garage holds a treasure trove of original chrome trim for his '66 Shelby GT350, a rare period-correct carburetor, and a signed poster from Carroll Shelby himself. If a pipe burst or a fire occurred, damaging these items, this specialized coverage would step in. Some policies even extend to tools used specifically for classic car maintenance and restoration. Always check the limits on this coverage, as it can vary. While some policies offer a blanket amount, others might allow you to schedule high-value individual items. It’s an often-overlooked but crucial protection for the true collector. You can find more information about protecting these assets in our guide on Spare Parts Coverage Explained.
Inflation Guard and Touring/Show Coverage
The classic car market is dynamic, with values often appreciating over time. An inflation guard endorsement automatically adjusts your agreed value upwards by a small percentage (e.g., 2-6%) each year to account for market appreciation, ensuring your classics aren't underinsured as their values climb. This means you don't have to constantly track market fluctuations and request manual updates, offering peace of mind that your collection's evolving worth is recognized. It's particularly useful for a multi-car collection, as all your vehicles benefit from this automatic adjustment. More details can be found in our explanation of Inflation Guard Coverage for Classic Cars Explained.
Furthermore, for collectors who love to show off their vehicles, touring and show coverage is essential. Many multi-car policies include, or allow you to add, coverage for your classics while they're being driven to, from, or displayed at car shows, club events, and rallies. This goes beyond standard comprehensive and collision by often including coverage for:
- Transit Damage: Protection while your car is being trailered or shipped to an event.
- Vandalism/Theft at Shows: Enhanced protection for situations unique to public displays.
- Trip Interruption: Some policies will even cover expenses if your classic breaks down far from home on a tour, covering lodging or rental car costs.
Consider Mrs. Davies, who regularly drives her collection of vintage European sports cars to events across the state. Without specific show and touring coverage, a breakdown or unforeseen incident far from home could be a logistical and financial nightmare. This add-on provides the peace of mind to truly enjoy your collection as intended.
Practical Considerations for Managing Your Collection Policy
Getting a multi-car collection policy is a smart move, but managing it effectively requires understanding the nuances and making informed choices. From eligibility to choosing the right partner, a bit of foresight can save you a lot of hassle down the road.
Eligibility Requirements for Multi-Car Policies
Just like any specialized insurance, multi-car collection policies come with certain eligibility criteria designed to ensure the vehicles are true classics and are cared for appropriately. While specifics vary between insurers, common requirements include:
- Age of Vehicles: Most insurers define a classic or antique based on age, typically 25 years or older for classics, and 45 years or older for antiques. However, some, like Hagerty, also cover "modern collectibles" (often 15-25 years old) or "future classics." All vehicles in your collection must meet their respective criteria.
- Limited Use: Your classics generally can't be daily drivers. They are expected to be used for pleasure driving, car shows, club events, and occasional errands. Most policies come with mileage limits, though some offer unlimited mileage options.
- Secure Storage: Insurers usually require your collection to be stored in a locked, private garage when not in use. This significantly reduces the risk of theft and vandalism. A simple carport or street parking might disqualify you.
- Other Vehicles: You typically need to have a separate, primary vehicle for daily transportation. The classics in your collection are supplemental, not substitutes, for your everyday ride.
- Driver History: A clean driving record for all household drivers can be a factor, especially for policies with specific age requirements for drivers.
Understanding these points is vital before you even start shopping. For a deeper dive into these criteria, refer to our comprehensive guide on Classic Car Insurance Eligibility Requirements. Meeting these requirements helps you qualify for the best rates and ensures your policy is valid when you need it most.
Choosing the Right Insurer for Your Collection
Not all insurance companies are created equal when it comes to classic car collections. Your local standard insurer might offer to add your classics to your regular policy, but they often lack the specialized coverage, agreed value options, and expertise that a true collector needs. This is where specialty classic car insurers excel.
Companies like Hagerty, Grundy, American Collectors Insurance, and American Modern Insurance Group are dedicated to the collector car market. They understand the nuances of classic car valuation, restoration, and the specific risks collectors face. When evaluating potential insurers for your multi-car collection, consider:
- Expertise in Valuations: Do they have a robust valuation system and experienced appraisers who understand the fluctuating market of specific models in your collection?
- Specialized Coverage Options: Do they offer all the crucial add-ons like restoration coverage, spare parts, and touring coverage that you might need?
- Claims Service: In the unfortunate event of a claim, do they have adjusters who specialize in classic cars and won't try to devalue your unique vehicle? Look for companies known for fair and prompt claim resolution.
- Customer Service: As a collector with multiple valuable assets, you want an insurer that offers personalized service and a deep understanding of your passion.
- Discounts: Many specialty insurers offer specific discounts for multi-car collections, car club memberships, and enhanced security measures.
It's highly recommended to compare quotes and coverage details from at least a few top-tier specialty providers. Our guide on Best Classic Car Insurance Companies provides a detailed comparison to help you make an informed decision. Remember, you're not just buying a policy; you're partnering with an insurer who will protect your automotive legacy.
Valuation and Appraisal for Multiple Vehicles
Accurately valuing each car in your multi-car collection is foundational to getting the right agreed-value coverage. This isn't a one-size-fits-all process; each vehicle needs individual attention.
Initial Valuation: When you first seek a quote, the insurer will ask for details about each car. Be prepared to provide:
- Year, Make, Model, VIN
- Condition (concours, excellent, good, driver)
- Any significant modifications or restoration work
- Mileage
- Any unique features, rare options, or documented history (e.g., provenance)
Many insurers, especially those specializing in classics like Hagerty, have extensive databases and expert staff to help you arrive at a fair agreed value for each vehicle. For high-value, rare, or heavily modified vehicles, a professional appraisal from an independent, certified appraiser might be required or highly recommended. This appraisal provides a detailed, objective assessment of your car's condition and market value, which acts as a strong basis for your agreed value with the insurer.
Maintaining Current Valuations: The classic car market changes, and your cars might undergo further restoration or modifications that increase their value. It's crucial to periodically review and update the agreed value for each vehicle in your collection. A general rule of thumb is to review values annually, especially before renewal. If you've just completed a significant restoration on your project car, or if a particular model in your collection has seen a surge in market demand, inform your insurer and provide updated documentation or another appraisal. This proactive approach ensures you're always adequately covered. You can learn more about this process in our article on How Classic Car Appraisals Work for Insurance. Don't assume your agreed value automatically keeps pace; active management of your valuations is key to protecting your investment.
Single-Car vs. Multi-Car Collection Policy Comparison
To truly appreciate the advantages, let's look at how a multi-car collection policy stacks up against insuring each classic separately.
| Feature | Single-Car Policy (for each classic) | Multi-Car Collection Policy |
|---|---|---|
| Billing | Separate bills, different due dates, fragmented | One consolidated bill, single due date, streamlined |
| Discounts | Limited; may miss out on multi-car or collection-specific | Often includes multi-car discounts, club discounts, collection benefits |
| Coverage Terms | Can vary wildly between different carriers or policies | Consistent agreed value and coverage terms across all vehicles |
| Claims Process | Potentially multiple claims departments, varied experiences | Single point of contact, specialized claims handling for classics |
| Admin Burden | High; multiple renewals, documents, and points of contact | Low; one policy document, one renewal, one primary contact |
| Flexibility | Adding/removing vehicles means new policy setup each time | Easily add/remove vehicles to existing master policy |
| Specialty Options | May be available, but often less comprehensive or coordinated | Fully integrated, robust specialty coverages (restoration, parts, etc.) |
| Cost Efficiency | Often higher due to lack of collection-specific pricing | Generally more cost-effective due to bundled pricing and discounts |
As you can see, for any serious collector, the multi-car collection policy is almost always the superior choice. It offers not only peace of mind but also significant efficiencies in both cost and time. When it's time to get quotes, remember to ask about specific multi-car discounts, as covered in our guide on Multi-Car Discount for Classic Collections, and compare the full breadth of coverage, not just the premium. You'll likely find that a specialty insurer is your best bet when you want to learn How to Compare Classic Car Insurance Quotes for multiple vehicles.
Disclaimer
Please remember that insurance policies can vary greatly, and the information provided here is for general guidance only. It is crucial to review the specifics of any policy with a licensed insurance professional to ensure it meets your individual needs and covers all your unique classic vehicles appropriately. Always read your policy documents carefully.