How Trip Interruption Coverage Works for Collectors
There’s nothing quite like hitting the open road in your beloved classic car, feeling the wind in your hair and the rumble of a vintage engine beneath you. It’s a dream for many, but for seasoned collectors, there’s also that nagging worry in the back of your mind: what if something goes wrong far from home? This guide is here to dive deep into trip interruption coverage, an often-overlooked but incredibly valuable component of classic car insurance designed to ease those fears and get you back on track when the unexpected happens.
Understanding the Reality of Classic Car Road Trips
Owning a classic car isn't just about polishing chrome and attending shows; it's about the experience of driving, of feeling history in your hands. But let's be honest, these aren't brand-new, perfectly reliable daily drivers. Taking your treasured classic on a long road trip, even a cross-state rally, comes with a unique set of challenges that modern vehicles rarely present.
The Unique Risks of Older Vehicles
Modern cars have sophisticated diagnostic systems, readily available parts, and legions of mechanics trained to fix them. Classic cars? Not so much. A 1960s muscle car, a vintage European roadster, or even a '70s sedan, no matter how meticulously maintained, can surprise you with an unexpected mechanical hiccup. A fuel pump might fail, an electrical short could emerge, or a gasket might finally give up the ghost. Finding a mechanic who truly understands carbureted engines or non-computerized systems in a rural town in, say, Nebraska, can be a monumental task. You might be miles from the nearest specialist, or even the right parts supplier, turning a minor issue into a major logistical headache. This is where specialized classic car insurance, like policies offered by companies such as Hagerty, truly shines by offering tailored solutions beyond a standard auto policy.
The Emotional Toll of a Stranded Classic
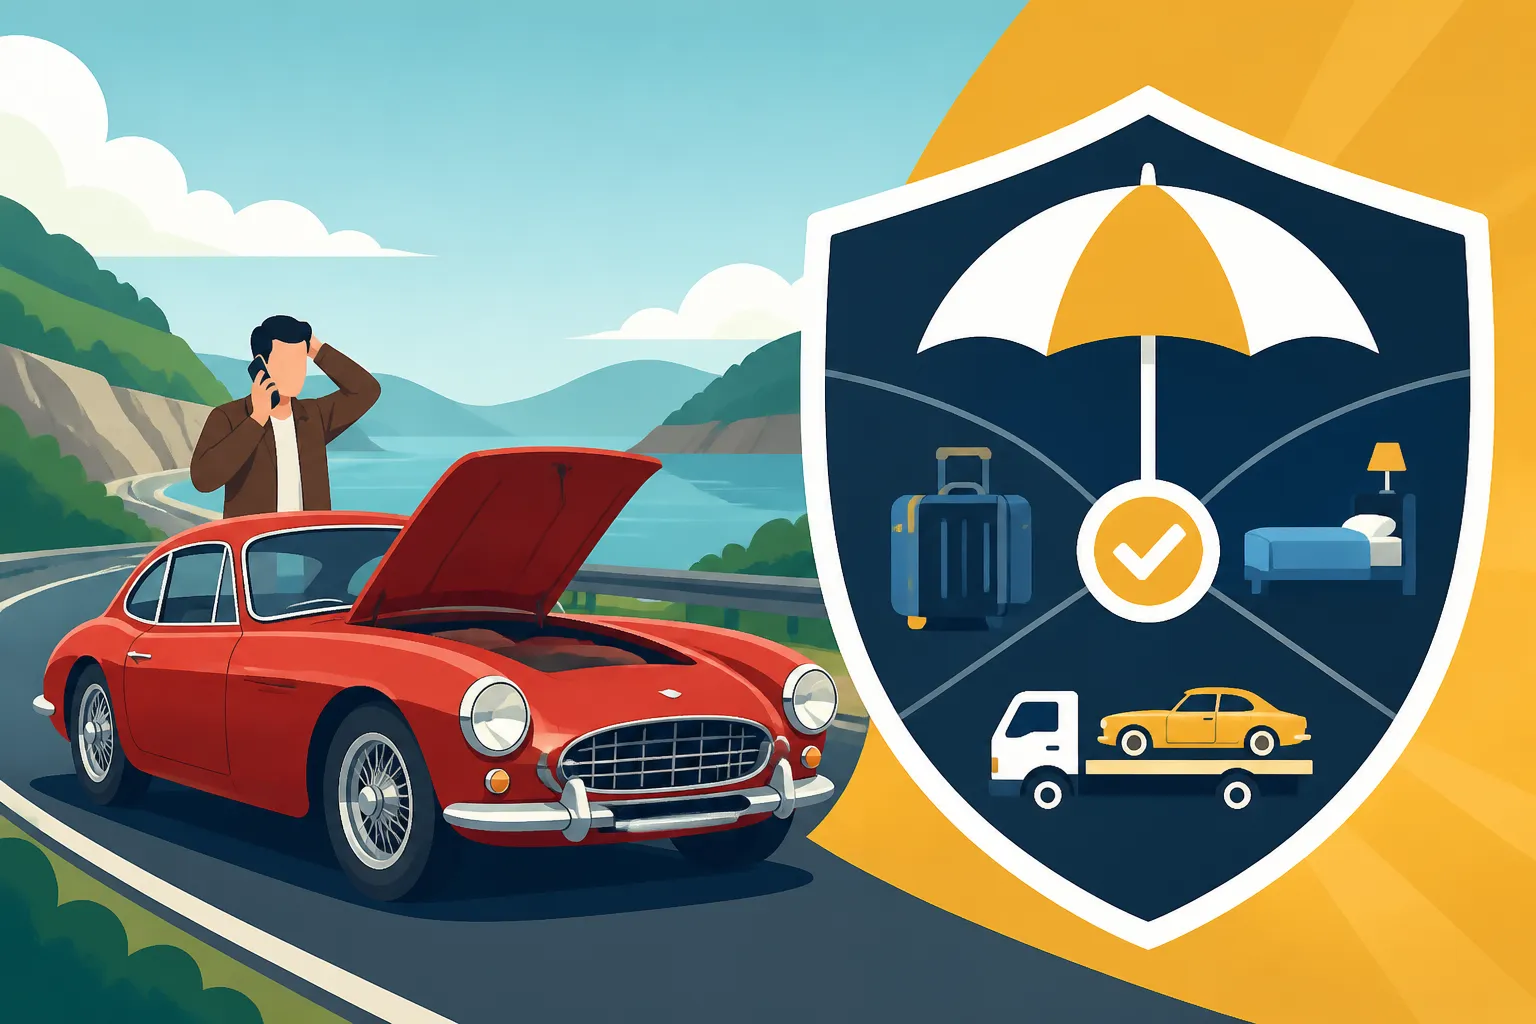
Beyond the mechanical woes, there's the emotional impact. Imagine you're on a long-planned road trip, perhaps heading to a major classic car show like the one in Amelia Island, and your prized possession breaks down 500 miles from your garage. It's not just a car; it's a part of your passion, an investment of time, money, and love. The stress of being stranded, potentially having to leave your car with an unfamiliar shop, and figuring out how you and your companions will get home or continue your journey, can quickly turn an enjoyable adventure into a nightmare. This isn't just about getting the car fixed; it's about mitigating the disruption to your life and travel plans. Understanding what your policy offers, especially regarding things like Roadside Assistance Coverage for Classic Cars Explained, can make all the difference.
What is Trip Interruption Coverage and Why Collectors Need It
So, what exactly is trip interruption coverage, and why is it such a vital component for classic car collectors who actually drive their vehicles? It’s essentially a safety net for your travel plans, specifically designed to help you out when your classic car has an insured breakdown or accident far from home.
Defining Trip Interruption Benefits
Trip interruption coverage, an excellent add-on available with many specialty classic car insurance policies, is there to help with the unexpected expenses that arise when your classic car suffers a covered mechanical failure or accident more than a certain distance from your primary residence (often 50 or 100 miles, depending on the insurer). These expenses can quickly add up, turning an inconvenience into a financial burden. Think about it: if your vintage Mustang throws a rod 300 miles from home, you're looking at more than just a repair bill. You might need a rental car to get home, a hotel stay while your car is assessed, or even alternative transportation for yourself and any passengers. This coverage helps reimburse you for these unforeseen costs, allowing you to focus on getting your vehicle sorted rather than stressing over the immediate travel logistics. It's a key part of building a complete Classic Car Insurance Coverage Types Explained.
How It Differs from Standard Roadside Assistance
It's easy to confuse trip interruption coverage with standard roadside assistance, but they serve different, albeit complementary, purposes. Roadside assistance, which is also a must-have for classic car owners, typically covers immediate services like towing your disabled vehicle to the nearest qualified repair shop, jump-starts, tire changes, or fuel delivery. This gets your car off the side of the road and to a place where repairs can begin.
However, roadside assistance usually stops there. It doesn't typically cover the consequential costs of being stranded. This is where trip interruption coverage steps in. While roadside assistance gets your car towed, trip interruption coverage provides financial relief for the lodging, meals, and alternative transportation you might need because your car is being repaired or you need to return home. For example, if your classic breaks down near Barstow, California, and needs a week in the shop, roadside assistance will get it there. Trip interruption coverage could then help pay for your hotel stay while you wait for parts or a flight home. It’s an essential part of Classic Car Insurance Add-Ons and Endorsements.
Key Components and Eligibility for Coverage
When looking into trip interruption coverage, it's crucial to understand what it covers, what it doesn't, and what criteria you and your vehicle need to meet to be eligible. Every insurer's policy details will vary, so always read the fine print.
What Expenses are Typically Covered
The beauty of trip interruption coverage is its focus on mitigating the immediate financial impact of being stranded. Here are the types of expenses commonly covered:
- Lodging: If your classic breaks down and repairs can't be completed immediately, you might need a hotel room. This coverage helps with those overnight stays.
- Meals: Eating out can add up quickly, especially if you're stuck for a few days. Many policies will reimburse for reasonable meal expenses during the interruption.
- Alternate Transportation: This is a big one. It could mean a rental car to continue your journey, return home, or even a plane ticket if you're too far to drive. Some policies, like those from Hagerty, specifically offer this to ensure you're not left high and dry.
- Commercial Travel: In some cases, if you're far from home, the most practical solution might be a train or bus ticket to get you where you need to be.
- Return Trip Home: If the repair takes an extended period, the policy might cover the cost to get you and your passengers back to your primary residence.
Most policies will have a maximum limit for these combined expenses, often a per-incident limit (e.g., up to $600 or $1,000) and sometimes a per-day limit (e.g., $150/day). You'll usually need to be a certain distance from home, often 50 to 100 miles, for the coverage to activate.
Common Exclusions and Limitations
While incredibly helpful, trip interruption coverage isn't a blank check. There are always some exclusions and limitations to be aware of:
- Routine Maintenance: This coverage is for unexpected breakdowns or accidents, not for scheduled servicing or issues that arise from neglecting maintenance. If your tires are bald and blow out, that's generally not covered.
- Pre-Existing Conditions: If your car had a known issue before the trip that led to the breakdown, it might not be covered.
- Non-Covered Perils: The interruption must stem from a "covered peril" as defined in your policy – typically a mechanical breakdown, collision, or other comprehensive loss (like fire or theft). Running out of gas intentionally, for example, wouldn't count.
- Maximum Limits: As mentioned, there will be financial caps on how much the policy will pay out per incident and sometimes per day. Make sure you're aware of these limits.
- Distance Requirement: You absolutely must be beyond the specified mileage radius from your home address for the coverage to kick in. A breakdown two towns over won't qualify.
- Non-Collectible Vehicles: This coverage is exclusively for the classic car insured under the specialty policy. It won't cover breakdowns of your modern daily driver. If you're wondering Do You Need a Separate Car for Classic Insurance, the answer is usually yes for these specialty benefits.
Who Qualifies for Trip Interruption Assistance
Generally, if you hold a classic car insurance policy that includes trip interruption coverage, and your vehicle meets the insurer's criteria for a classic, you're likely eligible. The primary driver and any passengers legally traveling with them would typically qualify for the benefits.
However, certain conditions must be met:
- Active Policy: Your classic car insurance policy must be active and in good standing at the time of the incident.
- Covered Incident: The interruption must be due to a covered mechanical breakdown or accident.
- Mileage Restriction Adherence: If your policy has mileage limits (e.g., Classic Car Insurance Mileage Limits by State), you must be operating within those limits. Exceeding them could void your coverage.
- Designated Drivers: The person driving the classic at the time of the incident should be a named insured or an approved driver on the policy. This is important to remember, especially if you have other household members who occasionally drive the classic.
These policies are generally designed for "pleasure use" vehicles, meaning they aren't used for daily commuting or commercial purposes. This use restriction helps keep premiums affordable and ensures the coverage is targeted at true collector situations.
Navigating a Claim and Maximizing Your Benefits
Dealing with a classic car breakdown is stressful enough. Knowing how to efficiently file a trip interruption claim can help alleviate some of that burden and ensure you receive the benefits you're entitled to.
Step-by-Step Guide to Filing a Claim
When your classic decides to take an unscheduled break, here’s a typical process for utilizing your trip interruption coverage:
- Safety First: Pull over to a safe location, if possible. Ensure everyone is out of harm's way.
- Contact Roadside Assistance: Your first call should almost always be to your classic car insurer's roadside assistance line. This service, often included with policies from companies like American Collectors Insurance or Grundy, will arrange for a tow to a qualified mechanic. Make sure you understand Towing Coverage for Classic Cars Explained.
- Notify Your Insurer About the Interruption: Once the car is safely at a shop and you know it won't be a quick fix, contact your insurance provider (or their dedicated claims line) to initiate a trip interruption claim. Explain the situation, provide your location, and describe the nature of the breakdown.
- Confirm Coverage Details: Ask your claims representative about your specific policy limits for lodging, meals, and alternative transportation, and any per-day or per-incident caps. Clarify the "distance from home" requirement to ensure you qualify.
- Keep All Receipts: This is absolutely critical. Any expenses you incur for hotels, meals, or alternative travel must be meticulously documented with receipts. Your insurer will require these for reimbursement.
- Follow Instructions: Your claims adjuster will guide you on next steps, such as approved repair facilities or how to arrange rental vehicles if needed. Adhere to their instructions to ensure a smooth claims process.
Documentation and Communication Best Practices
To make your trip interruption claim as seamless as possible, good documentation and clear communication are key.
- Detailed Records: Don't just keep receipts; consider making notes of dates, times, and why each expense was necessary. For example, "Hotel stay on May 15th because car required a part not available until May 17th."
- Photos: If it’s safe to do so, take photos of the breakdown location or the specific issue (if visible) on your car. While not always required for trip interruption, it can be helpful for the overall claim.
- Communication Log: Keep a log of every call or email with your insurance company and the repair shop. Note the date, time, who you spoke with, and what was discussed. This can be invaluable if any discrepancies arise later.
- Original Repair Invoice: Once your car is repaired, you'll need the repair invoice detailing the work done. This helps the insurer verify the covered incident.
- Timeliness: File your claim and submit documentation promptly. Delays can complicate the process.
Being prepared with this information will not only speed up your reimbursement but also reduce the stress during an already frustrating situation. For serious collectors, understanding comprehensive protection, including Do Classic Cars Need Full Coverage, is paramount.
Here's a quick look at typical expenses covered under trip interruption policies:
| Expense Category | Description | Typical Reimbursement Details |
|---|---|---|
| Lodging | Hotel stays due to car repairs taking longer than a day. | Up to a specified daily limit (e.g., $150-$200) for X nights. |
| Meals | Food expenses incurred while stranded away from home. | Often a daily limit per person (e.g., $50-$75). |
| Alternative Transportation | Rental car, train, bus, or airfare to continue trip or return home. | Up to a specified maximum (e.g., $500-$1,000 per incident). |
| Return Travel | Costs to travel back to the repair location to retrieve the repaired vehicle. | Included within the overall maximum limit. |
Remember, these are general guidelines, and your specific policy from providers like Hagerty will outline the exact limits and conditions. When you're ready to get coverage, it’s always a good idea to How to Compare Classic Car Insurance Quotes to find the best fit for your needs.
Disclaimer
Please remember that this information is intended for general guidance only and does not constitute legal or insurance advice. Policy terms, conditions, and coverage limits can vary significantly between insurance providers and specific policies. Always refer to your individual classic car insurance policy documents or consult directly with your insurance agent or provider to understand your exact coverage, exclusions, and limitations.