Agreed Value: How Payouts Work After a Total Loss
Few things sting as much as the thought of your cherished classic car, the one you've poured your heart, soul, and countless hours into, suffering a total loss. The emotional blow is one thing, but the financial devastation can be equally heartbreaking if you're not properly insured. That's where "agreed value" insurance comes in, offering a beacon of hope and a promise that if the worst happens, you'll receive a fair payout, reflecting the true worth of your pride and joy. This guide will walk you through exactly how agreed value payouts work after a total loss, providing clarity and peace of mind for every classic car owner.
Understanding Agreed Value in Classic Car Insurance
When it comes to insuring a classic car, the standard auto insurance model often falls woefully short. Your vintage Mustang isn't just transportation; it's a piece of history, an investment, and a passion project. That's why understanding agreed value coverage is absolutely paramount for any serious collector. It’s the cornerstone of protecting your unique asset.
What "Agreed Value" Truly Means
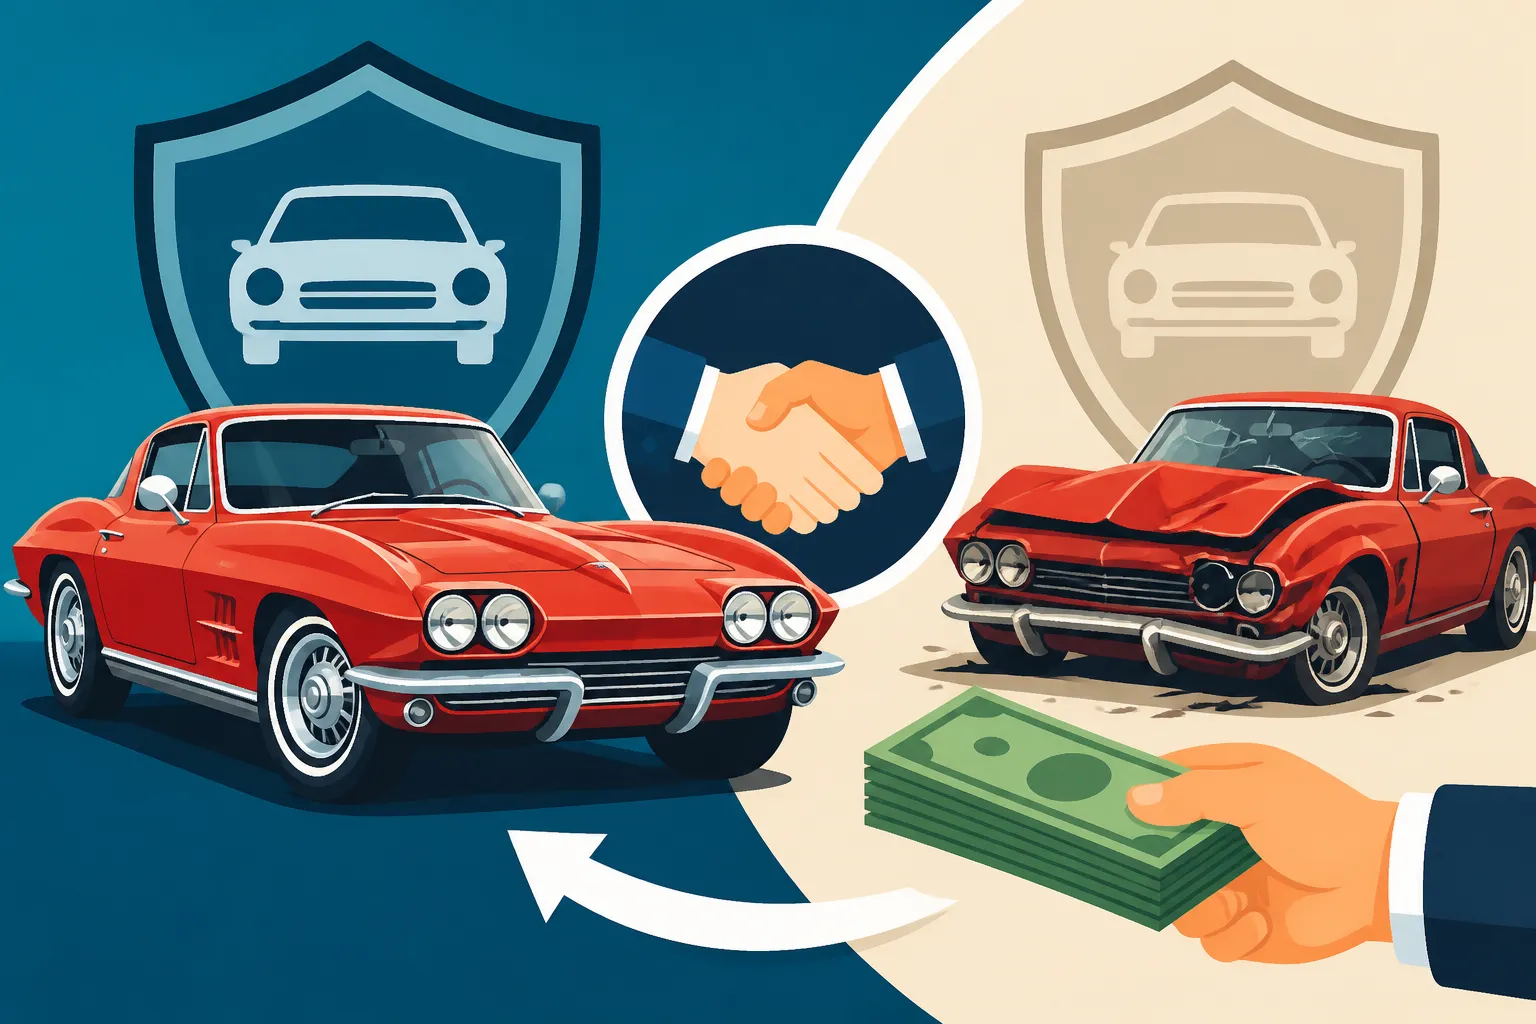
At its heart, "agreed value" is a commitment between you and your insurer on the exact dollar amount your classic car is worth at the beginning of your policy term. If your vehicle is ever declared a total loss, the insurance company will pay you that predetermined, agreed-upon amount, minus any applicable deductible, regardless of the market value at the time of the loss. This is a game-changer for classic car owners, and here’s why.
Unlike a standard auto policy that typically uses "Actual Cash Value" (ACV), which depreciates your vehicle's value over time, agreed value recognizes that classic cars often appreciate. ACV would pay you the replacement cost less depreciation, which for a 1969 Camaro could be shockingly low compared to its true collector value. Imagine lovingly restoring a vintage Triumph TR6, only for an accident to render it a total loss, and your standard insurer offers you a few thousand dollars based on depreciation. It's a nightmare scenario. That's why Why Agreed Value Matters for Classics is such a critical read for any enthusiast. Another common, but less favorable, option is "Stated Value." While it sounds similar to agreed value, Stated Value vs Agreed Value: Key Differences highlights how stated value policies often reserve the right for the insurer to pay out the stated value or the actual cash value or the cost to repair, whichever is less. This can leave you significantly underinsured and heartbroken. With true agreed value, there's no haggling over market fluctuations or depreciation; the agreed sum is what you get, period. This is the ultimate peace of mind.
Setting the Agreed Value
So, how do you arrive at this magical "agreed value"? It's a collaborative process that generally involves you, your insurer, and often an independent appraisal. Most specialty insurers, like Hagerty, rely on a combination of factors to help you determine this figure.
First, you'll provide detailed information about your classic. This includes its make, model, year, VIN, mileage, condition (concours, excellent, good, fair), any significant modifications or restorations, and its storage conditions. Pictures, especially high-quality ones documenting the interior, exterior, engine bay, and undercarriage, are incredibly helpful. For higher-value vehicles or those with extensive modifications, an independent appraisal is usually a mandatory step. A professional appraiser, specializing in classic and collector vehicles, will meticulously evaluate your car, considering its rarity, historical significance, condition, provenance (ownership history), and recent comparable sales. Their report provides an objective, third-party assessment of your car's value. You can learn more about this process in our guide on How Agreed Value Is Determined. Once all this information is gathered, you and the insurance company will agree on a specific monetary figure that represents your car's current fair market value for insurance purposes. This figure is then explicitly written into your policy.
The Total Loss Scenario: How Agreed Value Payouts Work
The thought of a total loss is agonizing, but knowing you have agreed value coverage can soften the blow significantly. It transitions the focus from arguing about your car's worth to rebuilding your collection or simply moving forward.
Defining a Total Loss for a Classic
A "total loss" doesn't necessarily mean your classic car is reduced to a pile of unrecognizable scrap metal. For insurance purposes, a vehicle is typically declared a total loss when the cost to repair the damage exceeds a certain percentage of its value, or when it's simply deemed unsafe or impractical to repair. With a classic car, this threshold might be different than a modern vehicle. For instance, if your 1970 Plymouth 'Cuda with an agreed value of $80,000 suffers $60,000 worth of damage, a standard insurer might repair it. But with a classic, even if the structural integrity can be fixed, the availability of original parts, the specialized labor required, and the impact on its collectible status might lead a specialty insurer to declare it a total loss, especially if the repair costs approach the agreed value.
In some cases, the decision might even come down to what's best for preserving the car's long-term value. If a repair involves extensive non-original parts or compromises its historical accuracy, a total loss declaration might be preferable, allowing you to receive the agreed value and potentially find a more original replacement. This nuanced approach is one of the key benefits of working with insurers who truly understand classic cars.
The Payout Process Step-by-Step
When a total loss occurs, the process, while still stressful, is streamlined thanks to agreed value. Here's a general outline:
- Report the Claim Immediately: Contact your insurance provider as soon as safely possible after the incident. Provide them with all necessary details, including the date, time, location, circumstances of the loss, and any other parties involved.
- Assessment and Documentation: The insurer will assign a claims adjuster who specializes in classic cars. They will review the damage, potentially requiring photos, police reports, and any prior appraisal documents you submitted when setting your agreed value. This isn't about determining the value again, but confirming the damage and ensuring it qualifies as a total loss under your policy terms.
- Review Policy and Deductible: Your adjuster will confirm your agreed value amount and review your policy for any applicable deductibles. For instance, if your classic had an agreed value of $75,000 and your deductible was $500, your payout would be $74,500.
- Receive Your Payout: Once all documentation is complete and the total loss is confirmed, the insurance company will issue a check for the agreed value, minus your deductible. This is the beauty of agreed value: you're paid what you and the insurer agreed the car was worth, no surprises, no depreciation debates. This can happen relatively quickly once all the paperwork is in order.
Real-World Examples of Agreed Value Payouts
Let's look at a couple of scenarios to really drive this home:
-
Scenario A: The Garage Fire: Maria owns a meticulously restored 1967 Chevrolet Corvette, which she insured for an agreed value of $150,000 with American Collectors Insurance. One unfortunate night, a fire in her garage causes extensive damage to the 'Vette, rendering it a total loss. Even though the actual damage assessment might put the repair cost at $120,000 (which might be reparable for a regular car), due to the specialized nature of the parts and labor, and the impact on its collectible status, her insurer declares it a total loss. Because she had an agreed value policy, Maria receives a check for $150,000 (minus her deductible), allowing her to begin her search for another dream Corvette without financial hardship.
-
Scenario B: The Uninsured Driver: David is cruising his 1955 Ford Thunderbird, agreed value $60,000, through the countryside when an uninsured driver runs a stop sign, T-boning his beloved Bird. The frame is bent, and the body panels are severely crumpled. Despite the rarity and high cost of original parts, the structural damage is too extensive to repair economically without drastically diminishing its value. Since David wisely secured Uninsured Motorist Coverage for Classic Cars Explained as an add-on to his agreed value policy with a company like Grundy, and the car is a total loss, he receives the full $60,000 agreed value (minus deductible). Without agreed value, a standard policy might only offer him actual cash value, which for a car of that age could be a fraction of its true worth, leaving him significantly out of pocket.
Protecting Your Investment: Maximizing Your Agreed Value Policy
An agreed value policy is a fantastic tool, but it's not a set-it-and-forget-it solution. Like any valuable asset, your classic car's value can change, and your policy needs to reflect that to truly protect your investment.
Regular Valuation Reviews
Classic cars are unique; their values can fluctuate based on market trends, historical events, or even just increasing rarity. It's crucial to periodically review and update your agreed value. What your 1965 Porsche 356 was worth five years ago might be significantly different today, especially if you've done substantial work on it. Most specialty insurers recommend reviewing your agreed value annually or bi-annually. This is especially important if the market for your specific model is appreciating rapidly. For instance, if you bought a 1980s Toyota Supra ten years ago, its value has likely skyrocketed, and your original agreed value would severely underinsure it today. Our article on How to Increase Your Agreed Value Over Time offers practical advice on this vital step.
You don't want to find yourself in a situation where What Happens If Your Classic Is Worth More Than Agreed Value and you haven't updated your policy. This would leave you absorbing the difference out of your own pocket. Keep in mind that insurers like Hagerty also offer tools and resources to help you track market values, making these reviews much easier.
Documenting Your Classic's Condition and Modifications
Meticulous record-keeping is your best friend when it comes to agreed value. Every receipt, every photo, every service record contributes to the narrative of your car's value. Did you just complete a frame-off restoration? Document it with before, during, and after photos, itemized receipts for parts and labor, and any certifications. Did you upgrade the engine with period-correct performance parts? Keep those invoices.
This documentation isn't just for setting the initial agreed value; it also supports any adjustments you want to make down the line and strengthens your claim in the event of a loss. Imagine trying to explain tens of thousands of dollars in restoration work without a single receipt. It makes the insurer's job, and your claim, much harder. A detailed logbook, a dedicated folder for all paperwork, and digital backups of photos and videos are invaluable. This detailed evidence can also be critical if you ever need to get How to Get a Classic Car Appraisal to justify a higher agreed value.
Understanding Policy Specifics and Endorsements
While agreed value is the bedrock, a truly comprehensive classic car policy offers additional endorsements and coverages that protect various aspects of your hobby. Don't just focus on the big number; delve into the details.
For example, if you're undertaking a major rebuild, consider Restoration Coverage for Classic Cars Explained. This unique add-on can incrementally increase your car's agreed value as you invest more money and time into the restoration process. Many collectors also benefit from Spare Parts Coverage for Classic Cars Explained, which insures those invaluable NOS (New Old Stock) parts or entire spare engines you might have tucked away. And with the rising costs of everything, Inflation Guard Coverage for Classic Cars Explained can automatically adjust your agreed value upwards by a small percentage each year to keep pace with market appreciation, offering an extra layer of protection without you having to proactively update it. Don't overlook practical coverages like flatbed towing for roadside assistance, as standard tow trucks can cause further damage to delicate classics.
Common Misconceptions and Pitfalls
Even with the best intentions, classic car owners can sometimes stumble into pitfalls that undermine the protection offered by agreed value policies. Being aware of these common mistakes can save you a lot of grief.
Agreed Value vs. Stated Value: A Critical Difference
This is perhaps the most common and dangerous misconception. As touched on earlier, "stated value" sounds similar to "agreed value," but their payouts are fundamentally different. Many mainstream insurance companies that dabble in classic car insurance might offer "stated value" policies. With a stated value policy, the "stated" amount is often just the maximum the company might pay. However, they reserve the right to pay you the actual cash value (ACV) or market value at the time of the loss, whichever is lower.
Let's say you "stated" your 1972 Datsun 240Z was worth $35,000, but a year later, the market softens slightly, and the ACV is determined to be $30,000. In a total loss, a stated value policy might only pay you $30,000, not the $35,000 you expected. With an agreed value policy, there's no such loophole; if you agreed to $35,000, that's what you get. Always verify that your policy explicitly uses the term "Agreed Value" and understands its implications.
The Importance of a Reputable Specialty Insurer
You wouldn't take your vintage Ferrari to a quick-lube shop for an engine rebuild, would you? The same principle applies to insuring your classic. Mainstream insurance companies, while excellent for daily drivers, often lack the specialized knowledge, understanding, and policy structures needed for collector vehicles. Their adjusters are typically trained for modern cars and might not grasp the intricacies of classic car valuation, repair, or parts sourcing.
Specialty insurers, on the other hand, are designed specifically for the collector car market. Companies like Hagerty, Grundy, and American Collectors Insurance employ adjusters who are enthusiasts themselves. They understand the difference between an original carburetor and a modern reproduction, the value of period-correct paint, and the impact of a total loss on a rare model. They also offer the unique coverages and benefits that truly protect classics. When you're searching for Best Specialty Classic Car Insurers, look for those with a proven track record in the collector car community.
What Happens If Your Classic Is Worth More Than Agreed Value
This is a real concern, especially in a rapidly appreciating market or if you've invested heavily in restoration without updating your policy. If your classic car's actual market value at the time of a total loss is higher than your agreed value, you're essentially underinsured. The insurance company is only obligated to pay the agreed value, not the car's current, higher market value.
Consider a situation where your 1970 Dodge Challenger R/T was initially insured for an agreed value of $80,000 five years ago. Since then, muscle car values have soared, and you've put another $20,000 into a perfect restoration, bringing its current market value to $120,000. If it's totaled today, your payout would still be $80,000 (minus deductible), leaving you with a $40,000 shortfall. This scenario underscores why When to Update Your Classic Car's Agreed Value is not just good practice, but absolutely essential. Regular reviews and updates, especially after significant work or market shifts, are the only way to ensure your agreed value keeps pace with your car's true worth.
Comparing Classic Car Insurance Payout Models
To truly appreciate the value of an Agreed Value policy, it's helpful to see how it stacks up against other common payout models used in the automotive insurance world. This comparison highlights why specialty classic car insurance is non-negotiable for serious collectors.
| Payout Model | Description | How it Works for Classics | Collector Implications |
|---|---|---|---|
| Agreed Value | Insurer pays a pre-determined, fixed amount agreed upon at policy inception. | You and the insurer agree on $X value. If totaled, you get $X (minus deductible). | Ideal. Provides guaranteed payout, protects against depreciation, and recognizes true collector value. |
| Stated Value | Insurer may pay the stated amount, or ACV/market value, whichever is less. | You state $X value. If totaled, insurer pays $X, ACV, or repair cost, whichever is lowest. | Risky. Can lead to significant underpayment if market value or ACV is lower than stated value. |
| Actual Cash Value | Insurer pays replacement cost minus depreciation. | Insurer determines current market value and then subtracts depreciation based on age/wear. | Disastrous. Classics appreciate; ACV is designed for depreciation. Payouts would be shockingly low and insufficient. |
| Market Value | Insurer pays what the car is worth on the open market at the time of loss. | Insurer assesses current market conditions and recent sales for comparable vehicles. | Problematic. While better than ACV, it's subjective and open to interpretation, potentially leading to disputes and delays. |
This table clearly illustrates why classic car insurance requirements almost always emphasize an agreed value policy. It's the only method that truly respects the unique nature and value proposition of collector vehicles.
Final Thoughts on Agreed Value Payouts
The journey of owning a classic car is filled with joy, camaraderie, and the satisfaction of preserving automotive history. Part of that preservation, and indeed, the peace of mind that allows you to fully enjoy your passion, comes from robust, specialized insurance. Agreed value coverage, especially when paired with the right endorsements from a knowledgeable specialty insurer like Hagerty or Grundy, is the ultimate safeguard against the financial heartache of a total loss. It's more than just a policy; it's an assurance that your investment, your hard work, and your passion are truly protected. Don't compromise on this vital aspect of classic car ownership.
Disclaimer
Please remember that insurance policies can vary greatly depending on the provider, your location, and the specific terms and conditions of your individual agreement. This article provides general information and should not be considered legal or financial advice. Always consult with a qualified insurance professional to discuss your specific needs and ensure your classic car is properly covered.